BOARD CERTIFICATION EXAM STUDY GUIDES Lower Extremity Trauma
[Click on Image to Enlarge]
ME-P Free Advertising Consultation
The “Medical Executive-Post” is about connecting doctors, health care executives and modern consulting advisors. It’s about free-enterprise, business, practice, policy, personal financial planning and wealth building capitalism. We have an attitude that’s independent, outspoken, intelligent and so Next-Gen; often edgy, usually controversial. And, our consultants “got fly”, just like U. Read it! Write it! Post it! “Medical Executive-Post”. Call or email us for your FREE advertising and sales consultation TODAY [678.779.8597] E-mail: MarcinkoAdvisors1738@outlook.com
Medical & Surgical e-Consent Forms
ePodiatryConsentForms.com
iMBA Inc., OFFICES
Suite #5901 Wilbanks Drive, Norcross, Georgia, 30092 USA [1.678.779.8597]. Our location is real and we are now virtually enabled to assist new long distance clients and out-of-town colleagues.
ME-P Publishing
SEEKING INDUSTRY INFO PARTNERS?
If you want the opportunity to work with leading health care industry insiders, innovators and watchers, the “ME-P” may be right for you? We are unbiased and operate at the nexus of theoretical and applied R&D. Collaborate with us and you’ll put your brand in front of a smart & tightly focused demographic; one at the forefront of our emerging healthcare free marketplace of informed and professional “movers and shakers.” Our Ad Rate Card is available upon request [678-779-8597].
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit a RFP for speaking engagements: MarcinkoAdvisors@outlook.com
Posted on March 29, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
What exactly is an Expert Witness?
At D.E.Marcinko & Associates an “expert witness” possesses specialized knowledge in a particular field and is qualified to provide deposition or testimony in court and under oath. This testimony can be based on their personal experience, education, training and/or research. The role of an expert witness is to provide objective and unbiased opinions, analysis, and insights to help a lawyer, judge and/or jury understand technical or complex issues related to the case.
An expert witness can be called by either the prosecution or the defense in a legal case. The expert witness may be required to provide a written report or affidavit detailing their opinions, analyses and conclusions, and they may be asked to testify in court to provide oral testimony and answer questions from the judge and lawyers.
Posted on March 29, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
DEFINITIONS
By Staff Reporters
***
***
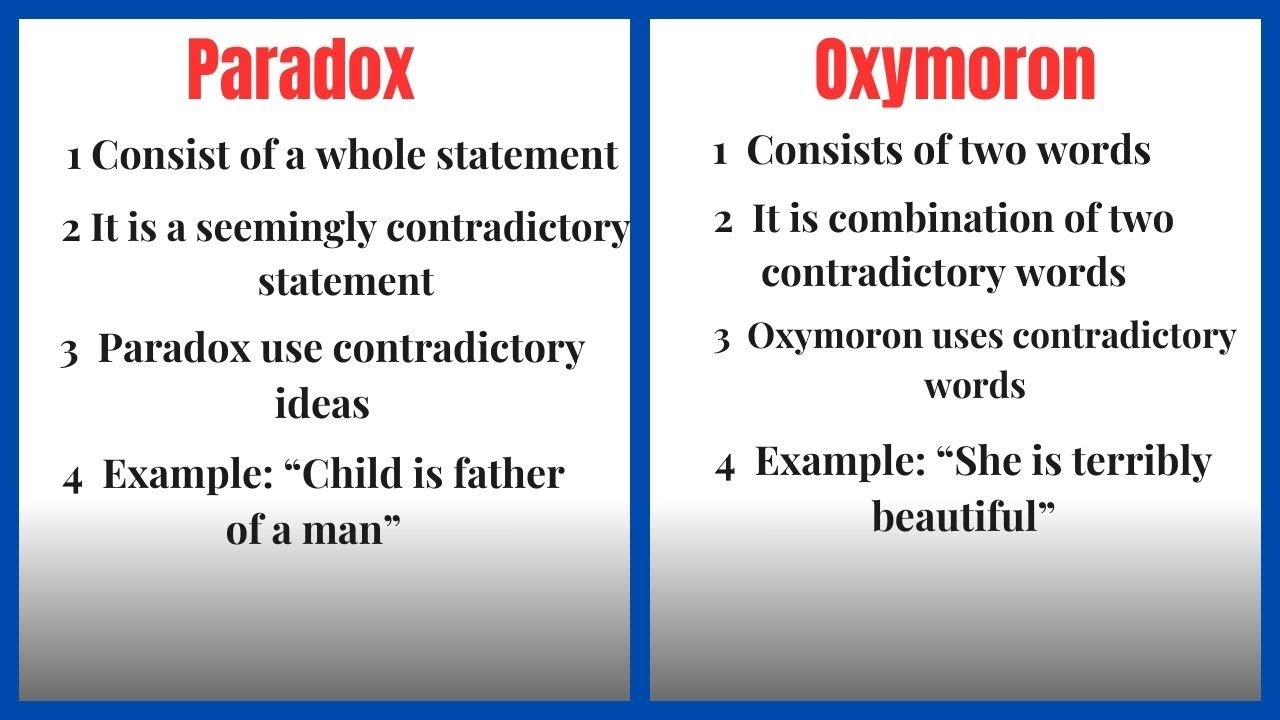
Paradoxes are broader concepts that may include statements, situations, or phenomena, revealing a truth through contradiction (e.g., “less is more”).
Oxymorons are combinations of two contradictory words to create a new meaning (e.g., “deafening silence”).
***
Most people tend to confuse a paradox with an oxymoron, and it’s not hard to see why. Most oxymoron examples appear to be compressed version of a paradox, in which it is used to add a dramatic effect and to emphasize contrasting thoughts. Although they may seem greatly similar in form, there are slight differences that set them apart.
A paradox consists of a statement with opposing definitions, while an oxymoron combines two contradictory terms to form a new meaning. But because an oxymoron can play out with just two words, it is often used to describe a given object or idea imaginatively.
As for a paradox, the statement itself makes you question whether something is true or false. It appears to contradict the truth, but if given a closer look, the truth is there but is merely implied.
In the first month of 2025, hospital revenue and expenses both increased, balancing each other out and resulting in continued steady financial performance for hospitals, according to Kaufman Hall’s January 2025 National Hospital Flash Report.
Revenues grew more quickly in the inpatient setting, as more patients were treated in the hospital and emergency department than in outpatient settings. While expense increases were largely driven by drug costs, the rate of that growth has significantly slowed.
This Health Capital Topics article reviews the report and the current state of hospital operations. (Read more…)
Posted on March 29, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
EDITOR-IN-CHIEF
By Dr. David Edward Marcinko; FACFAS MBA MEd
***
***
NATIONAL PHYSICIANS WEEK
National Physicians Week sets out March 25-31 to honor the healers dedicated to the art of medicine. In 2017, National Physicians Week highlighted the shortage of physicians in the United States against a growing landscape of minorities joining the ranks.
#NationalPhysiciansWeek
“In hindsight, I am proud of what we have accomplished in a short period of time, including raising the recognition of our group and spotlighting the years of sacrifice by those in our profession to serve our patients. We are poised to initiate actionable efforts to engage and educate our physician community.”
Cite: Dr. Kimberly Funches Jackson, President
Today in 2025, let’s explore the invaluable contributions of physicians, celebrate their hard work during National Physicians Week, and highlight the essential role that locum doctors play in enhancing healthcare delivery.
A Week to Honor All Physicians
National Physicians Week is a celebration of the remarkable work that doctors do every single day. From diagnosing complex conditions to providing life-saving treatments, physicians dedicate themselves to improving the health and well-being of their patients. It’s a week for healthcare professionals, patients, and communities to come together and show appreciation for the doctors who make a difference in our lives.
Physicians work long hours, face immense pressure, and make critical decisions daily. Their contributions go beyond the walls of the hospital, as many are also involved in research, teaching, and community outreach.
So, this week, it’s important to acknowledge not only their professional expertise but also the compassion and resilience they exhibit in their work.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit a RFP for speaking engagements: CONTACT: MarcinkoAdvisors@outlook.com
Posted on March 29, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
Dr. Jay Bhattacharya is officially the new NIH director. The Senate voted to confirm the Stanford University professor’s appointment on March 26 in a 53–47 vote. Marty MakaryMD was also confirmed as FDA commissioner in the same hearing in a 56–44 vote. The appointments come as additional “healthcare disruptors,” alongside Robert F. Kennedy Jr.’s confirmation as HHS secretary and Mehmet Oz’s nomination as head of the Centers for Medicare and Medicaid Services. The nominees have faced backlash from the medical community following their controversial stances on topics like vaccinations and alternative medical practices.
The Dow Jones Industrial Average (^DJI) dropped more than 700 points or nearly 1.7%, while the benchmark S&P 500 (^GSPC) fell almost 2%. The NASDAQ Composite (^IXIC) dropped 2.7% as tech stocks led the declines.
As noted above, the major averages fell on Friday after the release of a hotter-than-expected Personal Consumption Expenditures index reading, which includes the Federal Reserve’s preferred inflation gauge of “core” PCE. The reading showed prices increased more than expected last month, rising 0.4% month over month and 2.8% year over year, continuing a stubborn plateau on the path to the Fed’s 2% target.
Visualize: How private equity tangled banks in a web of debt, from the Financial Times.
Avram Noam Chomsky is an American professor known for his traditional work in linguistics and political activism. Sometimes called “the father of modern linguistics”, Chomsky is also one of the founders of the field of cognitive science. He is a laureate professor of linguistics at the University of Arizona and an professor emeritus at MIT.
And so, modern linguists today approach their work with scientific rigor and perspective [STEM], although they use methods that were once thought to be solely an academic discipline of the humanities.
Contrary to this humanitarian belief, according to Professor Mackenzie Hope Marcinko PhD of the University of Delaware, linguistics is now multidisciplinary. It overlaps each of the human sciences including psychology, neurology, anthropology, and sociology. Linguists conduct formal studies of sound structure, grammar and meaning, but also investigate the history of language families, and research language acquisition.
Posted on March 28, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
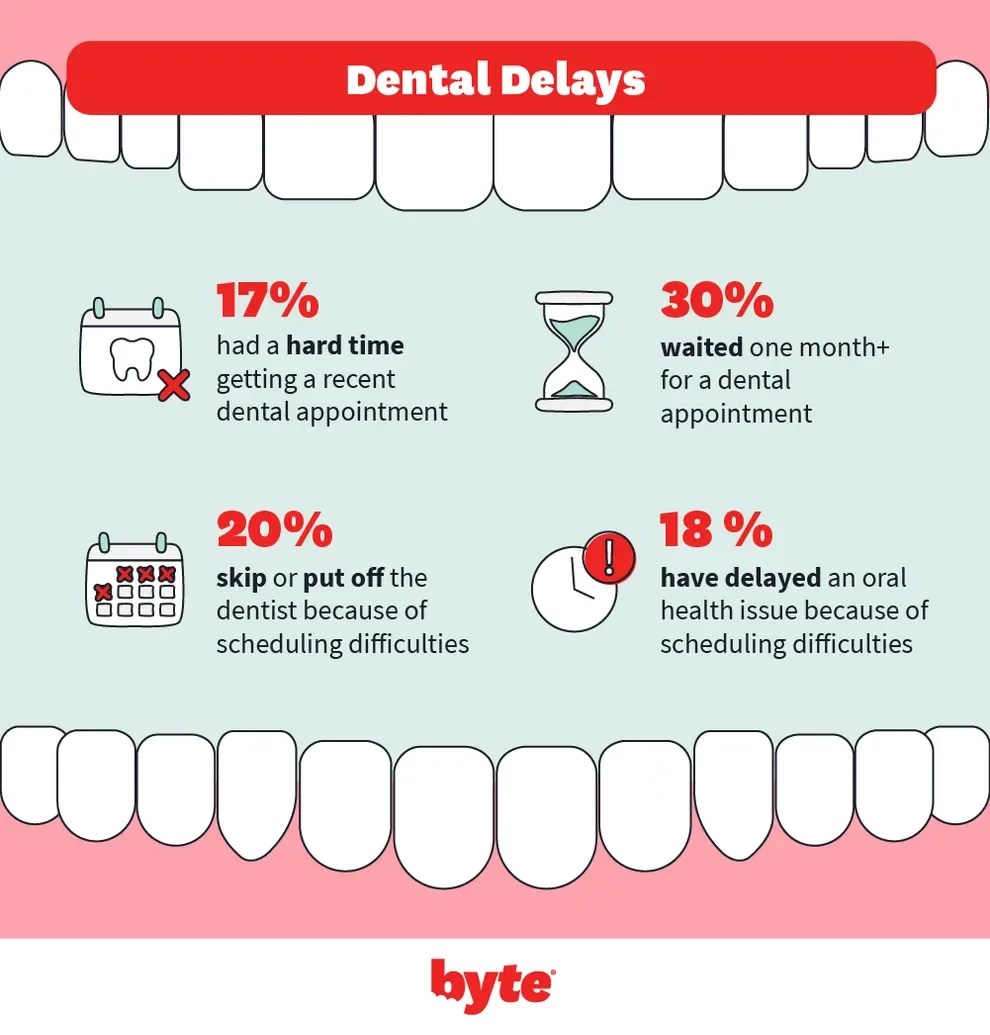
Dental care in America divides people into two camps: those who can afford regular preventive care and cleanings, and those who can’t.
These so-called dental deserts contribute to a deep disparity in overall health. People who live in these places are more likely to get tooth decay and develop severe health problems. They also spend more money on care, and more time seeking health assistance in an emergency.
***
***
Stat: 25 million. That’s how many US residents live in areas without enough dentists, according to a recent Harvard University study.
A growing movement against fluoride is adding to the risk of tooth decay in these “dental deserts.” (NPR)
Both median and average family net worth surged between 2019 and 2022, according to the U.S. Federal Reserve. Average net worth increased by 23% to $1,063,700, the Fed reported in October 2023, the most recent year it published the data. Median net worth, on the other hand, rose 37% over that same period to $192,900.
You might wonder why the average and median net worth figures are so different. That’s because when you take the average of something, you add together every value in a data set and then divide that figure by the number of individual values.
When calculating a median, you simply look at the middle figure within a data set. That said, an average figure can be significantly higher or lower than a median figure if there are extreme outliers – meaning a group of people with significantly more net worth than the rest of the group can bring the average higher.
Average Net Worth by Age
The average net worth of someone younger than 35 years old is $183,500, as of 2022. From there, average net worth steadily rises within each age bracket. Between 35 to 44, the average net worth is $549,600, while between 45 and 54, that number increases to $975,800. Average net worth surges above the $1 million mark between 55 to 64, reaching $1,566,900.
Average net worth again rises for those ages 65 to 74, to $1,794,600, before falling to $1,624,100 for the 75 and older group. The median net worth within every single age bracket, however, is much lower than the average net worth.
***
***
Physicians [MD/DO]Net Worth by Specialty
A 2023 Medscape report shows the top 10 specialties with the most survey respondents saying they are worth more than $5 million.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit a RFP for speaking engagements: CONTACT: MarcinkoAdvisors@outlook.com
Posted on March 28, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
Health and Human Services Secretary Robert F. Kennedy Jr. is expected to announce 10,000 employees will be cut, the Wall Street Journal reported today—the latest round of layoffs in the Trump administration’s push to slash the size of the federal workforce.
US stocks slid lower on Thursday after President Trump pushed ahead with hefty new tariffs on auto imports, stoking concerns about a potential full-on trade war and global economic harm. The S&P 500 (^GSPC) and the Dow Jones Industrial Average (^DJI) fell just over 0.3% on the heels of a losing day for the major gauges. The tech-heavy NASDAQ Composite (^IXIC) led the losses, falling more than 0.5%.
An important concept for all medical professionals to understand is the current rate of return (CCR).
According to this principle, the current rate of a taxable return must be evaluated in reference to a similar non-taxable rate of return. This allows you to focus on your portfolio’s real (after-tax return), rather than its’ nominal, or stated return.
Now, since most medical professionals own a combination of both vehicles, it is important to calculate the average rate of return (ARR), as demonstrated in the following matrix. Usually, this will result in the assumption of more risk, for the possibility of great return.
To compare after tax yields, with taxable yields, use the following formulas:
Tax equivalent yield = yield / (1 – MTB), while taxable yield X (1-tax rate) = tax exempt yield.
Example: if the yield on a tax exempt municipal bond was 6%, and you are in a 28% tax bracket; the equivalent taxable yield (ETY), is 8.3%, calculated in the following manner: 06 / 1.00 – .28 =.083, or, 8.3% ETY. This means that you would need a taxable instrument paying almost 9 % to equal the 6 percent tax exempt bond.
Posted on March 27, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
DEFINITION
By Staff Reporters
***
***
Restaurant Reservation Scalping
The unauthorized online restaurant reservation market works like this.
Third-party platforms directly secure or encourage scalpers to secure reservations at popular restaurants without the restaurants’ permission, and then they facilitate the sale of those reservations for a hefty fee on their websites and smart phone apps.
These reservation scalpers often use bots to quickly secure the reservations online and take them off the market, so the average human customer can’t get access to that reservation without paying an unauthorized third party.
Posted on March 27, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
BREAKING NEWS
By Staff Reporters
***
***I
Intel (NASDAQ: INTC) just said today, that three members of its board of directors would be stepping down as the embattled chip maker reshapes itself under new Chief Executive Lip Bu-Tan.
Omar Ishrak, the former CEO of medical device maker Medtronic (MDT), University of California, Berkeley Dean Tsu-Jae King Liu and University of Pennsylvania professor Risa Lavizzo-Mourey are leaving Intel’s board, the company said in a filing.
For years, I thought of cryptocurrency as a digital replacement for traditional money. After all, Bitcoin has “coin” right in the name. But let’s be honest: if Bitcoin is a currency, then my mother’s old Beanie Baby collection is a retirement fund.
A real currency needs to be stable. It should allow you to buy a coffee today without wondering whether, by tomorrow, that same amount could buy a car—or be worth nothing at all. Bitcoin and its kin like Ethereum and Dogecoin fail this test spectacularly.
Recently I have realized that cryptocurrency might be something even bigger and stranger than currency. It is not just digital money; it’s a bet on the huge global demand for financial autonomy.
In an age where every dollar is tracked, crypto offers an escape from traditional financial oversight. That makes it attractive not just to cybercriminals and tax evaders, but also to privacy advocates, speculators, and people living under restrictive financial policies. It doesn’t replace traditional money, it sidesteps it. It allows people to move, store, create, and destroy wealth outside of conventional banking systems. Some use it for transactions. Others see it as a hedge against inflation or a bet on the future of decentralized finance. Governments and banks don’t quite know what to do with it.
Crypto exists in a financial gray zone. It’s not widely accepted for everyday purchases, yet it can hold immense value. Unlike cash, which is limited by geography, or gold, which requires secure storage, crypto can be transferred globally in seconds. That’s part of its appeal, especially in countries with strict capital controls or volatile economies.
At the heart of cryptocurrency’s identity is the way it is produced. Crypto isn’t just a speculative asset—it’s an industrialized wealth-creation system. Imagine a massive warehouse filled with powerful computers “manufacturing” cryptocurrency. These mining operations exist solely to create new “coins” and process transactions, consuming enormous amounts of electricity in the process. The larger the operation, the more crypto it produces.
This is not how traditional currencies work. Fiat currencies are managed by central banks aiming for economic stability. Crypto, by contrast, is controlled by a decentralized network of miners and participants [block-chain]. Its supply is fixed, immune to government intervention. Some see this as a weakness. Others argue it is crypto’s greatest strength.
As Bitcoin and other major cryptocurrencies become more integrated into mainstream finance, the risks evolve. Even as regulators warn about crypto’s role in illicit activity, major corporations and investment firms are offering crypto-backed products. Some politicians, including President Trump, are discussing national Bitcoin reserves. This growing legitimacy makes crypto harder to ignore. But if crypto-backed funds become widespread, a crash could ripple far beyond crypto traders. That said, crypto remains a small fraction of global finance. Unless institutional adoption grows significantly, even a major downturn likely wouldn’t trigger systemic collapse.
Crypto’s increasing presence in finance does not make it a sound retirement investment. It is still a speculation. And speculations—whether in Bitcoin, meme stocks, or dot-com startups—are high-risk and not suitable for long-term financial security. Retirement portfolios should be built on diversification, stability, and predictable returns. Crypto offers none of these.
For years, I saw crypto as a failed currency. What I now think it to be is a decentralized speculative asset, driven by a growing demand to bypass traditional financial systems. Its future remains uncertain. As regulation increases and mainstream adoption expands, its role will continue to shift. But crypto is no longer just a niche experiment. It has become a financial force that governments, institutions, and individuals must reckon with—whether they embrace it or try to control it.
Posted on March 27, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
Over the next decade, advances in artificial intelligence will mean that humans will no longer be needed “for most things” in the world, says Bill Gates. That’s what the Microsoft co-founder and billionaire philanthropist told comedian Jimmy Fallon during an interview on NBC’s “The Tonight Show” in February. At the moment, expertise remains “rare,” Gates explained, pointing to human specialists we still rely on in many fields, including “a great doctor” or “a great teacher.”
US stocks closed sharply loser Wednesday as President Trump prepared to unveil new tariffs on US auto imports. The benchmark S&P 500 (^GSPC) was down more than 1.1%, while the Dow Jones Industrial Average (^DJI) fell about 0.4%. The tech-heavy NASDAQ Composite (^IXIC) led the losses, sliding over 2%. Tech leaders Nvidia (NVDA) and Tesla (TSLA) both closed down more than 5%.
It’s a shocking fall for 23andMe that once boasted a $6 billion valuation in 2021—despite never making a profit. As of Friday, it was worth $50 million, and on Monday, shares for the consumer genetic testing pioneer fell 50% to 88 cents, Reuters reported.
Visualize: How private equity tangled banks in a web of debt, from the Financial Times.
*** Several years ago we noted that far too many mid-career, mature and physician clients using traditional stock brokers, management consultants and “financial advisors”, seemed to be less successful than those who went it alone. These Do-it-Yourselfers [DIYs] had setbacks and made mistakes, for sure. But, the ME Inc,. doctors seemed to learn from their mistakes and did not incur the high management and service fees demanded from general or retail one-size-fits-all “advisors.”
In fact, an informal inverse related relationship was noted, and dubbed the “Doctor Effect.” In other words, the more consultants an individual doctor retained; the less well they did in all disciplines of the financial planning, professional portfolio and investing continuum.
Of course, the reason for this discrepancy eluded many of them as Wall Street brokerages and wire-houses flooded the media with messages, infomercials, print, radio, TV, texts, tweets, and internet ads to the contrary. Rather than self-learn the basics, the prevailing sentiment seemed to purse the holy grail of finding the “perfect financial advisor.” This realization was a confirmation of the industry culture which seemed to be: Bread for the advisor – Crumbs for the client!
And so, we at the the Institute of Medical Business Advisors Inc. (iMBA), and this Medical Executive-Post, formed a cadre’ of technology focused and highly educated doctors, financial advisors, attorneys, accountants, psychologists and educational visionaries who decided there must be a better way for their healthcare colleagues to receive financial planning advice, products and related management services within a culture of fiduciary responsibility.
We trust you agree with this ME Inc philosophy as illustrated in this free white paper available upon request.
PROFESSIONAL PORTFOLIO CONSTRUCTION [Investing Assets and their Management] Subscribe, Read, Like and Refer
Email whiote paper request here:MarcinkoAdvisors@outlook.com
Without proper internal accounting controls, a medical practice [MD, DO, DPM, DDS, DMD] might never reach peak profitability. Internal controls designed and implemented by the physician-owner help prevent bad things from happening.
Embezzlement protection is the classic example. However, internal controls also help ensure good things happen most of the time; according to colleague Dr. Gary Bode; MSA, CPA.
Some Common Embezzlement “Old School” Schemes
Here are some ‘old-school” embezzlement schemes to avoid; however the list is imaginative and endless.
The physician-owner pocketing cash “off the books”. To the IRS, this is like embezzlement to intentionally defraud it out of tax money.
Employee’s pocketing cash from cash transactions. This is why you see cashiers following protocol that seems to take forever when you’re in the grocery check out line. This is also why you see signs offering a reward if he/she is not offered a receipt. This is partly why security cameras are installed.
Bookkeepers writing checks to themselves. This is easiest to do in flexible software programs like QuickBooks, Peachtree Accounting and related financial software. It is one of the hardest schemes to detect. The bookkeeper self-writes and cashes the check to their own name; and then the name on the check is changed in the software program to a vendor’s name. So a real check exists which looks legitimate on checking statements unless a picture of it is available.
Employees ordering personal items on practice credit cards.
Bookkeepers receiving patient checks and illegally depositing them in an unauthorized, pseudo practice checking account, set up by themselves in a bank different from yours. They then withdraw funds at will. If this scheme uses only a few patients, who are billed outside of the practice’s accounting software it is hard to detect. The doctor must have a good knowledge of existing patients to catch the ones “missing” from practice records. Monitoring the bookkeeper’s lifestyle might raise suspicion, but this scheme is generally low profile and protracted. Checking the accounting software “audit trail” shows the required original invoice deletions or credit memos in a less sophisticated version of this scheme.
Bookkeepers writing payroll checks to non-existent employees. This scheme works well in larger practices and medical clinics with high seasonal turnover of employees, and practices with multiple locations the podiatrist-owner doesn’t visit often.
Bookkeepers writing inflated checks to existing employees, vendors or subcontractors. Physician-owners should beware if romantic relationships between the bookkeeper and other practice related parties.
Bookkeepers writing checks to false vendors. This is another low profile, protracted scheme that exploits the podiatrists-owner’s indifference to accounts payable.
Assessment
Operating efficiency, safeguarding assets, compliance with existing laws and accuracy of financial transactions are common goals of internal managerial and cost accounting in medical practice.
CONCLUSION
Hopefully, the above is a good review to prevent common practice embezzlement schemes. Unfortunately, it is a never-ending endeavor.
References: Marcinko, DE: Dictionary of Health Economics and Finance. Springer Publishing Company, NY 2007.
Posted on March 26, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
Donald Trump has officially dropped a stablecoin. It’s called USD1, and it’s pegged 1:1 with the US dollar, according to a statement from his family company World Liberty Financial Inc, (WLFI) today. The company says the token is fully backed by short-term US government treasuries, USD deposits, and other cash equivalents. Every token equals one dollar, no exceptions. WLFI says it built the whole thing to give people a stablecoin they don’t have to second guess.
US stocks rose for a third day in a row despite souring consumer confidence — and as investors weighed whether President Trump would temper his plans for upcoming tariffs.
The benchmark S&P 500 (^GSPC) rose more than 0.1%, while the Dow Jones Industrial Average (^DJI) ticked just above the flatline. The tech-heavy NASDAQ Composite (^IXIC) rose nearly 0.5%, bolstered by a more than 3% jump from Tesla (TSLA).
During his first month in office, President Donald Trump’s administration has rolled out edicts calling for significant changes at a fast and furious pace, with a number of healthcare agencies and programs across the U.S. Department of Health & Human Services (HHS) targeted.
In an attempt to keep up with the latest actions of the legislative and executive branches of the federal government, this Health Capital Topics article summarizes recent events in Washington and the impact of these changes (both imminent and impending) on providers and patients. (Read more…)
Posted on March 25, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
By Wikipedia and Staff Reporters
***
***
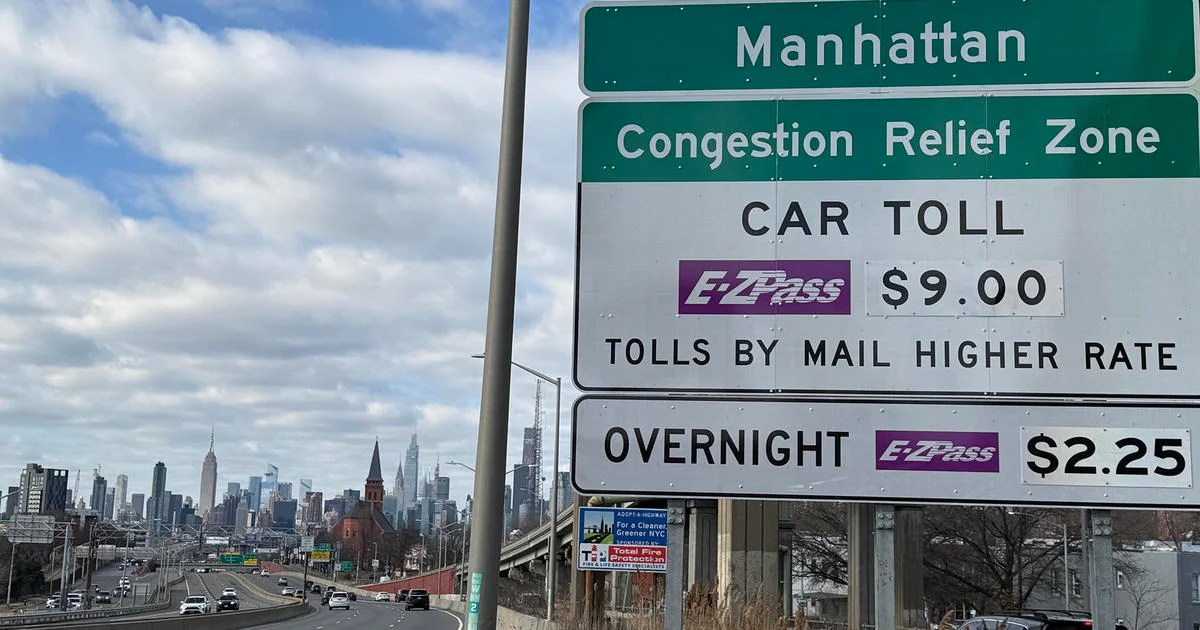
Congestion pricing or congestion charges is a system of surcharging users of public goods that are subject to congestion through excess demand, such as through higher peak charges for use of bus services, electricity, railways, telephones, and road pricing to reduce traffic congestion; airlines and shipping companies may be charged higher fees for slots at airports and through canals at busy times. This pricing strategy regulates demand, making it possible to manage congestion without increasing supply.
According to the economic theory behind congestion pricing, the objective of this policy is to use the price mechanism to cover the social cost of an activity where users otherwise do not pay for the negative externalities they create (such as driving in a congested area during peak demand).
By setting a price on an over-consumed product, congestion pricing encourages the redistribution of the demand in space or in time, leading to more efficient outcomes.
Posted on March 25, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
US stocks closed near session highs on Monday as investors welcomed reports that the next wave of President Trump’s tariffs will be narrower than expected.
The S&P 500 (^GSPC) rose almost 1.8% on the heels of the broad benchmark snapping a four-week losing streak. The Dow Jones Industrial Average (^DJI) advanced 1.4%, while contracts on the tech-heavy NASDAQ Composite (^IXIC) led the gains, up 2.3%.
A hostile takeover happens when an entity takes control of a company without the knowledge and against the wishes of the company’s management. A hostile takeover is an acquisition strategy requiring that the entity acquire and control more than 50% of the voting shares issued by the company.
In mergers and acquisitions (M&A), a hostile takeover is the acquisition of a target company by an acquiring company that goes directly to the target company’s shareholders, either by making a tender offer or through a proxy vote.
Ideally, an entity interested in acquiring a company should seek approval from the target company’s Board of Directors. The difference between a hostile and a friendly takeover is that, in a friendly takeover, the target company’s board of directors approve of the transaction and recommend shareholders vote in favor of the deal.
Defenses against a hostile takeover
These defense mechanisms can be preemptive or reactive, depending on how prepared the company is for the possibility of a hostile bid.
Poison pill is one of the most common defenses against a hostile takeover. Officially known as a “shareholder rights plan,” the poison pill allows existing shareholders to purchase additional shares at a discount, diluting the ownership interest of the acquiring company. The goal is to make it prohibitively expensive for the acquirer to complete the takeover.
A golden parachute is another defense strategy, which involves providing lucrative compensation packages (bonuses, severance pay, stock options, etc.) to key executives in the event they are terminated as a result of the takeover. This creates a financial disincentive for the acquiring company, as it would need to pay out these large sums upon completing the takeover.
In a Crown jewel defense, the target company sells or threatens to sell its most valuable assets—its “crown jewels”—if the takeover is completed. This reduces the attractiveness of the company to the acquirer, as the most desirable assets would no longer be part of the deal.
The Pac-Man defenses a more aggressive strategy in which the target company turns the tables by attempting to buy shares of the acquiring company, effectively launching a counter-takeover. While rare, this defense can deter hostile bids by making the takeover battle more costly and complex.
A White-Knight defense involves the target company seeking out a more favorable acquirer, or “white knight,” to make a friendly takeover bid. This allows the target company to avoid the hostile acquirer while still securing the benefits of a merger or acquisition.
The hostile takeover between Sanofi-Aventis and Genzyme Corp. occurred in 2010 when Sanofi, a French pharmaceutical company, wanted to buy Genzyme, a US biotech firm specializing in rare diseases. Genzyme resisted the offer, leading to conflict. Sanofi started a public campaign to pressure Genzyme’s shareholders into selling.
After months of negotiations, the two companies reached a deal in 2011. Sanofi agreed to pay $74 per share, with additional payments tied to Genzyme’s future performance, bringing the total deal value to around $20.1 billion. This acquisition allowed Sanofi to expand into the lucrative market for rare disease treatment.
The genetic testing company 23andMe went from biotech superstar to the brink of collapse. And, its most valuable asset might be its controversial customer DNA data trove.
Now, 23andMe filed for bankruptcy late Sunday night and announced the resignation of its chief executive officer Anne Wojcicki who is stepping down from her position but remains on the board of directors.
Wojcicki has so far tried unsuccessfully to rescue the business by buying it back and capping a precipitous fall for the DNA-testing company.
Posted on March 24, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
Futures attached to the benchmark S&P 500 (ES=F) rose 0.6%, with NASDAQ 100 (NQ=F) futures up 0.7%. Futures tied to the Dow Jones Industrial Average (YM=F) advanced around 0.4%.
Posted on March 23, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
ByJ. Chris Miller JD
***
***
Your personal and financial life is constantly changing. Significant changes always necessitate the need to review your life. However, a few key events trigger the need to review your estate plan. If any of the events below have occurred since you reviewed your estate plan, see a competent adviser to help you achieve your goals.
Birth of a child or grandchild.
Death of a spouse, beneficiary, guardian, trustee or personal representative.
Marriage of you or your children.
Divorce. (Review beneficiary designations and asset titling)
Move out of state. An estate is settled under the laws of the state in which the decedent resided. Certain provisions of a will that are valid in one state may not be in another.
Change in estate value. A large increase or decrease in the size of an estate may greatly affect some of the strategies that were implemented.
Changes in business. Starting, buying or selling a medical practice or other business has an impact on your estate. The addition or death of a business owner will cause a review.
Tax law changes. EGTRRA has dramatically changed the way we plan for estate taxes. It is important to note that only planning for estate taxes has been effected. Estate planning involves much more than just the motivation to reduce or eliminate taxes. Assuring that your family is financially taken care of, that children have the opportunity to go to college, that your debts are paid, that charitable desires are achieved, provisions for a needy child, proper selection of a guardian, the list goes on. Please do not use the new law as an excuse to not plan your estate.
***
OVERHEARD IN THE FINANCIAL ADVISOR’S LOUNGE
From my perspective, estate planning is a team sport, and lawyers rely on financial advisers all the time to spot issues for clients. We do not share the opinion that non-lawyers are incapable of giving good advice.
The recent horrifying murder of UnitedHealthcare Group CEO Brian Thompson has called attention to the anger many Americans feel about our health care system. This tragedy has thrust the very real issue of health care costs back into the headlines.
One article on the topic, from Ken Alltucker for USA Today, offered seven reasons why Americans pay so much for health care with such poor results. When I saw the headline, I thought, “Finally, someone’s going to bring up the elephant in the room: taxes.”
The seven reasons included bloated administrative costs, lack of price transparency, overpaid specialists, higher prescription drug prices, and more. But I didn’t see a word about how, compared to other developed nations with “cheaper” health care, Americans pay far lower taxes. That omission feels like leaving a critical piece of the puzzle off the table.
***
***
In reality, countries with universal health care are not pulling off some magic trick of efficiency. They are simply collecting the money differently—through significantly higher taxes. Americans, on the other hand, pay for health care more directly, through out-of-pocket costs and insurance premiums.
In a column last year, I did the math. Americans spend about 17.8% of GDP on health care, plus 27.7% of GDP in taxes. That’s a total of 45.5%. Now compare that to twelve European countries with universal health care. They spend a median of 11.5% of GDP on health care and collect 41.9% of GDP in taxes. Total? 53.4%. In other words, Americans are spending 7.9% less overall on healthcare and taxes combined.
The saving isn’t what it appears, though. A fair comparison of healthcare costs and taxes needs to account for the fact that universal healthcare systems cover 100% of their populations, while the U.S. system currently leaves about 8% uninsured. If you factor in the cost of covering our uninsured residents, the U.S. likely spends a comparable percentage of income on healthcare as European countries with universal systems.
***
***
Our system is far from perfect. As the USA Todayarticle points out, administrative costs are bloated. Harvard’s David Cutler estimates up to 25% of our health spending goes toward paperwork, phone calls, and processing. Price transparency is practically nonexistent. The cost of a diagnostic test might vary from $300 to $3,000 depending on where you go. We pay much more for prescription drugs and many procedures than those same treatments cost in other developed nations. Another issue is the fee-for-service model that rewards doctors for ordering more tests and procedures, whether or not patients get better.
We can do better. Innovations like value-based care, where providers are paid for outcomes rather than procedures, could help shift the system toward real results. Greater price transparency would empower patients to make informed choices and force providers to compete. And addressing administrative inefficiencies could save billions.
Yet fixing the system requires being honest about trade-offs. If we want universal health care at European price rates, we need to accept European tax rates. That’s the part of the conversation that often gets left out. It’s easy to be angry at hospitals, insurance companies, and drug manufacturers—and yes, they all have plenty to answer for. But we also need to face the reality that we’ve chosen a system that prioritizes lower taxes over centralized health care.
Anger may have put the flaws in our health care system in the spotlight. Finding genuine solutions will require moving beyond expressions of anger and frustration. It will demand thoughtful discussions about what kind of health care system, as individuals and as a nation, that we want and how we are willing to fund it.
Posted on March 22, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
While some medical practitioners and facilities can operate without Professional Liability Insurance coverage, one business related insurance that cannot / should not be avoided is Worker’s Compensation. Employers in all but seven states – so-called “monopolistic” states because they have their own state funds, are under statutory obligation to provide coverage for their employees. Historically, Worker’s Compensation pre-dates Social Security entitlements and well before the emergence of employer sponsored group benefits.
The coverage under worker’s compensation provides for lost income due to on-the-job accidents or work-related disability or death and the amount of benefits vary by state. In some instances, the coverage will reimburse the employee for medical expenses incurred with the accident.
The four general benefits covered under Worker’s Compensation are:
Medical Care – for expenses incurred usually without limitations on amount or period of care.
Disability Income – payable for both total and partial disability and is usually based on 66 2/3 percent of their wage base.
Death Benefits – generally fall into two categories; one a flat amount for “burial” insurance; and two, survivor benefits. Though varying by state, these benefits are similar to the disability payment (a percentage of weekly base wages) but may be capped as to total benefit, such as $50,000 or a period, such as 10 years
Rehabilitation Benefits – includes not only medical rehabilitation, but vocational rehabilitation, vocational counseling, retraining or educational benefits, and job placement
Traditionally, the secondary purpose of Worker’s Compensation was to reduce potential litigation because employees accepting the benefits from a Worker’s Compensation claim generally waived their right to sue their employer.
***
***
However, in our litigious society, this “protective shelter” has been severely tested and is crumbling.
Employers may provide their Worker’s Compensation three ways:
Private commercial insurance
State government funds
Self-insurance
Very few factors drive the premium structure – the occupation of the workers is the single most important determinant of premiums. An office worker may have premiums as low as $.10 per hundred of wages and a coal miner may exceed $50.00 per hundred of wages. Generally speaking, however, Worker’s Compensation premiums for the medical profession or healthcare worker are among the lowest available.
Therefore, for the medical practice, some physicians may consider self-insurance because the weekly benefits are typically below $500, thus making this decision attractive.
Alternatively, because officers and owners can elect not to be covered by Worker’s Compensation, the decision to purchase coverage from a private insurance company may afford inexpensive assurance that the benefits will be conveniently provided, and administered, by a private insurance company for their employees.
Absolute Return – the goal is to have a positive return, regardless of market direction. An absolute return strategy is not managed relative to a market index.
Accredited Investor – wealthy individual or well-capitalized institutions covered under Regulation D of the Securities Act of 1933.
Alpha – the return to a portfolio over and above that of an appropriate benchmark portfolio (the manager’s “value added”).
Arbitrage – any strategy that invests long in an asset, and short in a related asset, hoping the prices will converge.
Attribution – the process of “attributing” returns to their sources. For example, did the returns to a portfolio (over and above some benchmark) come from stock selection, industry/sector over- or under-weighting or factor weighting. Software programs are helpful in reporting an attribution.
Beta – a measure of systematic (i.e., non-diversifiable) risk. The goal is to quantify how much systematic risk is being taken by the fund manager vis-à-vis different risk factors, so that one can estimate the alpha or value-added on a risk-adjusted basis.
Correlation – a measure of how strategy returns move with one another, in a range of –1 to +1. A correlation of –1 implies that the strategies move in opposite directions. In constructing a portfolio of hedge funds, one usually wants to combine a number of non-correlated strategies (with decent expected returns) to be well diversified.
Drawdown – the percentage loss from a fund’s highest value to its lowest, over a particular time frame. A fund’s “maximum drawdown” is often looked at as a measure of potential risk.
Hurdle Rate – the return where the manager begins to earn incentive fees. If the hurdle rate is 5% and the fund earns 15% for the year, then incentive fees are applied to the 10% difference.
Leverage – one uses leverage if he borrows money to increase his position in a security. If one uses leverage and makes good investment decisions, leverage can magnify the gain. However, it can also magnify a loss.
Opportunistic – a general term that describes an aggressive strategy with a goal of making money (as opposed to holding on to the money one already has).
***
***
Pairs Trading – usually refers to a long/short strategy where one stock is bought long, and a similar stock is sold short, often within the same industry. Buying the stock of Home Depot and shorting Lowe’s in an equal amount would be an example.
Portfolio Simulation – involves testing an investment strategy by “simulating” it with a database and analytic software. Often referred to as “backtesting” a strategy. The simulated returns of the strategy are compared to those of a benchmark over a specific time frame to see if it can beat that benchmark.
Sharpe Ratio – a measure of risk-adjusted return, computed by dividing a fund’s return over the risk-free rate by the standard deviation of returns. The idea is to understand how much risk was undertaken to generate the alpha.
Short Rebate – if you borrow stock and then sell it short, you have cash in your account. The short rebate is the interest earned on that cash.
R-Squared – a measure of how closely a portfolio’s performance varies with the performance of a benchmark, and thus a measure of what portion of its performance can be explained by the performance of the overall market or index. Hedge fund investors want to know how much performance can be explained by market exposure versus manager skill.
Transportable Alpha – the alpha of one active strategy can be combined with another asset class. For example, an equity market-neutral strategy’s value-added can be “transported” to a fixed income asset class by simply buying a fixed income futures contract. The total return comes from both sources.
Value at Risk – a technique which uses the statistical analysis of historical market trends and volatilities to estimate the likelihood that a specific portfolio’s losses will exceed a certain amount.
Posted on March 22, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
A CONTROVERSY?
By Staff Reporters
***
***
DEFINITION
State medical boards are the agencies that license medical doctors, investigate complaints, discipline physicians who violate the medical practice act, and refer physicians for evaluation and rehabilitation when appropriate. The overriding mission of medical boards is to serve the public by protecting it from incompetent, unprofessional, and improperly trained physicians. Medical boards accomplish this by striving to ensure that only qualified physicians are licensed to practice medicine and that those physicians provide their patients with a high standard of care.
The right to practice medicine is a privilege granted by the state. Each state has laws and regulations that govern the practice of medicine and specify the responsibilities of the medical board in regulating that practice. These regulations are laid out in a state statute, usually called a medical practice act. State medical boards establish the standards for the profession through their interpretation and enforcement of this act.
Assembling a quality physician population to meet the needs of the public begins with licensure. During the process of evaluating applicants for medical licensure, state medical boards’ primary focus is on a physician’s qualifications, including undergraduate and graduate medical education, work history, and personal character.
Candidates for licensure also must successfully complete a rigorous examination designed to assess their ability to apply knowledge, concepts, and principles of health and disease that constitute the basis for safe and effective patient care.
The Federation of State Medical Boards of the United States, Inc., and the National Board of Medical Examiners (NBME) have collaborated to establish a single, 3-step examination for medical licensure in the United States, known as the United States Medical Licensing Examination (USMLE). The USMLE provides state medical boards with a common evaluation system for all licensure applicants. To assure the continued relevance of the exam, the NBME uses basic science and clinical faculty from the nation’s medical schools as well as practicing physicians, some of whom serve on state medical boards, to generate the examinations.
“… I am persuaded that licensure has reduced both the quantity and quality of medical practice…It has reduced the opportunities for people to become physicians, it has forced the public to pay more for less satisfactory service, and it has retarded technological development…I conclude that licensure should be eliminated as a requirement for the practice of medicine”
-Milton Friedman, Nobel prize-winning economist
“As a rule, regulation is acquired by the industry and is designed and operated primarily for its benefit”
-George J. Stigler Nobel Prize-winning economist
“Licensing has served to channel the development of health care services by granting an exclusive privilege and high status to practitioners relying on a particular approach to health care, a disease-oriented intrusive approach rather than a preventive approach….By granting a monopoly to a particular approach to health care, the licensing laws may serve to assure an ineffective health care system”
-Lori B. Andrews, Professor of Law, Chicago-Kent College
“Let us allow physicians, hospitals and schools to spring up where they’re needed, abolish the restrictive licensure laws, and simply invoke the laws against fraud to insure honesty among all providers of health care …That will make health care affordable for everyone”
Posted on March 22, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
The S&P 500 edged up 0.1%. The index finished with a 0.5% gain for the week. It’s still down 4.8% so far this month. The Dow Jones Industrial Average eked out a 0.1% gain, while the NASDAQ composite rose 0.5%.
It appears Medicare coverage for tele-health is here to stay—at least for the next six months. When the House of Representatives and Senate passed a budget on March 11t and 14th, respectively, they not only avoided a government shutdown, but also extended a resolution for Medicare to cover non-behavioral health tele-health appointments until September 30th.
Visualize: How private equity tangled banks in a web of debt, from the Financial Times.
Posted on March 21, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
Beware – Public Improvement Fees
Beware – Public Improvement Districts
By Staff Reporters
***
***
A Public Improvement Fee (PIF) is a fee that developers may require their tenants to collect on sales transactions to pay for on-site improvements. The PIF is a fee and NOT a tax; therefore, it becomes a part of the overall cost of the sale/service and is subject to sales tax
Examples of these improvements include curbs and sidewalks, parking facilities, storm management system, sanitary sewer systems, road development (within the site) and outdoor public plazas.
Public Improvement Districts (PIDs) are a financing mechanism used to fund new developments and infrastructure improvements. PIDs are relatively easy to create and can be done by the local municipality. A majority of property owners within the district may petition a local government to create the district. Bonds can then be issued to fund a development or infrastructure improvements. Through an industry analysis and view of the current political environment, PIDs are certainly a beneficial mechanism to fund projects otherwise not feasible due to constraints on city budgets. Local elected officials will want PIDs monitored and only used in proper circumstances.
Posted on March 21, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
U.S. stock indexes edged lower Thursday following another reminder that big, unsettling policy changes are underway because of President Donald Trump, along with more signals suggesting the U.S. economy remains solid for now.
The S&P 500 slipped 0.2% after flipping between modest gains and losses through the day. The Dow Jones Industrial Average dipped by 11 points, or less than 0.1 %, and the NASDAQ composite fell 0.3%.
Posted on March 21, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
By Health Capital Consultants, LLC
***
***
The term “value” has many different meanings and definitions to different parties. Therefore, at the outset of each valuation engagement, it is critical to define appropriately (and have all parties agree to) the standard of value to be employed in developing the valuation opinion.
The standard of value defines the type of value to be determined and answers the question “value to whom?” There are several standards of value that may be sought, including: Fair Market Value (FMV), Fair Value, Investment Value, and Liquidation Value. (Read more...)
Posted on March 20, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
A medical zebra is rare a disease, one that is so rare that most doctors have not encountered a patient with that disease. Having only read about the disease in a textbook or in the case of many recently defined diseases, not at all. It is therefore difficult for medical doctors to diagnose these individuals.
The term originates from a popular saying among clinicians, “when you hear hoof-beats, think horses, not zebras”, meaning that when diagnosing a patient, one should first exclude the most common causes for a patients symptoms, before looking for rare causes. While this is a good idea in everyday practice, one must not forget to make the effort to go “zebra hunting” when the common causes don’t explain the full clinical picture. This is especially important with the current growth of genetics and personalized medicine.
Examples:
Sutton’s law – perform first the diagnostic test expected to be most useful
Occam’s razor – select from among competing hypotheses the one that makes the fewest new assumptions
Leonard’s law of physical findings – it is obvious or it is not there
Hickam’s dictum – “Patients can have as many diseases as they damn well please”
Samuel Gee – author of Medical lectures and aphorisms (1902)
James Alexander Lindsay – author of Medical axioms, aphorisms, and clinical memoranda (1924)
Maimonides – Commentary on the aphorisms of Hippocrates and Medical aphorisms of Moses (12th century)
Sagan standard – Extraordinary claims require extraordinary evidence
Twyman’s law – Any figure that looks interesting, or different, is usually wrong.
Now, a medical aphorisms is a pithy statement denoting a general truth. They have a special niche in medical discourse and writing. The use of aphorisms in medicine dates to ancient times and continues today.
Tax avoidance—An action taken to lessen tax liability and maximize after-tax income.
Tax evasion—The failure to pay or a deliberate underpayment of taxes.
Underground economy—Money-making activities that people don’t report to the government, including both illegal and legal activities.
Voluntary compliance—A system of compliance that relies on individual citizens to report their income freely and voluntarily, calculate their tax liability correctly, and file a tax return on time.
Posted on March 20, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
Stat: $1.2 billion. That’s how much San Diego-based Scripps Health plans to spend building a new hospital in San Marcos, California. (Becker’s Hospital Review)
Read: What WHO Director-General Tedros Adhanom Ghebreyesus said about USAID cuts. (Stat)
Pharm fresh: Check out in-depth strategies designed to help increase engagement between pharma reps and primary care clinicians. It’s all right here in Pri-Med’s research. Read the report.
Shares of Charles Schwab Corp. SCHW+1.51% rallied 1.51% to $78.73 Wednesday, on what proved to be an all-around favorable trading session for the stock market, with the S&P 500 IndexSPX+1.08% rising 1.08% to 5,675.29 and the Dow Jones Industrial AverageDJIA+0.92% rising 0.92% to 41,964.63.
Posted on March 19, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
BREAKING NEWS!
***
***
The Federal Reserve just opted to hold interest rates steady as officials reckon with fearful markets and concerns of an economic slowdown sparked by the trade wars launched by President Donald Trump and his efforts to overhaul and dismantle government agencies.
After a two-day meeting of its monetary policy committee in Washington, D.C., the Fed announced it would hold its rate target at a range of 4.25% to 4.50%. Investors anticipated the move. The Fed’s target rate remains a full percentage point lower than it was when the Fed pivoted to cutting rates last September.
Posted on March 19, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
Rocking Financial Planning … Old School Advice!
By Dr. David E. Marcinko MBBS MBA MEd CMP®
The economic platitude of the past, such as don’t spend more than 15-20 percent of your net salary on food, or 5-10 percent on medical care, among others, have given rise to the more individualized personal financial ratio concept. Personal ratios, like business ratios, represent benchmarks to compare such parameters as debt, income growth and net worth.
According to Edward McCarthy MIB CFP® – a personal financial expert from Warwick, Rhode Island whom I interviewed about a decade ago – the following represented useful ratios for the lay as well as medical professional [personal communication].
The Ratios:
Basic Liquidity Ratio = liquid assets / average monthly expenses. Should be 4-6 months, or even longer, in the case of a medical professional employed by a financially insecure HMO. In a low interest rate environment, iMBA Inc offers 12-24 months for consideration.
Debt to Assets Ratio = total debt / total assets. A percentage which is high initially, and should decrease with age as the medical professional approaches a debt free existence
Debt to Gross Income Ratio = annual debt repayments / annual gross income. A percentage representing the adequacy of current income for existing debt repayments. Medial professionals should try to keep this below 25-30%.
Debt Service Ratio = annual debt re-payment / annual take-home pay. Medical professionals should try to keep this ratio below about 40%, or have difficulty paying down debt.
Investment Assets to Net Worth-Ratio = investment assets / net worth. This ratio should increase over time, as retirement for the medical professional approaches.
Savings to Income Ratio = savings / annual income. This ratio should also increase over time, especially as major obligations are retired.
Real Growth Ratio = (income this year – income last year) / (income last year – inflation rate). It is desirable for the medical professional to keep this ratio growing faster than the core rate f inflation.
Growth of Net-Worth Ratio = (net worth this year – net worth last year) / net worth last year – inflation rate. Again, this ratio should stay ahead of inflation.By calculating these ratios, perhaps on an annual basis, the medical professional can spot problems, correct them, and continue progressing toward stated financial goals.
Assessment
Now, after ten years, are these traditional ratios and advice still valid today: why or why not?
***
***
Conclusion
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on March 19, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Split-Dollar Life Insurance: An arrangement under which a life insurance policy’s premium, cash values, and death benefit are split between two parties—usually a corporation and a key employee or executive. Under such an arrangement an employer may own the policy and pay the premiums and give a key employee or executive the right to name the recipient of the death benefit.
***
***
Several factors will affect the cost and availability of life insurance, including age, health, and the type and amount of insurance purchased. Life insurance policies have expenses, including mortality and other charges. If a policy is surrendered prematurely, the policy holder also may pay surrender charges and have income tax implications. You should consider determining whether you are insurable before implementing a strategy involving life insurance.
Any guarantees associated with a policy are dependent on the ability of the issuing insurance company to continue making claim payments.
9. We act with honesty, integrity and are always straightforward. 8. We strive to be innovative, creative, iconoclastic, and flexible. 7. We admit and learn from mistakes and don’t repeat them. 6. We work hard always as competitors are trying to catch up. 5. We treat others with dignity and respect. 4. We are the onus of consulting advice for the well being of others. 3. We fight complacency as former success is in the past. 2. The best management styles are timeless, not timely. 1. Our clients are colleagues and always come first.
SPEAKING: Dr. David Edward Marcinko MBA MEd will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit a RFP for speaking engagements.
***
***
CONTACT: Ann Miller RN MHA at: MarcinkoAdvisors@outlook.com
Posted on March 19, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
US stocks pulled back on Tuesday, led by a nearly 2% decline in the NASDAQ, following two days of gains as investors concerned about an economic slowdown looked to the Federal Reserve’s policy meeting for insights.
The tech-heavy NASDAQ Composite (^IXIC) plummeted about 1.7% as Nvidia (NVDA) shares fell roughly 3% as its annual GTC event failed to impress investors. Other “Magnificent Seven” names also dragged down the tech-heavy index. Notably, those stocks are having their worst quarter in more than two years.
The Dow Jones Industrial Average (^DJI) and S&P 500 (^GSPC) also moved to the downside on Tuesday, dropping about 0.6% and 1.1%, respectively.
“Malta has quietly leveraged the rising tide of the financial transparency imperative to attract hedge funds.“
There was a time when the quaint island sought to play on the traditional terrain, offering anonymity and a “laissez-faire regulatory regime,” not to mention very low taxes, as in no capital gains taxes and no taxes on dividends; all while English speaking and USD currency denominated.
***
***
While many leading domiciles for offshore hedge funds remain in the Caribbean – notably the Cayman Islands, the British Virgin Islands, Bermuda, and the Bahamas – the island of Malta is drawing attention, especially from European funds.
SO – HOW MUCH IS A “FINANCIAL ADVISOR” REALLY WORTH?
This blog holds a rather uncomplimentary opinion of financial advisors, and the financial services and brokerage industry as a whole; deserved, or not? The entire site hints at this attitude as well, in favor of a going it alone or ME, Inc investing when possible. Nevertheless, it is reasonable to wonder how much boost in net-returns might an educated and informed, fee transparent and honest, fiduciary focused “financial advisor” add to a clients’ investment portfolio; all things being equal [ceteris paribus].
And, can it be quantified?
Well, according to Vanguard Brokerage Services®, perhaps as much as 3%? In a decade long paper from the Valley Forge, PA based mutual fund and ETF giant, Vanguard said financial advisors can generate returns through a framework focused on five wealth management principles:
• Being an effective behavioral coach: Helping clients maintain a long-term perspective and a disciplined approach is arguably one of the most important elements of financial advice. (Potential value added: up to 1.50%).
• Applying an asset location strategy: The allocation of assets between taxable and tax-advantaged accounts is one tool an advisor can employ that can add value each year. (Potential value added: from 0% to 0.75%).
• Employing cost-effective investments: This component of every advisor’s tool kit is based on simple math: Gross return less costs equals net return. (Potential value added: up to 0.45%).
• Maintaining the proper allocation through rebalancing: Over time, as investments produce various returns, a portfolio will likely drift from its target allocation. An advisor can add value by ensuring the portfolio’s risk/return characteristics stay consistent with a client’s preferences. (Potential value added: up to 0.35%).
• Implementing a spending strategy: As the retiree population grows, an advisor can help clients make important decisions about how to spend from their portfolios. (Potential value added: up to 0.70%).
Source: Financial Advisor Magazine, page 20, April 2014.
Assessment
However, Vanguard notes that while it’s possible all of these principles could add up to 3% in net returns for clients, it’s more likely to be an intermittent number than an annual one because some of the best opportunities to add value happen during extreme market lows and highs when angst or giddiness [fear and greed] can cause investors to bail on their well-thought-out investment plans.
And, is the study applicable to doctors and allied healthcare providers? Doe Vanguard have a vested interest in the topic. What about fee based versus fee-only financial advice?
Conclusion
Finally, recognize the plethora of other financial planning life-cycle topics addressed in this ME-P were not included in the Vanguard investment portfolio-only study a decade ago.
And what about today with contemporaneous internet advising, chat-rooms, linkedin, robo-advisors, reddit and the like?
Posted on March 18, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST–TODAY’SNEWSLETTERBRIEFING
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
A group of current and former employees of JPMorgan Chase (NYSE:JPM) has filed a lawsuit alleging that the company, through its prescription drug plan run by CVS Health (NYSE:CVS), overpaid for medicines, resulting in higher expenses for its workers, according to Bloomberg News.
The S&P 500 (^GSPC) gained about 0.6% to rebound for a second day in row, while the Dow Jones Industrial Average (^DJI) gained more than 350 points, or more than 0.8%. The tech-heavy NASDAQ Composite (^IXIC) rose 0.3% as “Magnificent 7” stocks, including Nvidia (NVDA) and Tesla (TSLA), faltered.
Posted on March 17, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
BANK IDENTIFICATION NUMBER – DEFINED
By Staff Reporters
***
***
What Is a BIN Attack?
The BIN, or the Bank Identification Number, is the first six digits on a credit card. These are always tied to its issuing institution – usually a bank. In a BIN attack, fraudsters use these six numbers to algorithmically try to generate all the other legitimate numbers, in the hopes of generating a usable card number.
How Does a BIN Attack Work?
Fraudsters conduct BIN attacks by generating hundreds of thousands of possible credit card numbers and testing them out.
A fraudster looks up the BIN of the bank they will target. Ranging from four to six digits, this information is in the public domain and is thus easy to source.
Using dedicated software such as an auto-dialer, they generate thousands, often tens of thousands, combinations of possible existing card numbers by this issuer.
At this point, these credentials need to be tested. The fraudster identifies a suitable online shop or donation page.
They start card testing by attempting a small payment with each generated card number.
They keep track of the small percentage of card details that worked, which they are ready to use in earnest for their fraudulent pursuits.
***
***
Remember that the fraudster will start off with only six digits, yet there are many more card details required for a successful transaction. If those are entered erroneously, the transaction will decline. This includes the CVV number, the expiration date, as well as likely address verification service (AVS) failures. Card testing transactions are executed remotely in a fast fashion, so distance checks should also be a hint as well as velocity alerts.
Fraudsters may use bad merchant accounts directly for this purpose, or more frequently involve multiple online stores and services during a BIN attack, as their attempts keep getting blocked at most outlets.
When analyzing a set of financial statements to determine practice value, adjustments (normalizations) generally are needed to produce a clearer picture of likely future income and distributable cash flow. It also allows more of an “apples to apples” line item comparison. This normalization process usually consists of making three main adjustments to a medical practice’s net income (profit and loss) statement.
1. Non-Recurring Items: Estimates of future distributable cash flow should exclude non-recurring items. Proceeds from the settlement of litigation, one-time gains/losses from the selling of assets or equipment, and large write-offs that are not expected to reoccur, each represent potential nonrecurring items. The impact of nonrecurring events should be removed from the practice’s financial statements to produce a clearer picture of likely future income and cash flow.
2. Perquisites: The buyer of a medical practice may plan to spend more or less than the current doctor-owner for physician executive compensation, travel and entertainment expenses, and other perquisites of current management. When determining future distributable cash flow, income adjustments to the current level of expenditures should be made for these items.
3. Non-cash Expenses: Depreciation expense, amortization expense, and bad debt expense are all non-cash items which impact reported profitability. When determining distributable cash flow, you must analyze the link between non-cash expenses and expected cash expenditures.
The annual depreciation expense is a proxy for likely capital expenditures over time. When capital expenditures and depreciation are not similar over time, an adjustment to expected cash flow is necessary. Some practices reduce income through the use of bad debt expense rather than direct write-offs. Bad debt expense is a non-cash expense that represents an estimate of the dollar volume of write-offs that are likely to occur during a year. If bad debt expense is understated, practice profitability will be overstated.
***
***
Balance Sheet Adjustments
Adjustments also can be made to a practice’s balance sheet to remove non-operating assets and liabilities, and to restate asset and liability value at market rates (rather than cost rates). Assets and liabilities that are unrelated to the core practice being valued should be added to or subtracted from the value, depending on whether they are acquired by the buyer.
Examples include the asset value less outstanding debt of a vacant parcel of land, and marketable securities that are not needed to operate the practice. Other non-operating assets, such as the cash surrender value of officer life insurance, generally are liquidated by the seller and are not part of the business transaction.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit a RFP for speaking engagements: CONTACT: MarcinkoAdvisors@outlook.com
Posted on March 17, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
The Power of Attorney Mistake That Could Cost You Everything
By Rick Kahler CFP®
***
***
Recently, reading a training manual on elder abuse, I was reminded of a financial risk that is often overlooked. One of the fastest and easiest ways to unravel your financial security is to have the wrong person gain control of your money.
The example in the manual mirrored a heartbreaking situation I once experienced with a long-term client. As her mental and physical health declined, this single woman moved into assisted living. Her newly designated power of attorney, a relative from out of town, took control of her financial affairs.
Almost immediately, without consulting us, the relative began making large withdrawals, closed her accounts, and transferred funds elsewhere. They challenged the financial plan, investments, and strategies we had established to safeguard the client’s financial security and provide for her long-term care. Even though their actions threatened the client’s wellbeing, we were powerless to stop them. Our only recourse was to report the behavior to the authorities.
This heartbreaking and frustrating experience underscored just how critical it is to be mindful when executing a Power of Attorney. Besides designating someone you trust, it is wise to build in safeguards to prevent even a well-meaning relative from inadvertently derailing a carefully constructed financial plan.
***
***
One such safeguard is to include a financial advisor in your POA—as long as that person is a fee-only, fiduciary advisor with an obligation to act in your best interests. In many cases, advisors are hesitant to suggest this option because they are sensitive to the potential conflict of interest and do not want to appear self-serving. An unfortunate reality is that you should be cautious if an advisor, particularly one who sells products on commission, seems eager to be added to your POA.
Including your financial advisor in your POA does not mean you designate them as your agent to manage your affairs. Instead, you include a clause naming them as the professional of record you want your designated agent to continue working with. This creates continuity and accountability. It prevents your agent from replacing your advisor with someone who may be unfamiliar with your needs and goals, unqualified, or untrustworthy.
Your advisor might also recommend adding a secondary safeguard, such as naming an attorney or accountant to oversee the selection of a successor advisor in case your current advisor is unable to continue. This additional layer of protection ensures that the financial professionals guiding your portfolio remain aligned with your best interests. Taking these extra steps can save you—and your loved ones—from significant financial stress down the road.
Including safeguards in your POA is not about mistrusting your loved ones, but about equipping them with the right resources and support to act in your best interest. Financial management is complex, and it requires expertise that most people, even those with the best intentions, may not possess.
One of the hardest parts about planning for diminished financial capacity is the emotional aspect. No one likes to imagine a time when they might not be able to manage their own money. But in reality, taking steps now to protect your financial future is the ultimate act of control. It can help ensure that your wishes are respected and the financial foundation you’ve worked so hard to build remains intact.
Remember, too, that avoiding conversations often increases financial vulnerability. If you don’t have a POA or aren’t comfortable with what you do have, now is the time to bring it up with your advisor, attorney, or a trusted family member. These safeguards are about protecting yourself. They also support those you will rely on to care for you and your financial legacy,
Posted on March 16, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
DOCTOR PODIATRIC MEDICINE
By Staff Reporters
***
***
Background: Survey research is common practice in podiatry literature and many other health-related fields. An important component of the reporting of survey results is the provision of sufficient information to permit readers to understand the validity and representativeness of the results presented. However, the quality of survey reporting measures in the body of podiatry literature has not been systematically reviewed.
Objective: To examine the reporting of response rates and nonresponse bias within survey research articles published in the podiatric literature in order to provide a foundation with regard to the development of appropriate research reporting standards within the profession.
Methods: This study reports on a secondary analysis of survey research published in the Journal of the American Podiatric Medical Association, the Foot, and the Journal of Foot and Ankle Research. 98 surveys published from 2000 to 2018 were reviewed and data abstracted regarding the report of response rates and non-response bias.
Results: 67 surveys (68.4%) report a response rate while only 36 articles (36.7%) mention non-response bias in any capacity.
Conclusions: The findings suggest that there is room for improvement in the quality of reporting response rates and nonresponse in the body of podiatric literature involving survey research. Both nonresponse and response rate should be reported to assess survey quality. This is particularly problematic for studies that contribute to best practices.
Health actuaries analyze potential risks, profits and trends that will affect their employers, which are often in the health insurance, government health services and medical provider industries. They advise companies on issuing policies to consumers based on risks, calculated premiums and upcoming changes in health-care costs.
It’s common for an actuary to have a bachelor’s degree or higher in actuary studies, mathematics or statistics. Coursework on medical terminology and hierarchy of the medical field is also beneficial. In addition to academic education, certification is also necessary to reach “professional status,” which is required by most employers.
***
***
The professional organization, Society of Actuaries, certifies actuaries in the health and medical field. Their statistical work is commonly done with predictive tables, probability tables and life tables that are created on customized statistical analysis software such as Stata or XLSTAT.
The actuary field as a whole is growing faster than other fields, according to the Bureau of Labor Statistics [BLS]. In 2020, it expanded by 27 percent. The average annual salary for an actuary in 2010 was $87,650. More specifically, in the health insurance field, the salary was slightly higher at $91,000.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit a RFP for speaking engagements: CONTACT: MarcinkoAdvisors@outlook.com
Posted on March 16, 2025 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
DEFINITION
***
***
According to Wikipedia, a tontine (/ˈtɒntaɪn, -iːn, ˌtɒnˈtiːn/) is an investment linked to a living person which provides an income for as long as that person is alive. Such schemes originated as plans for governments to raise capital in the 17th century and became relatively widespread in the 18th and 19th centuries.
Tontines enable subscribers to share the risk of living a long life by combining features of a group annuity with a kind of mortality lottery. Each subscriber pays a sum into a trust and thereafter receives a periodical payout. As members die, their payout entitlements devolve to the other participants, and so the value of each continuing payout increases. On the death of the final member, the trust scheme is usually wound up.
Tontines are still common in France. They can be issued by European insurers under the Directive 2002/83/EC of the European Parliament. The Pan-European Pension Regulation passed by the European Commission in 2019 also contains provisions that specifically permit next-generation pension products that abide by the “tontine principle” to be offered in the 27 EU member states.
Questionable practices by U.S. life insurers in 1906 led to the Armstrong Investigation in the United States restricting some forms of tontines. Nevertheless, in March 2017, The New York Times reported that tontines were getting fresh consideration as a way for people to get steady retirement income.



 Support our online development, and advance our onground research initiatives in free market economics, as we seek to showcase the brightest Next-Gen minds.
THE ME-P DISCLAIMER: Posts, comments and opinions do not necessarily represent iMBA, Inc., but become our property after submission. Copyright © 2006 to-date. iMBA, Inc allows colleges, universities, medical and financial professionals and related clinics, hospitals and non-profit healthcare organizations to distribute our proprietary essays, photos, videos, audios and other documents; etc. However, please review copyright and usage information for each individual asset before submission to us, and/or placement on your publication or web site. Attestation references, citations and/or back-links are required. All other assets are property of the individual copyright holder.