ASSET PROTECTION: Fundamentals for Physicians

Don’t Leave Yourself Unprotected

By Nicholas Efthemis CFP®

The largest concern facing physicians today is how to protect their wealth against the proliferation of malpractice claims and extraordinarily high jury verdicts. Malpractice insurance has become so expensive that physicians are greatly reducing their coverage.

Even worse, some carriers are dropping physicians that have poor claims history. When meeting with physicians my message is a simple one. Take action and do so now. Constructing a complete asset protection plan is the single most critical step towards attaining financial freedom. Physicians work hard and long hours to create wealth, and are potentially one medical malpractice claim or general negligence claim away from financial catastrophe. Detailing every asset protection strategy is beyond the scope of this article, however I will review some important concepts you should know.

Good asset protection will prevent lawsuits. Conversely, the more personal assets that remain unprotected the more likely an attorney is willing to go after you. In fact, a physician with very high malpractice coverage and unprotected assets has a target on his back. This can be avoided through lower policy limits and a complete Asset Protection Plan.

What is the Best Asset Protection Plan?

The best Asset Protection Plan for a physician or any high net worth client removes all assets from the client’s name. The worst plan has all the assets in the client’s name. You will need to work with a specialized attorney to find the ideal plan for you. In many cases your largest asset are the funds in your retirement plan or IRA. The good news is that creditors cannot reach ERISA qualified plan assets. Common ERISA plans include:

1. 401(k) 403(b) Plan

2. Profit Purchase Plan

3. Money Purchase Plan

4. New Comparability Plans

5. Defined Benefit Plan

Keep in mind IRAs are not considered ERISA qualified plans and have no federal protection from creditors. Many individual states have protected IRAs in part or in full. In my state, New York, IRAs are fully protected. If you live in a state where they are not you should seriously consider moving the money into an ERISA qualified plan. This can be accomplished even if you are retired.

What about my house?

It is never a good idea, from an asset protection standpoint to own property in just your name. If you get sued the property is almost entirely at risk. Owning the marital home jointly with your spouse can be effective. You will protect the home from each other’s individual creditors (though not joint creditors). You should not title many assets as tenants by the entirety for several reasons. Physicians suffer a higher divorce rate than the already high national average of fifty percent. Should a divorce occur you will have ensured the spouse will receive half of that asset. Also, you do nothing to protect the asset against joint creditors.

How should my other assets be held?

You will need to consult a specialized asset protection attorney. Most effective plans involve the use of a corporate structure, limited liability company, or family limited partnership. Keep in mind that the entity you choose will have its own unique asset protection and tax consequences.

  • Sole proprietorships and partnerships are the worst way to own a business. If a sole proprietor is found negligent in his duties for the business that injures a third person, the sole proprietor is personally liable. If a product or employee harm a third person or someone is harmed on the premises, the sole proprietor is personally liable. With a partnership you have all of the above risks coupled with a partner who can cause you even more liability.
  • Limited Liability Companies (LLCs), Family Limited Liability Companies (FLLCs) and Family Limited Partnerships (FLPs) are the most commonly used tools by asset protection specialists today. A creditor attempting to obtain assets of a debtor when the assets are in a LLC will likely have very limited success. In fact, a charging order is the only remedy a court can give a creditor. A charging order does not allow creditors to sell assets of the LLC or force distributions of income. It also cannot transfer interest in the LLC to the creditor. A creditor who obtains a charging order against an LLC may in fact receive a K-1 for income they never did and may never receive.

What should I consider holding in an LLC?

I advise my physician clients to consider holding rental real estate, after tax investment accounts, planes, boats and any personal assets of value in an LLC. Unless you are single and your home is titled in your name alone, the marital home may not be a good candidate for transfer to an LLC. By doing so, you forego the capital gains exemption of $250,000 per spouse. Brokerage accounts can be owned by an LLC, and when constructed correctly you will have full ability to invest as you desire. The investments within the account would then be protected. Assets such as planes and boats may be best held in their own LLCs to protect the rest of your estate from their unique risk profiles.

Example:

  • Personal Residence $750,000 Tenants by the entirety
  • Vacation Property $300,000 LLC #1
  • Investment Account $900,000 LLC #1
  • 401 (k) 2,400,000 ERISA plans are federally protected
  • Boat $55,000 LLC #2

Assessment

The topic of asset protection is vast and complicated, but I hope to break out additional topics such as off-shoring, accounts receivable leveraging, fiduciary duties, and insurance in subsequent articles. My hope is that I have given you enough ideas and motivation to act now. You cannot wait until there is an issue. It is critical that your financial planner, attorney and accountant are all very knowledgeable on asset protection. Do not rely on a generalist to navigate such a complex yet critical issue.

About the Author:

Nicholas Efthemis is a Certified Financial Planner™ who helps physicians plan wisely and live fully by creating a financial plan that helps them focus on their medical practice and live a better life.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

***

***

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

NVIDIA: Booming Artificial Intelligence & Stock!

SPLITS STOCK 10:1 ANNOUNCED

By Staff Reporters

***

***

Nvidia sales rose 262% as AI keeps booming

The company whose chips are powering the Artificial Intelligence revolution saw an even bigger jump in sales last quarter than analysts had expected: to $26 billion.

CITE: https://www.r2library.com/Resource/Title/082610254

That’s a good sign for the future of AI and probably for the entire stock market, on which Nvidia has an outsized influence. CEO Jensen Huang declared “the next industrial revolution has begun,” as Nvidia predicted $28 billion in sales this quarter. The company also announced plans to split its stock 10-for-1 next

Stock Splits: https://medicalexecutivepost.com/2023/08/14/stock-splits-a-vital-equity-investing-concept-for-physician-investors/

AI: https://www.sas.com/en_us/insights/analytics/what-is-artificial-intelligence.html

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Uber Health, Lyft Healthcare, HHS Cyber Attacks as Markets Swoon

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

Your referral Count -0-

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Here’s where the major benchmarks ended:

  • The S&P 500 index lost 14.40 points (0.3%) to 5,307.01; the Dow Jones Industrial Average® ($DJI) declined 201.95 points (0.5%) to 39,671.04; the NASDAQ Composite® ($COMP) slipped 31.08 points (0.2%) to 16,801.54.
  • The 10-year Treasury note yield (TNX) rose more than 1 basis point to 4.426%.
  • The CBOE Volatility Index® (VIX) increased 0.43 to 12.29.

Retailer shares were among the market’s weakest performers after Target’s (TGT) quarterly results, released before Wednesday’s open, fell short of expectations. Target shares tumbled 8% after the company reported revenue fell 3% in the first quarter from the year-earlier period. During the company’s earnings call, Target CEO Brian Cornell noted “continued soft trends in discretionary categories” contributed to the revenue decline.

Energy companies were also under pressure after WTI Crude Oil (/CL) futures closed at a three-month low just above $77 per barrel.

CITE: https://www.r2library.com/Resource

Following a series of high-profile—and costly—cyberattacks against the healthcare industry, the federal government is stepping in with a $50+ million initiative intended to boost hospital cybersecurity, a division of the Department of Health and Human Services (HHS) announced on May 20th.

CITE: https://tinyurl.com/2h47urt5

Uber Health will begin rolling out a new solution designed for caregivers this summer, allowing individuals to add a caregiver to their Uber profile. That caregiver can then see and spend that person’s health benefits on eligible services, request rides to doctors’ appointments or order groceries. In the coming months, Uber Health will be working with Medicare Advantage, Medicaid and commercial plans to offer the solution.


U.S. Sens. Sheldon Whitehouse and Bill Cassidy, M.D., want to reform how primary care providers get paid through Medicare, and they also want to hear from the healthcare industry about the best way to do it. Together, they introduced a bipartisan bill, the Pay PCPs Act (S. 4338), last week to better support and improve pay for high-quality primary care providers. 


And… digital maternal health company Babyscripts announced a partnership with Lyft Healthcare to offer sponsored rides for people who are pregnant or postpartum and face barriers to transportation. The Lyft partnership will identify transportation-insecure patients and offer free rides to in-person appointments in traditional care settings and community-based healthcare services and programs.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

METAVERSE MEDICINE: Doctor, Patient Avatars Ahead?

By WebMD

In what some are calling the next iteration of the internet, the metaverse is an unfamiliar digital world where you could be an avatar navigating computer-generated places and interacting with others in real time. In this space, the constraints of our physical, bricks and mortar world and travel habits fade. And new opportunities and challenges emerge.

***


***

READ HERE: https://www.webmd.com/a-to-z-guides/news/20220812/metaverse-medicine-doctor-patient-avatars-ahead

Cite: https://www.amazon.com/Dictionary-Health-Information-Technology-Security/dp/0826149952/ref=sr_1_5?ie=UTF8&s=books&qid=1254413315&sr=1-5

***

COMMENTS APPRECIATED

Thank You

***

PODCAST: Medicare Value Based Payments Explained

By Eric Bricker MD

***

***

COMMENTS APPRECIATED

Thank You

***

***

***

PHYSICIAN’S BEWARE: Psychological “INVESTING MIND TRAPS”

By Dr. David Edward Marcinko MBA MEd CMP™

SPONSOR: http://www.MarcinkoAssociates.com

As, as human beings, our brains are booby-trapped with psychological barriers that stand between making smart financial decisions and making dumb ones. The good news is that once you realize your own mental weaknesses, it’s not impossible to overcome them. 

CITE: https://www.r2library.com/Resource

In fact, psychiatrist and medical colleague Wes Boyd MD PhD MA related the following mind-traps and investing impediments that have yet to be appreciated by the financial planning community writ-large:

  • Anchoring happens when we place too much emphasis on the first piece of information we receive regarding a given subject. For instance, when shopping for a wedding ring a salesman might tell us to spend three months’ salary. After hearing this, we may feel like we are doing something wrong if we stray from this advice, even though the guideline provided may cause us to spend more or less than we can afford. Ditto for buy / sell stock recommendations without our own due diligence.
  • Myopia makes it hard for us to imagine what our lives might be like in the future. For example, because we are young, healthy, and in our prime medical practice earning years now, it may be hard for us to picture what life will be like when our health depletes and we know longer have the earnings necessary to support our standard of living. This short sighted thinking makes it hard to save adequately when we are young, when saving does the most good.
  • Gambler’s fallacy occurs when we subconsciously believe we can use past events to predict the future. It is common for the hottest sector during one calendar year to attract the most doctor investors the following year. Of course, just because an investment did well last year doesn’t mean it will continue to do well this year. In fact, it is more likely to lag the market.
  • Avoidance is simply procrastination. Even though you may only have the opportunity to adjust your health care plan through your employer once per year, researching alternative health plans is too much work and too boring for us to get around to it. Consequently, we stick with a plan that may not be best for us.
  • Loss aversion affected many investors during the stock market crash of 2008. During the crash, many doctors decided they couldn’t afford to lose more and sold their investments. Of course, this caused the investors to sell at market troughs and miss the quick, dramatic recovery.
  • Overconfident investing happens when we believe we can out-smart other investors via market timing or through quick, frequent trading. Data convincingly shows that people who trade most often under-perform the market by a significant margin over time.
  • Mental accounting takes place when we assign different values to money depending on where we get it from. For instance, even though we may have an aggressive saving goal for the year, it is likely easier for us to save money that we worked for than money that was given to us as a gift.
  • Herd mentality makes it very hard for humans to not take action when everyone around us does. For example, we may hear stories of people making significant profits buying, fixing up, and flipping homes and have the desire to get in on the action, even though we have no experience in real estate.

CMP: http://www.CertifiedMedicalPlanner.org

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Hims & Hers, MSFT-AI, Neuralink, FDIC and New Market Highs

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Microsoft unveiled new PCs with AI-powered features.

CITE: https://www.r2library.com/Resource

Hims & Hers stock soared as much as 38% on the news that it’ll provide GLP-1 injections with the same active ingredient as Ozempic or Wegovy for just $199/month—an 85% discount compared to Wegovy’s ~$1,350 monthly price tag (without insurance).

***

FDIC Chair Martin Gruenberg will resign after an investigation found widespread sexual harassment at the agency. But he won’t step down until a successor is named.

CITE: https://tinyurl.com/2h47urt5

The FDA granted Elon Musk’s neurotech company Neuralink, approval to place its brain chip into a second human test subject using a new method designed to correct issues that arose after its inaugural insertion in January, per the Wall Street Journal.

And, Optum Rx is shaking up its pharmacy model. The business says it will make drug costs more predictable and transparent for clients.

CITE: https://tinyurl.com/tj8smmes

  • All three indexes ended the day higher after Fed Governor Christopher Waller stopped by CNBC and mentioned he doesn’t think raising interest rates is in the cards, even if the Fed is waiting for more data before making cuts. The NASDAQ continued to hit new all-time highs today as investors place their bets before Nvidia’s earnings announcement tomorrow afternoon, and the S&P 500 hit yet another record.
  • Copper continued to rise as the market comes to terms with the metal’s importance, while oil fell on the news that the Biden administration will release 1 million barrels of gasoline this summer from the Northeast reserve. Meanwhile, ethereum continued to climb on the news that a new ETF may be joining the fray.

Here’s where the major benchmarks ended:

  • The S&P 500 index rose 13.28 points (0.3%) to 5,321.41; the Dow Jones Industrial Average® ($DJI) gained 66.22 points (0.2%) to 39,872.99; the NASDAQ Composite advanced 37.75 points (0.2%) to 16,832.62.
  • The 10-year Treasury note yield (TNX) lost more than 2 basis points to 4.414%.
  • The CBOE Volatility Index® (VIX) fell 0.29 to 11.86.

Banking and consumer staples were among the market’s strongest performers Tuesday, while utility shares extended a sharp upswing over the past month. The Dow Jones Utility Average® ($DJU) added 0.5% and closed at a 12-month high. Transportation companies were among the weakest performers.

In other markets, Gold (/GC) futures slipped from Monday’s record high above $2,454 per ounce, while Silver (/SI) futures ended near a 12-year high around $32.21. Gold futures are still up 17% this year due to several factors, including reports of China’s central bank buying actual gold as well as escalating conflict in the Middle East. Gold is viewed by some as a safe-haven asset during periods of heightened geopolitical tension.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

PHYSICIANS & DENTISTS: Financial Consulting & Planning

Sponsored by: http://www.MARCINKOASSOCIATES.com

START TO FINISH CYCLE

***

Our Process

***

READ HERE: https://marcinkoassociates.com/financial-planning/

RELATED: https://medicalexecutivepost.com/2023/12/15/doctor-are-you-a-financial-advisors-customer-or-client/

COMMENTS APPRECIATED

Thank You

***

***

PHYSICIANS ONLY: Hedge Funds and Venture Capitalists

SPONSORED: http://www.MARCINKOASSOCIATES.com

START TO FINISH CYCLE

***

Our Process

***

READ HERE: https://marcinkoassociates.com/hedge-funds/

MORE: https://medicalexecutivepost.com/2023/02/19/what-is-an-unregistered-security/

COMMENTS APPRECIATED

Thank You

***

***

EXPLAINED: Medical “Bottle Neck” Accounting

VARIANCE AND BOTTLE-NECK ACCOUNTING

DR. DAVID E. MARCINKO MBA MEd CMP

Any healthcare organization usually has several processes involved in the utilization of its patient services. Unfortunately, bottlenecks may arise which constrain the amount of services any given healthcare entity can deliver. 

Accounting Definition 

An accounting “bottleneck” is a process that has a low output and limits total healthcare entity revenues. If a medical business entity wants to increase sales or revenues, it has to solve its bottleneck [ie., access management] problems. 

Traditional Variance Analysis Dilemma 

With traditional variance analysis [VA], managers and administrators analyze the difference between budgeted patient revenues and actual revenues. Typically, differences between budgeted revenues and actual revenues are analyzed as seen in the example below.

Initially postulated by Horngren and Foster for manufacturing processes, VA can now be modified for medical business entity use. 

Example: 

  Patient Service Units   Contract/UCR Fee    
Budgeted sales revenues 10,000,000 * 1,23 = $ 12,300,000
Actual sales revenues 9,000,000 * 1,21 = $ 10,890,000
          -/- —————-
Total variance         $ 1,410,000
Traditional Assessment
Actual patient revenues were lower than budgeted; and the unfavorable patient sales volume variance was (9,000,000 – 10,000,000) * $ 1,23 = – $ 1,230,000. 


The actual patient revenue price was lower than budgeted as the unfavorable price variance was: ($ 1,21 – $ 1,23) * 9,000,000 = – 180,000.

Traditional variance analysis however does not point out which of the processes were bottlenecks, which caused the negative volume variance.Thus, a normal variance analysis can’t be used to solve bottlenecks in a clinic, hospital or medical practice.

Enter B-N Accounting

In bottleneck accounting however, managers and healthcare administrators determine the bottlenecks in a medical organization.And, a bottleneck accounting report shows which process were bottlenecks occur and how much money is lost in each bottleneck.

Example:

Bottleneck Patient Sales Revenues $ 800,000
Bottleneck Dep. II $ 350,000
Other Bottlenecks $ 80,000
  + —————-
Total Volume Variance $ 1,230,000

Conclusion: 

The managerial accounting modification for “bottlenecks” not only points out the bottlenecks to solve, it also shows which bottleneck is to be handled first.

And so, what are your thoughts on this accounting machination? Please comment.

References: Horngren, C. T. and G. Foster, ‘Cost Accounting, A Managerial Emphasis’, Prentice-Hall, Inc. 1987. 

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com 

Subscribe Now: Security is assured.

***

***

***

PSYCHOLOGICAL “TRAPS” of Investing

MIND TRAPS PHYSICIAN INVESTORS MUST REDUCE AND AVOID AT ALL COSTS

See the source image

By Dr. David E. Marcinko MBA MEd CMP®

SPONSOR: http://MarcinkoAssociates.com

CMP logo

SPONSOR: http://www.CertifiedMedicalPlanner.org

As human beings, our brains are booby-trapped with psychological barriers that stand between making smart financial decisions and making dumb ones. The good news is that once you realize your own mental weaknesses, it’s not impossible to overcome them.

CITE: https://www.r2library.com/Resource/Title/0826102549

In fact, Mandi Woodruff, a financial reporter whose work has appeared in Yahoo! Finance, Daily Finance, The Wall Street Journal, The Fiscal Times and the Financial Times among others; related the following mind-traps in a September 2013 essay for the finance vertical Business Insider; as these impediments are now entering the lay-public zeitgeist.

***

8 Psychological Traps All Stock Investors Should Avoid - YouTube

 Anchoring happens when we place too much emphasis on the first piece of information we receive regarding a given subject. For instance, when shopping for a wedding ring a salesman might tell us to spend three months’ salary. After hearing this, we may feel like we are doing something wrong if we stray from this advice, even though the guideline provided may cause us to spend more than we can afford.

 Myopia makes it hard for us to imagine what our lives might be like in the future. For example, because we are young, healthy, and in our prime earning years now, it may be hard for us to picture what life will be like when our health depletes and we know longer have the earnings necessary to support our standard of living. This short-sightedness makes it hard to save adequately when we are young, when saving does the most good.

 Gambler’s fallacy occurs when we subconsciously believe we can use past events to predict the future. It is common for the hottest sector during one calendar year to attract the most investors the following year. Of course, just because an investment did well last year doesn’t mean it will continue to do well this year. In fact, it is more likely to lag the market.

 Avoidance is simply procrastination. Even though you may only have the opportunity to adjust your health care plan through your employer once per year, researching alternative health plans is too much work and too boring for us to get around to it. Consequently, we stick with a plan that may not be best for us.

 Loss aversion affected many investors during the stock market crash of 2008. During the crash, many people decided they couldn’t afford to lose more and sold their investments. Of course, this caused the investors to sell at market troughs and miss the quick, dramatic recovery.

 Overconfident investing happens when we believe we can out-smart other investors via market timing or through quick, frequent trading. Data convincingly shows that people who trade most often underperform the market by a significant margin over time.

 Mental accounting takes place when we assign different values to money depending on where we get it from. For instance, even though we may have an aggressive saving goal for the year, it is likely easier for us to save money that we worked for than money that was given to us as a gift.

MORE: https://medicalexecutivepost.com/2021/09/04/more-on-money-psychology/

RELATED: https://medicalexecutivepost.com/2014/12/15/on-internet-investing-psychology/

 Herd mentality makes it very hard for humans to not take action when everyone around us does. For example, we may hear stories of people making significant profits buying, fixing up, and flipping homes and have the desire to get in on the action, even though we have no experience in real estate.

YOUR COMMENTS ARE APPRECIATED.

Thank You

***

RISK MANAGEMENT: https://www.routledge.com/Risk-Management-Liability-Insurance-and-Asset-Protection-Strategies-for/Marcinko-Hetico/p/book/9781498725989

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors : Best Practices from Leading Consultants and Certified Medical Planners™ book cover

***

“ACTIVE” INVESTMENT STRATEGIES: For Physicians

And … why doctors are different?

By Dr. David Edward Marcinko MBA MEd CMP

SPONSOR: http://www.MarcinkoAssociates.com

By Dr. David Edward Marcinko MBA CMP™

There are two distinct forms of financial analysis investment strategies often used by medical colleague investors who desire to pursue an active investment strategy.

Technical Analysis: Technical analysts, sometimes referred to as chartists, use historical price data and transaction volume data to identify mis-priced securities. A key belief shared by technical analysts is that stock prices follow recurring patterns and that once these historical patterns are identified, they can be used to identify future security prices. The heart of technical analysis is identifying significant shifts in the macro/micro economic supply and demand factors for a particular securities investment.

Skeptics of technical analysis generally subscribe to the notion that the markets efficiently and accurately price securities. In fact, the weak form of the Efficient Market Hypothesis [EMH] is based on the view that investors cannot consistently earn superior returns using historical data and technical analysis alone.

Fundamental Analysis: In contrast to technical analysis – which relies on historical market returns / transactions data – fundamental analysis focuses on the underlying company’s assets, earnings, risks, dividends and intrinsic security factors to identify mis-priced securities.

Furthermore, investors using fundamental analysis can use either a top-down or bottom-up approach:

  • The top-down investor starts with global economics, including both international and national economic indicators. These may include GDP growth rates, inflation, interest rates, exchange rates, productivity and energy prices. They subsequently narrow their search to regional / industry analysis of total sales, price levels, the effects of competing products, foreign competition and entry or exit from the industry. Often they refine their search to the best business in the area being studied.
  • The bottom-up investor starts with specific businesses, regardless of their industry / region, and proceeds in reverse of the top-down approach. Bottom-up investing is an approach that focuses on analyzing individual stocks and de-emphasizes the significance of macroeconomic and market cycles. In other words, bottom-up investing typically involves focusing on a specific company’s fundamentals, such as revenue or earnings, versus the industry or the overall economy. The bottom-up investing approach assumes individual companies can perform well even in an industry that is under performing, at least on a relative basis.

And so, a medical professional utilizing fundamental analysis is attempting to find securities that are trading at market prices below their intrinsic value. Skeptics suggest this is difficult or almost impossible to achieve.

Thus, while technical analysis focuses on market price history, a security’s intrinsic fundamental analysis is determined independent of the security’s market value. Of course, a combination of both fundamental and technical analysis can also be considered.

DOCTORS ARE DIFFERENT: https://marcinkoassociates.com/doctors-unique/

CMP: http://www.CertifiedMedicalPlanner.org

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Abbvie, Treasuries, Gold, Copper and the NASDAQ Rally

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

The yield on the 10-year Treasury rose as investors wait for word from the FOMC on Wednesday, while oil initially rose on the news of the death of the president of Iran, though it fell back down to end the day lower after succession of the presidency was settled. But investors were clearly still feeling jittery as gold hit new highs on the back of geopolitical concerns. Copper also rose to a new all-time high.

Here’s where the major benchmarks ended:

  • The S&P 500 index gained 4.86 points (0.1%) to 5,308.13; the Dow Jones Industrial Average® ($DJI) lost 196.82 points (0.5%) to 39,806.77; the NASDAQ Composite rallied 108.91 points (0.7%) to 16,794.87.
  • The 10-year Treasury note yield (TNX) increased more than 2 basis points to 4.443%.
  • The CBOE Volatility Index® (VIX) rose 0.15 to 12.14.

Nvidia’s gain helped push the PHLX Semiconductor Index (SOX) more than 2% to a two-and-a-half-month high and just under a record close posted in early March. The small-cap Russell 2000® Index (RUT) added 0.3% and ended slightly below a six-week high posted last Wednesday. 

CITE: https://www.r2library.com/Resource

JPMorgan shares fell 4.5% as investors realized that they won’t have Jamie Dimon around forever—he told shareholders at a meeting today that his 5-year timetable for leaving the company no longer applies.

CITE: https://tinyurl.com/2h47urt5

After AbbVie’s Humira, the best-selling drug in the world, lost patent exclusivity in 2023, company executives placed their bets on two other AbbVie drugs, Skyrizi and Rinvoq, to make up for an anticipated steep decline in revenue.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

15 YEAR JOURNEY: From Active to Passive Investing?

By Staff Reporters

***

***

Historical Review

As can now be discerned 15 years later, two trends emerged from the aftermath of the 2008 financial crisis. One was a new type of investment that concentrated capital among a small number of firms. The other was left-wing activism in the style of Occupy Wall Street. Combined, these trends helped empower Wall Street behemoths to push much of the corporate wokeness that is so common today. The financial meltdown precipitated a transition from active to passive investment.

Definitions

Active investment is what one typically thinks of as investing — making risky stock purchases in an attempt to beat the market in the short-term.

More: https://medicalexecutivepost.com/2023/03/06/understanding-active-asset-allocation/

Passive investment, on the other hand, requires much less effort. According to Investopedia, it is a long-term strategy where investors try to “replicate market performance by constructing well-diversified portfolios” (e.g. mutual funds) typically based on a “representative benchmark” like the S&P 500 index.  In other words, it bets on the market rather than against it.

More: https://medicalexecutivepost.com/2015/03/19/more-on-passive-investing-for-physicians/

Dichotomy

Passive investing took off after the financial crisis when investors realized it wasn’t worth trying to beat the market. Why pay a broker a one to two percent fee every year to actively manage your assets, especially when the downturn revealed they often under-performed the regular market returns? Many opted for passive asset management that cost a fraction of a brokerage fee.

More: https://medicalexecutivepost.com/2022/03/09/active-or-passive-investing-pursuits/

Today

In fact, one study found that between 2008 and 2015, active funds lost $800 billion while passive funds gained over $1 trillion in new investment. As of 2019, more money is now invested in passive than in active funds.

Cite: https://www.cambridge.org/core/journals/business-and-politics/article/hidden-power-of-the-big-three-passive-index-funds-reconcentration-of-corporate-ownership-and-new-financial-risk/30AD689509AAD62F5B677E916C28C4B6

***

***

COMMENTS APPRECIATED

Thank You

***

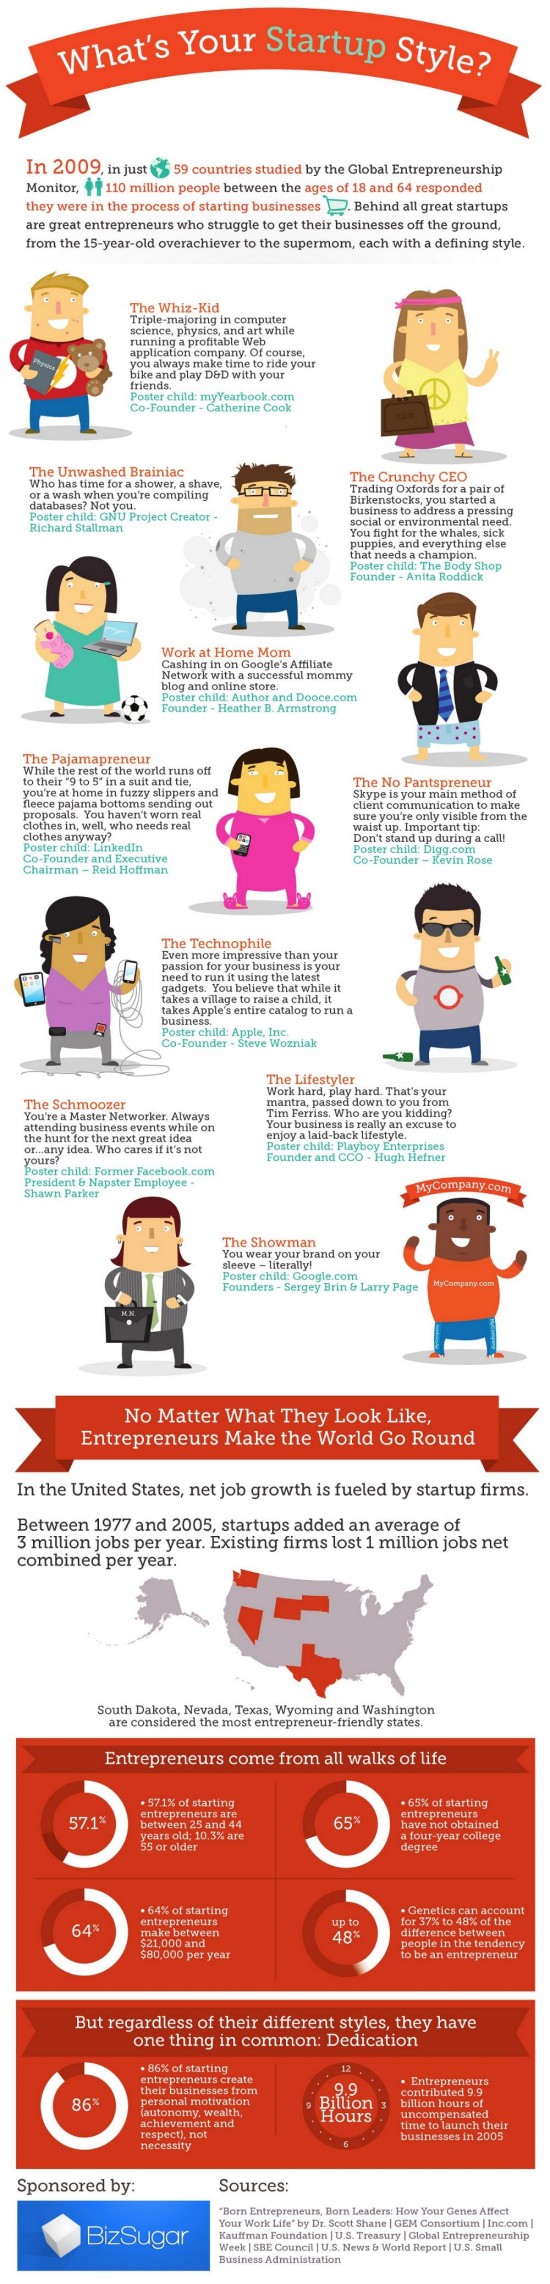
What’s Your Business [Medical Practice] Start Up Style?

Entrepreneurs, their Styles and the Drive Behind Them!

[By staff reporters]

SPONSOR: http://www.MarcinkoAssociates.com

It goes without saying that it takes a special kind of person to become a doctor, and an entrepreneur.

Driven, motivated, innovative – these are just a few of the many ways to describe individuals who risk everything to transform their vision into reality; or to save lives.

We created this infographic to celebrate the entrepreneur, not only for their individual, quirky styles, but also for their contributions to the global economy.

Source: bizsugar.com

How it Works

***

***

Assessment

Are medical professionals the same or different today -OR- in the health 2.0 future?

MUCH MORE FOR DOCTORS: https://marcinkoassociates.com/welcome-medical-colleagues/

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product Details

 ***

DAILY UPDATE: Fiduciary Rule with Stock Market Earnings Week

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

For last the week, the NASDAQ Composite (^IXIC) rose more than 2% while the S&P 500 (^GSPC) popped more than 1.5%. The Dow Jones Industrial Average (^DJI) rose more than 1%, closing above 40,000 for the first time ever on Friday.

In the week ahead, highly anticipated earnings results from Nvidia (NVDA) are expected to be the key catalyst for markets. Results from Target (TGT), Palo Alto Networks (PANW), and Lowe’s (LOW) will also be closely tracked by investors.

The week is also expected to be quieter on the economic front, with updates on activity in the manufacturing and services sectors as well as the final reading of consumer sentiment for May on tap. Minutes from the Fed’s May meeting are also expected on Wednesday afternoon.

CITE: https://www.r2library.com/Resource

The rule, finalized last month by the Labor Department, requires investment advisers to provide “prudent, loyal, honest advice free from overcharges” and avoid recommendations that favor their interests at the expense of their clients. It also updates the definition of an investment advice fiduciary under the Employee Retirement Income Security Act (ERISA) and Internal Revenue Code. 

Under the new definition, a fiduciary includes any financial services provider who offers investment advice to a retirement investor for a fee and who claims to be acting as a fiduciary or who a reasonable investor understands to be a trusted adviser acting in their best interest. The update removes the requirement that fiduciaries provide advice on a regular basis, bringing one-time advice under the rule. The Biden administration has argued that the previous definition, which was written in 1975, is outdated and has not kept pace with changes to the retirement landscape. 

CITE: https://tinyurl.com/2h47urt5

And, confidence in the U.S. dollar has waned, as forecasts suggest that a dip in inflation might allow the Federal Reserve to slash interest rates. With a notable 5% climb earlier this year, the dollar is now bracing for its first loss of 2024, triggered by a promising inflation report.

CITE: https://tinyurl.com/tj8smmes

Finally, fourteen of the world’s 20 largest stock markets have hit all-time highs recently, including England, Japan, Brazil, India, and Canada, according to Bloomberg. In the USA, the S&P 500 (also at a record) hasn’t dropped more than 2% in a trading session in 311 days, the longest streak in five years.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

PODCAST: Medicare Launched the First VBC Initiative 40 Years Ago!

****

See the source image

BY DR. ERIC BRICKER MD

***

Value-Based Care Happened 40 Years

Why Was Medicare Able to Bring About So Much Value-Based Payment Change in 3 Years (’83-’86) Compared to the Relatively Little Change That Has Occurred in the 11 Years Since the Affordable Care Act?

Watch the Video to Find Out.

YOUR COMMENTS ARE APPRECIATED.

Thank You

***

PODCAST: Healthcare Start-Up Accelerators and Incubators

By Dr. Eric Bricker MD

***

***
MORE: https://medicalexecutivepost.com/2017/04/02/on-digital-health-accelerator-and-corporate-start-up-programs/

COMMENTS APPRECIATED

Thank You

***

***

***

DAILY UPDATE: Jerome Powell, DJIA, Reddit and Life Insurance

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Young adults are delaying life insurance purchases due to financial constraints and a preference for spending on immediate experiences. The insurance industry is responding with digital-first strategies and more flexible products.

CITE: https://www.r2library.com/Resource

The DJIA closed above 40,000 for the first time after briefly crossing the milestone the day before and clinching its fifth winning week. Reddit shot up after announcing a partnership with OpenAI that lets the AI train on your posts and gives Reddit advertising dollars and the ability to use the tech to make new tools.

But, GameStop stock plunged after the recently reinvigorated meme stock filed to sell 45 million new shares and revealed that sales were down last quarter.

CITE: https://tinyurl.com/2h47urt5

Jerome Powell, chair of the Federal Reserve has tested positive for Covid. But the economy needn’t worry because he’s working from home.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

RE-BROADCAST: An Interview with Fiduciary Bennett Aikin AIF®

On Financial Fiduciary Accountability

[By Dr. David E. Marcinko MBA MEd CMP™]

[By Ann Miller; RN, MHA]

Currently, there is a growing dilemma in the financial sales and services industry. It goes something like this:

  • What is a financial fiduciary?
  • Who is a financial fiduciary?
  • How can I tell if my financial advisor is a fiduciary?

Now, in as much as this controversy affects laymen and physician-investors alike, we went right to the source for up-to-date information regarding this often contentious topic, for an email interview and Q-A session, with Ben Aikin.ben-aikin

About Bennett Aikin AIF® and fi360.com

Bennett [Ben] Aikin is the Communications Coordinator for fi360.com. He oversees all communications for fi360. His responsibilities include messaging, brand management, copyrights and trademarks, and publications. Mr. Aikin received his BA in English from Virginia Tech in 2003 and is currently an MS candidate in Journalism from Ohio University.

Q. Medical Executive Post 

You have been very helpful and gracious to us. So, let’s get right to it, Ben. In the view of many; attorneys, doctors, CPAs and the clergy are fiduciaries; most all others who retain this title seem poseurs; sans documentation otherwise.

A. Mr. Aikin

You are correct. Attorneys, doctors and clergy are the prototype fiduciaries. They have a clear duty to put the best interests of their clients, patients, congregation, etc., above their own. [The duty of a CPA isn’t as clear to me, although I believe you are correct]. Furthermore, this is one of the first topics we address in our AIF training programs, and what we call the difference between a profession and an industry.  The three professions you name have three common characteristics that elevate them from an industry to a profession:

  1. Recognized body of knowledge
  2. Society depends upon practitioners to provide trustworthy advice
  3. Code of conduct that places the clients’ best interests first

Q. Medical Executive Post 

It seems that Certified Financial Planner®, Chartered Financial Analysts, Registered Investment Advisors and their representatives, Registered Representative [stock-brokers] and AIF® holders, etc, are not really financial fiduciaries, either by legal statute or organizational charter. Are we correct, or not? Of course, we are not talking ethics or morality here. That’s for the theologians to discuss.

A. Mr. Aikin

One of the reasons for the “alphabet soup”, as you put it in one of your white papers [books, dictionaries and posts] on financial designations, is that while there is a large body of knowledge, there is no one recognized body of knowledge that one must acquire to enter the financial services industry.  The different designations serve to provide a distinguisher for how much and what parts of that body of knowledge you do possess.  However, being a fiduciary is exclusively a matter of function. 

In other words, regardless of what designations are held, there are five things that will make one a fiduciary in a given relationship:

  1. You are “named” in plan or trust documents; the appointment can be by “name” or by “title,” such as CFO or Head of Human Resources
  2. You are serving as a trustee; often times this applies to directed trustees as well
  3. Your function or role equates to a professional providing comprehensive and continuous investment advice
  4. You have discretion to buy or sell investable assets
  5. You are a corporate officer or director who has authority to appoint other fiduciaries

So, if you are a fiduciary according to one of these definitions, you can be held accountable for a breach in fiduciary duty, regardless of any expertise you do, or do not have. This underscores the critical nature of understanding the fiduciary standard and delegating certain duties to qualified “professionals” who can fulfill the parts of the process that a non-qualified fiduciary cannot.

Q. Medical Executive Post 

How about some of the specific designations mentioned on our site, and elsewhere. I believe that you may be familiar with the well-known financial planner, Ed Morrow, who often opines that there are more than 98 of these “designations”? In fact, he is the founder of the Registered Financial Consultants [RFC] designation. And, he wrote a Foreword for one of our e-books; back-in-the-day. His son, an attorney, also wrote as a tax expert for us, as well. So, what gives?

A. Mr. Aikin

As for the specific designations you list above, and elsewhere, they each signify something different that may, or may not, lend itself to being a fiduciary: For example:

• CFP®: The act of financial planning does very much imply fiduciary responsibility.  And, the recently updated CFP® rules of conduct does now include a fiduciary mandate:

• 1.4 A certificant shall at all times place the interest of the client ahead of his or her own. When the certificant provides financial planning or material elements of the financial planning process, the certificant owes to the client the duty of care of a fiduciary as defined by CFP Board. [from http://www.cfp.net/Downloads/2008Standards.pdf]

•  CFA: Very dependent on what work the individual is doing.  Their code of ethics does have a provision to place the interests of clients above their own and their Standards of Practice handbook makes clear that when they are working in a fiduciary capacity that they understand and abide by the legally mandated fiduciary standard.

• FA [Financial Advisor]: This is a generic term that you may find being used by a non-fiduciary, such as a broker, or a fiduciary, such as an RIA.

• RIA: Are fiduciaries.  Registered Investment Advisors are registered with the SEC and have obligations under the Investment Advisers Act of 1940 to provide services that meet a fiduciary standard of care.

• RR: Registered Reps, or stock-brokers, are not fiduciaries if they are doing what they are supposed to be doing.  If they give investment advice that crosses the line into “comprehensive and continuous investment advice” (see above), their function would make them a fiduciary and they would be subject to meeting a fiduciary standard in that advice (even though they may not be properly registered to give advice as an RIA).

• AIF designees: Have received training on a process that meets, and in some places exceeds, the fiduciary standard of care.  We do not require an AIF® to always function as a fiduciary. For example, we allow registered reps to gain and use the AIF® designation. In many cases, AIF designees are acting as fiduciaries, and the designation is an indicator that they have the full understanding of what that really means in terms of the level of service they provide.  We do expect our designees to clearly disclose whether they accept fiduciary responsibility for their services or not and advocate such disclosure for all financial service representatives.

Q. Medical Executive Post 

Your website, http://www.fi360.com, seems to suggest, for example, that banks/bankers are fiduciaries. We have found this not to be the case, of course, as they work for the best interests of the bank and stockholders. What definitional understanding are we missing?

A. Mr. Aikin

Banks cannot generally be considered fiduciaries.  Again, it is a matter of function. A bank may be a named trustee, in which case a fiduciary standard would generally apply.  Banks that sell products are doing so according to their governing regulations and are “prudent experts” under ERISA, but not necessarily held to a fiduciary standard in any broader sense.

Q. Medical Executive Post 

And so, how do we rectify the [seemingly intentional] industry obfuscation on this topic. We mean, our readers, subscribers, book and dictionary purchasers, clients and colleagues are all confused on this topic. The recent financial meltdown only stresses the importance of understanding same.

For example, everyone in the industry seems to say they are the “f” word. But, our outreach efforts to contact traditional “financial services” industry pundits, CFP® practitioners and other certification organizations are continually met with resounding silence; or worse yet; they offer an abundance of parsed words and obfuscation but no confirming paperwork, or deep subject-matter knowledge as you have kindly done. We get the impression that some FAs honesty do-not have a clue; while others are intentionally vague.

A. Mr. Aikin

All of the evidence you cite is correct.  But that does not mean it is impossible to find an investment advisor who will manage to a fiduciary standard of care and acknowledge the same. The best way to rectify confusion as it pertains to choosing appropriate investment professionals is to get fiduciary status acknowledged in writing and go over with them all of the necessary steps in a fiduciary process to ensure they are being fulfilled. There also are great resources out there for understanding the fiduciary process and for choosing professionals, such as the Department of Labor, the SEC, FINRA, the AICPA’s Personal Financial Planning division, the Financial Planning Association, and, of course, Fiduciary360.

We realize the confusion this must cause to those coming from the health care arena, where MD/DO clearly defines the individual in question; as do other degrees [optometrist, clinical psychologist, podiatrist, etc] and medical designations [fellow, board certification, etc.]. But, unfortunately, it is the state of the financial services industry as it stands now.

Q. Medical Executive Post 

It is as confusing for the medical community, as it is for the lay community. And, after some research, we believe retail financial services industry participants are also confused. So, what is the bottom line?

A. Mr. Aikin

The bottom line is that lay, physician and all clients have a right to expect and demand a fiduciary standard of care in the managing of investments. And, there are qualified professionals out there who are providing those services.  Again, the best way to ensure you are getting it is to have fiduciary status acknowledged in writing, and go over the necessary steps in a fiduciary process with them to ensure it is being fulfilled.

Q. Medical Executive Post 

The “parole-evidence” rule, of contract law, applies, right? In dealing with medical liability situations, the medics and malpractice attorneys have a rule: “if it wasn’t written down, it didn’t happen.”  

A. Mr. Aikin

An engagement contract accepting fiduciary status should trump a subsequent attempt to claim the fiduciary standard didn’t apply. But, to reiterate an earlier point, if someone acts in one of the five functional fiduciary roles, they are a fiduciary whether they choose to acknowledge it or not.  I have attached a sample acknowledgement of fiduciary status letter with copies of our handbook, which details the fiduciary process we instruct in our programs, and our SAFE, which is basically a checklist that a fiduciary should be able to answer “Yes” to every question to ensure the entire fiduciary process is being covered.

Q. Medical Executive Post 

It is curious that you mention checklists. We have a post arguing that very theme for doctors and hospitals as they pursue their medial error reduction, and quality improvement, endeavors. And, we applaud your integrity, and wish only for clarification on this simple fiduciary query?

A. Mr. Aikin

Simple definition: A fiduciary is someone who is managing the assets of another person and stands in a special relationship of trust, confidence, and/or legal responsibility.

Q. Medical Executive Post 

Who is a financial fiduciary and what, if any, financial designation indicates same?

A. Mr. Aikin

Functional definition: See above for the five items that make you a fiduciary.

Financial designations that unequivocally indicate fiduciary duty: Short answer is none, only function can determine who is a fiduciary. 

Q. Medical Executive Post 

Please repeat that?

A. Mr. Aikin

Financial designations that indicate fiduciary duty: none. It is the function that determines who is a fiduciary.  Now, having said that, the CFP® certification comes close by demanding their certificants who are engaged in financial planning do so to a fiduciary standard. Similarly, other designations may certify the holder’s ability to perform a role that would be held to a fiduciary standard of care.  The point is that you are owed a fiduciary standard of care when you engage a professional to fill that role or they functionally become one.  And, if you engage a professional to fill a non-fiduciary role, they will not be held to a fiduciary standard simply because they have a particular designation.  One of the purposes the designations serve is to inform you what roles the designation holder is capable of fulfilling.

It is also worth keeping in mind that just being a fiduciary doesn’t equate to a full knowledge of the fiduciary standard. The AIF® designation indicates having been fully trained on the standard.

Q. Medical Executive Post 

Yes, your website mentions something about fiduciaries that are not aware of same! How can this be? Since our business model mimics a medical model, isn’t that like saying “the doctor doesn’t know he is doctor?” Very specious, with all due respect!

A. Mr. Aikin

I think it is first important to note that this statement is referring not just to investment professionals.  Part of the audience fi360 serves is investment stewards, the non-professionals who, due to facts and circumstances, still owe a fiduciary duty to another.  Examples of this include investment committee members, trustees to a foundation, small business owners who start 401k plans, etc.  This is a group of non-sophisticated investors who may not be aware of the full array of responsibilities they have. 

However, even on the professional side I believe the statement isn’t as absurd as it sounds.  This is basically a protection from both ignorant and unscrupulous professionals.  Imagine a registered representative who, either through ignorance or design, begins offering comprehensive and continuous investment advice.  Though they may deny or be unaware of the fact, they have opened themselves up to fiduciary liability. 

Q. Medical Executive Post 

Please clarify the use of arbitration clauses in brokerage account contracts for us. Do these disclaim fiduciary responsibility? If so, does the client even know same?

A. Mr. Aikin

By definition, an engagement with a broker is a non-fiduciary relationship.  So, unless other services beyond the scope of a typical brokerage account contract are specified, fiduciary responsibility is inherently not applicable.  Unfortunately, I do imagine there are clients who don’t understand this. Furthermore, AIF® designees are not prohibited from signing such an agreement and there are some important points to understand the reasoning.

First, by definition, if you are entering into such an agreement, you are entering into a non-fiduciary relationship. So, any fiduciary requirement wouldn’t apply in this scenario.

Second, if this same question were applied into a scenario of a fiduciary relationship, such as with an RIA, this would be a method of dispute resolution, not a practice method. So, in the event of dispute, the advisor and investor would be free to agree to the method of resolution of their choosing. In this scenario, however, typically the method would not be discussed until the dispute itself arose.

Finally, it is important to know that AIF/AIFA designees are not required to be a fiduciary. It is symbolic of the individuals training, knowledge and ongoing development in fiduciary processes, but does not mean they will always be acting as a fiduciary.

Q. Medical Executive Post 

Don’t the vast majority of arbitration hearings find in favor of the FA; as the arbitrators are insiders, often paid by the very same industry itself?

A. Mr. Aikin

Actual percentages are reported here: http://www.finra.org/ArbitrationMediation/AboutFINRADR/Statistics/index.htm However, brokerage arbitration agreements are a dispute resolution method for disputes that arise within the context of the securities brokerage industry and are not the only means of resolving differences for all types of financial advisors.  Investment advisers, for example, are subject to respond to disputes in a variety of forums including state and federal courts.  Clients should look at their brokerage or advisory agreement to see what they have agreed to. If you wanted to go into further depth on this question, we would recommend contacting Brian Hamburger, who is a lawyer with experience in this area and an AIFA designee. Bio page: http://www.hamburgerlaw.com/attorneys/BSH.htm.

Q. Medical Executive Post 

What about our related Certified Medical Planner® designation, and online educational program for financial advisors and medical management consultants? Is it a good idea – reasonable – for the sponsor to demand fiduciary accountability of these charter-holders? Cleary, this would not only be a strategic competitive advantage, but advance the CMP™ mission to put medical colleagues first and champion their cause www.CertifiedMedicalPlanner.org above all else. 

A. Mr. Aikin

I think it is a good idea for any plan sponsor to demand fiduciary status be acknowledged from anyone engaged to provide comprehensive and continuous investment advice.  I also think it is a good idea to be proactive in verifying that the fiduciary process is being followed.

Q. Medical Executive Post 

Is there anything else that we should know about this topic?

A. Mr. Aikin

Yes, a further note about fi360’s standards. I wrote generically about the fiduciary standard, because there is one that is defined by multiple sources of regulation, legislation and case law.  The process defined in our handbooks, we call a Fiduciary Standard of Excellence, because it covers that minimum standard and also best practice standards that go above and beyond.  All of our Practices, which comprise that standard, are legally substantiated in our Legal Memoranda handbook, which was written by Fred Reish’s law firm, who is considered a leading ERISA attorney.

Additional resources:

Q. Medical Executive Post 

Thank you so much for your knowledge and willingness to frankly share it with the Medical-Executive-Post.

Assessment

All are invited to continue the conversation with Mr. Aikin, asynchronously online, or thru this contact information:

fi360.com
438 Division Street
Sewickley, PA 15143
412-741-8140 Phone
866-390-5080 Toll-free phone
412-741-8142 Fax

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

HOSPITALS: http://www.crcpress.com/product/isbn/9781466558731
CLINICS: http://www.crcpress.com/product/isbn/9781439879900
ADVISORS: www.CertifiedMedicalPlanner.org
BLOG: www.MedicalExecutivePost.com

Product DetailsProduct DetailsProduct Details

Product Details  Product Details

Product DetailsProduct Details

Product Details

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

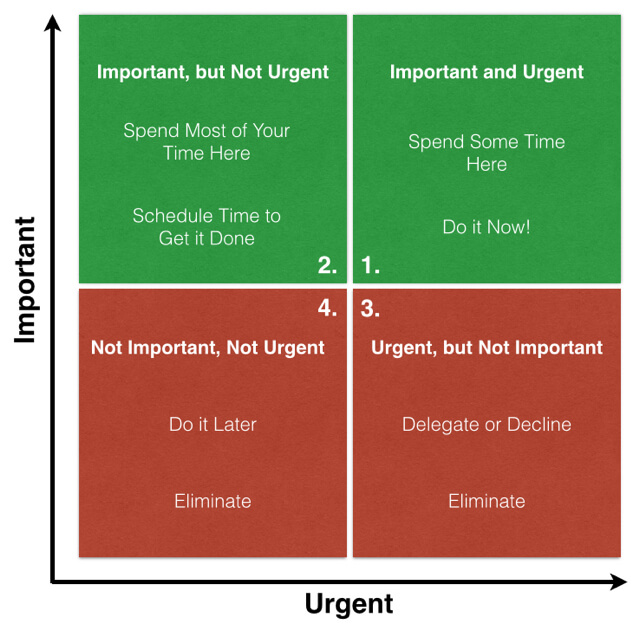
What is the Eisenhower Matrix?

What is the Eisenhower Matrix?

[By staff reporters]

The Eisenhower Matrix is a business management and strategic planning productivity tool that helps to sort tasks and spread them reasonably over time.

The sort out is based on the principals of urgency and importance. When assigned to each task, those two factors place the task to the relevant quadrant of the matrix.

After this routine is done, it’s enough to take a look at the matrix to visually estimate what you should start with.

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Book Marcinko: https://medicalexecutivepost.com/dr-david-marcinkos-bookings/

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, IT, business and policy management ecosystem.

HOSPITALS

***

Product DetailsProduct Details

DAILY UPDATE: Top Causes of Death, Narcan Saves Lives but Scientific Research Fraudulent as DJIA Tops 40,000

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Walgreens has released its own brand of naloxone, a medication that reverses the effects of an opioid overdose. Available online now, Walgreens Brand Naloxone HCl Nasal Spray comes with two doses for $34.99, about $10 cheaper than the name-brand version, Narcan. The over-the-counter medication will also be available in stores by the end of May in the pain aisle, according to a press release, making the life-saving nasal spray more accessible.

***

Here’s where the major benchmarks ended:

  • The S&P 500 index rose 6.17 points (0.1%) to 5,303.27, up 1.5% for the week; the Dow Jones Industrial Average gained 134.21 points (0.3%) to 40,003.59, up 1.2% for the week; the NASDAQ Composite® ($COMP) lost 12.35 points (0.1%) to 16,685.97, up 2.1% for the week.
  • The 10-year Treasury note yield (TNX) rose more than 4 basis points to 4.42%, down about 8 basis points for the week.
  • The CBOE Volatility Index® (VIX) fell 0.43 to 11.99.

Among major companies, Nvidia (NVDA) dropped 2% Friday but still posted a 2.9% advance for the week ahead of the semiconductor leader’s quarterly earnings Wednesday. Among sectors, energy shares led gainers behind a 1% jump in WTI Crude Oil (/CL) futures. The small-cap Russell 2000® Index (RUT) ended little changed but still gained 1.7% for the week.

CITE: https://www.r2library.com/Resource

Fraudulent research papers have cost scientific journal publishers millions in lost revenue. (the Wall Street Journal)

CITE: https://tinyurl.com/2h47urt5

The 10 Top Causes of Adult Death in the U.S.A.

1.  Heart disease 267.2* 2.  Cancer 142.3 3.  Unintentional injuries 64.0 4.  COVID-19 44.5 5.  Stroke 39.5 6.  Chronic lower respiratory disease 34.3 7.  Alzheimer disease 28.9 8.  Diabetes 24.1  9   Kidney disease 13.8 10. Chronic liver disease and cirrhosis 13.8 Deaths per 100,000 population.

Source: Jeffrey Bendix, Medical Economics [5/15/24]

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

SUBMITTED ESSAYS: Economics, Management and Finance from Advisors to Physicians

By Staff Reporters

SPONSOR: http://www.MARCINKOASSOCIATES.com

Finance, economics and management essays of most current interest to all physicians and healthcare professionals

READ ESSAYS: https://marcinkoassociates.com/articles-essays/

Check back periodically for practical updates. Our catalogue library of major books, texts, case models and dictionaries is suggested for additional financial, economic, business and medical practice management information and education.

COMMENTS APPRECIATED

Thank You

***

***

***

PHYSICIANS BEWARE: Traditional Financial Planning “Rules of Thumb”

DOCTORS AND MEDICAL PROFESSIONALS BEWARE?

We ARE Different!

SPONSOR: http://MarcinkoAssociates.com

By Dr. David E. Marcinko MBA CMP®

SPONSOR: http://www.CertifiedMedicalPlanner.org

CMP logo

***

  • While financial planning rules of thumbs are useful to people as general guidelines, they may be too oversimplified in many situations, leading to underestimating or overestimating an individual’s needs. This may be especially true for physicians and many medical professionals. Rules of thumb do not account for specific circumstances or factors occurring at a particular time, or that could change over time, which should be considered for making sound financial decisions.
  • Great Health Industry Resignation: https://medicalexecutivepost.com/2021/12/12/healthcare-industry-hit-with-the-great-resignation-retirement/

For example, in a tight job market, an emergency fund amounting to six months of household expenses does not consider the possibility of extended unemployment. I’ve always suggested 2-3 years for doctors. Venture capitalist lay-offs of physicians during the pandemic confirm this often criticized benchmark opinion of mine.

As another example, buying life insurance based on a multiple of income does not account for the specific needs of the surviving family, which include a mortgage, the need for college funding and an extended survivor income for a non-working spouse. Again a huge home mortgage, or several children or dependents, may be the financial bane of physician colleagues and life insurance.

CITE: https://www.r2library.com/Resource/Title/082610254

***

EXAMPLES: Old/New Rules

  • A home purchase should cost less than an amount equal to two and a half years of your annual income. I think physicians in practice for 3-5 years might go up to 3.5X annual income; ceteras paribus.
  • Save at least 10-15% of your take-home income for retirement. Seek to save 20% or more.
  • Have at least five times your gross salary in life insurance death benefit. Consider 10X this amount in term insurance if young, and/or with several children or other special circumstances.
  • Pay off your highest-interest credit cards first. Agreed.
  • The stock market has a long-term average return of 10%. Agreed, but appreciated risk adjusted rates of return..
  • You should have an emergency fund equal to six months’ worth of household expenses. Doctors should seek 2-3 years.
  • Your age represents the percentage of bonds you should have in your portfolio. Risk tolerance and assets may be more vital.
  • Your age subtracted from 100 represents the percentage of stocks you should have in your portfolio. Risk tolerance and assets may still be more vital.
  • A balanced portfolio is 60% stocks, 40% bonds. With historic low interest rates, cash may be a more flexible alternative than bonds; also avoid most bond mutual funds as they usually never mature.

There are also rules of thumb for determining how much net worth you will need to retire comfortably at a normal retirement age. Here is the calculation that Investopedia uses to determine your net worth:

Compensation in the Physician Specialties: Mostly Stable - NEJM  CareerCenter Resources

RULES 72, 78 and 115: https://medicalexecutivepost.com/2022/01/30/the-rules-of-72-78-and-115/

INVITATION: https://medicalexecutivepost.com/2021/05/08/invite-dr-marcinko-to-your-next-big-event/

***

COMMENTS ARE APPRECIATED

Thank You

Subscribe to the Medical Executive-Post

***

FINANCE: https://www.amazon.com/Comprehensive-Financial-Planning-Strategies-Advisors/dp/1482240289/ref=sr_1_1?ie=UTF8&qid=1418580820&sr=8-1&keywords=david+marcinko

***

DAILY UPDATE: Core CPI and ERISA while Markets Remain High with Walmart Up

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Here’s where the major benchmarks ended:

America’s oldest popular stock index, the Dow Jones Industrial Average, hit a brief record high yesterday morning when it traded above 40,000, reflecting renewed hope for the market’s health after Wednesday’s promising inflation report.

  • The S&P 500® index (SPX) fell 11.05 points (0.2%) to 5,297.10; the Dow Jones Industrial Average declined 38.62 points (0.1%) to 39,869.38; the NASDAQ Composite® ($COMP) shed 44.07 points (0.3%) to 16,698.32.
  • The 10-year Treasury note yield (TNX) rose more than 2 basis points to 4.381%.
  • The CBOE Volatility Index® (VIX) dropped 0.03 to 12.42.

Walmart’s strength fueled a strong day for consumer staples shares. The S&P 500 Consumer Staples ($SP500#30), which includes Walmart as well as companies like Coca-Cola (KO) and Procter & Gamble (PG), surged 1.5% to its highest level in over two years. 

Among other companies, Applied Materials (AMAT) fell 1.6% ahead of the semiconductor industry supplier’s quarterly earnings report, which is expected after Thursday’s close.

CITE: https://www.r2library.com/Resource

And, Core CPI, which tracks the price of goods and services excluding volatile food and energy prices and is closely watched as an inflation indicator, rose 3.6% from the same period last year. That’s the smallest annual increase since April 2021. On a monthly basis, core CPI rose 0.3%, marking the first time in six months that its growth slowed from the prior month. Other good signs include:

  • Grocery prices dropped 0.2% from March, the first decrease in a year.
  • Health insurance and car insurance increased more slowly in April than in March.
  • A separate report released yesterday showed consumer spending stayed steady last month.

CITE: https://tinyurl.com/2h47urt5

Finally, Joe Manchin (D-W.Va.) and a group of Republican senators are moving to overturn a retirement investment planning rule that was finalized by the Labor Department last month. The Labor Department unveiled the new rule last month that would update the definition of an investment advice fiduciary under the Employee Retirement Income Security Act. Manchin and 15 Republican senators joined in co-sponsoring a Congressional Review Act (CRA) resolution that would overturn this new rule.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

REIMBURSEMENT: Valuation of Accountable Care Organizations

By Health Capital Consultants, LLC

***


Valuation of Accountable Care Organizations: Reimbursement

The U.S. healthcare payment and delivery system is increasingly moving to a value- and quality-based system. Accountable care organizations (ACOs) are at the forefront of delivering high-quality and cost-effective care to millions of Medicare beneficiaries and privately insured patients, incentivized by substantial shared savings for those who increase quality while containing costs.

CITE: https://www.r2library.com/Resource

This third installment of a five-part series on the valuation of ACOs will discuss the reimbursement environment in which ACOs participate.(Read more…) 

COMMENTS APPRECIATED

Thank You

***

***

***

HOSPITALS: https://www.amazon.com/Financial-Management-Strategies-Healthcare-Organizations/dp/1466558733/ref=sr_1_3?ie=UTF8&qid=1380743521&sr=8-3&keywords=david+marcinko
***

DAILY UPDATE: Healthcare Monopolies, Ark Invest and the Stock Markets Mega Rally

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

More people are interested in determining their “heart age” using new tests and tech tools, but some skeptics say it’s not a healthy data point to focus on. (the Wall Street Journal)

CITE: https://www.r2library.com/Resource

The Cathie Wood-led Ark Invest just made some significant trades. The most prominent among them were the increased stakes in Palantir Technologies Inc (NYSE:PLTR) and the reduced holdings in Coinbase Global Inc (NASDAQ: COIN).

Here’s where the major benchmarks ended:

  • The S&P 500 index rose 61.47 points (1.2%) to 5,308.15; the Dow Jones Industrial Average added 349.89 points (0.9%) to 39,908.00; the NASDAQ Composite rallied 231.21 points (1.4%) to 16,742.39.
  • The 10-year Treasury note yield fell almost 10 basis points to 4.348%.
  • The CBOE Volatility Index® (VIX) dropped 0.97 to 12.45.

Chipmaker shares led the way higher Wednesday, lifting the Philadelphia Semiconductor Index (SOX) almost 3% to a 10-week high. Interest-rate-sensitive sectors like real estate and utilities were also strong. The small-cap Russell 2000® Index (RUT) advanced 1.1% to a seven-week high. The U.S. Dollar Index ($DXY) slumped to its weakest level in five weeks, reflecting expectations for lower interest rates that may reduce the appeal of U.S. fixed income assets.

Among companies, Cisco Systems (CSC) surged 1.5% ahead of its quarterly results expected after Wednesday’s close. Dow member Walmart (WMT) is expected to release results Thursday morning as the unofficial retail earnings season accelerates. 

CITE: https://tinyurl.com/2h47urt5

And … The U.S. Department of Justice (DOJ) announced it has established a new task force to take on healthcare monopolies and collusion. The task force, made up of prosecutors, economists, healthcare industry experts and others, will guide the division’s enforcement strategy and policy approach in healthcare, including by facilitating policy advocacy, investigations and, where warranted, civil and criminal enforcement in healthcare markets.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

CUSTOMIZABLE e-PODIATRY CONSENT FORMS Now Available for 2024

Electronically CUSTOMIZABLE FOR EVERY FOOT / ANKLE / LEG SURGEON

***

http://www.ePodiatryConsentForms.com

CUSTOMIZABLE CMS & AGENCY FOR HEALTHCARE RESEARCH AND QUALITY STYLED PROTOCOLS, CHECKLISTS AND TEMPLATES

.… Specifically for Podiatrists ….   

e-Podiatry Consent Forms™ is an innovative new suite of software programs from the Institute of Medical Business Advisors [iMBA, Inc]. Our products solve your informed consent problems and enhance the education, discussion and documentation of the informed consent process for all podiatrists performing foot, ankle and leg reconstructive surgical procedures.

THE PROBLEM

All podiatrists are being pressured by the Centers for Medicare and Medicaid Services [CMS], the Joint Commission on Accreditation of Healthcare Organizations [JCAHO], liability carriers and private insurance payers to make their consent process more patient-friendly, informed and easily understood. And, the pressure to standardize and comply is great.

Most recently, based on the need to make healthcare even safer, the Agency for Healthcare Research and Quality (AHRQ) undertook a major study to identify patient safety issues and develop recommendations for “best practices”.

The AHRQ Evidence Report

The AHRQ report identified the challenge of addressing shortcomings such as missed, incomplete or not fully comprehended informed consent, as a significant patient safety issue and opportunity for improvement.

The authors of the AHRQ report hypothesized that better informed patients:

“are less likely to experience errors by acting as another layer of protection.”

And, the AHRQ study ranked a “more interactive informed consent process” among the top 11 practices supporting more widespread implementation; especially for surgical consent forms.

THE SOLUTION

Why Us: https://epodiatryconsentforms.com/why-us/

One answer to the modern risk-management problem of “informed consent interactivity” may be e-Podiatry Consent Forms™  We license two core interactive surgical products, and a reference library, with related concepts and products in development:

  • Forefoot, Mid-Foot and Simple Rear-Foot Version
  • Complex Rear-Foot, Ankle and Lower Leg Version
  • Comprehensive content library for extreme customization.

Each e-Podiatry Consent Forms™ CD-ROM [secure email delivery is now available] is increasingly trusted as the simple solution to standardized communications across the entire office-enterprise; from managing-risk, informing-patients and complying with modern regulatory requirements through enhanced patient-centric informed consent encounters.

Thus, by improving the consistency, details, documentation and effectiveness of the informed consent process, e-Podiatry Consent Forms™ equips all podiatric surgeons with the tools needed to augment quality standards, reduce litigation potential and improve patient outcomes and safety.

http://www.ePodiatryConsentForms.com

***

ORDER NOW: MarcinkoAdvisors@msn.com

DELIVERY: By email only

***

PODIATRY PREP: Pass All Your Board Certification Examinations in 2024

Celebrating 30 Years of Your Success!

***

Engineers at MIT want to optimize your jog. Some of the brightest minds in math and science have created a predictive model that can tell you what kind of shoe you would run best in. The model assesses a person’s height, weight, and leg length to simulate their gait in sneakers of different materials and mid-soles. It then projects the optimal shoe based on which one produces the most efficient running form (i.e., which uses as little energy as possible per stride).

And so, as 3D printing and related tech continue to drive sneaker innovation, the researchers say their model will be beneficial to designers who want to create new kinds of highly functional kicks (Adidas funded some of the research).

Why? Marketing and product sales, of course. But, some experts suggest improved shoes might increase your running away speed by 8-10% while reducing injuries.

***

pod_prep_text

Pass ALL the Certification Boards!

By: http://www.PodiatryPrep.org

The Foot and Ankle Research Consortium, Inc. (FARC) is the leading publisher of Podiatric educational software. Since 1992, we have been producing the most effective and innovative method of preparing for ALL the Podiatry Board Examinations.

CURIOUS STUDY: Hallux Valgus Met I

SCARF: scarf osteotomy

This includes: The American Board of Podiatric Surgery, The American Board Of Podiatric Orthopedics and Primary Podiatric Medicine, the American Podiatric Medical Specialties Board, ABLES and the PMLexis. (Now includes the latest information for all Board Re-Certifications).

CONTENTS: https://podiatryprep.org/compatibility-test/

Customization and private  tutoring services also available.

FAN CLUB: https://podiatryprep.org/podiatryprep-fan-club/

doctor_pass2

PURCHASE – PREPARE – PASS®

ORDER HERE: https://podiatryprep.org/order-form/

GOOD LUCK!

Thank You

BUSINESS: https://www.amazon.com/Business-Medical-Practice-Transformational-Doctors/dp/0826105750/ref=sr_1_9?ie=UTF8&qid=1448163039&sr=8-9&keywords=david+marcinko

***

CAN: Doctor-Patient Intimacy be Electronic?

e Communication Tales from the Treatment Room

dem-2

By Dr. David Edward Marcinko MBA MEd CMP®

www.CertifiedMedicalPlanner.org

Today’s electronic media makes physician-patient communication possible; yet there is another kind of intimacy. ICTs—information and communication technologies—enable 24/7 monitoring of basic information such as blood pressure, glucose levels, pulse, and respiration, etc.

Example:

In one study, an ICT not only made it easier for patients to stay in touch with their doctors, the outcomes were also significantly better.[i] Today, Hippocrates is no longer trailing patients around the house to keep track of their snacks and moods. But Hippocrates has gone digital in the form of a wearable device that records subtle changes in biological markers and communicates them instantaneously to a health provider.

While this is obviously a great advance, we suggest you pause for a moment before plugging in.

Why?

ICTs and social media tools can make a difference to one of the most important dimensions—physiological outcomes. But you can have the latest interactive technology at your disposal and still fail to be connected.

Example:

A story that a friend told me shows how.

***

One morning, her elderly father was touching up the paint on his sailboat. Nearby, another boat-owner, who happened to be an emergency medical technician, noticed her father was struggling to breathe and that his lips had turned purple. A trip to the local community hospital led to a barrage of high-tech tests and procedures, a diagnosis of emphysema, later complications with cerebral hematomas, and hospitalizations and re-hospitalizations that brought him into contact with a neurologist, a neurosurgeon, a cardiologist, and a pulmonologist.

Throughout her father’s medical ordeal, the team of specialists stayed in touch with each other and the primary care physician via various electronic media. But one person remained out of the loop—her father. One day, six months into the experience, the primary care physician phoned our friend’s mother to check on his patient. Her father recalls thinking, “Why was he calling her?”

The physician was communicating, but he was emotionally disconnected.

***

The Moral

The moral of the story: communication needs to be patient-centered in both electronic and psychological terms. That means understanding how someone likes to communicate and making sure the medium fits the message. Electronic media are just part of the equation. The other is the doctor-patient relationship. Once a relationship is established, it may be fine to use e-mail to send information about dosage.

But, delivering a new diagnosis may require the extra effort of scheduling a phone call or a face-to-face visit. Today, since you have so many Health 2.0 choices, it takes some effort to select the right way to communicate in a particular situation.

Use the Right Relationship Strategy

A colleague recently shared another story about an encounter with a specialist.

Example:

***

After an examination for a minor ailment, he was told that there might be a medicated lotion that could ameliorate his condition. The doctor thought for a moment, then swiveled around to the computer on his desk. As our colleague watched the screen, his physician typed a few words into a search engine. Up popped a list and he wrote out a script. “Try this,” his doctor concluded. “I think it will help.”

It did, almost overnight.

***

The Moral

Even though his physical problem had disappeared completely, our colleague felt there was something missing in the interaction. “It bothered me that my doctor turned to the Web for help at that moment. He found a cure, but I felt he wasn’t paying attention to me.”

The physician is supposed to be an authority who has a special relationship to the patient. “Anybody can Google,” our colleague complained. Was he being unreasonable? Maybe.

But; this story tells us something important about technology—it cuts both ways.

***

aahnofx

***

Assessment

Everyone has their own preferences when it comes to how they want to interact with each other and with technology. If these preferences are explicit and aligned, the chances for a productive partnership are high. The preferences, however, are many and complex. You can easily get lost in the tangled thicket of interpersonal styles and virtual mediums.

In the Web 2.0 environment, it helps to narrow down the endless choices to just a few options.

MORE: Is Text Messaging being Overlooked as an Engagement Tool in Healthcare?

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[i] Hanson, William M. The Edge of Medicine: The Technology That Will Change Our Lives. New York, NY: Palgrave Macmillan, 2008.

Product DetailsProduct Details

***

DAILY UPDATE: Squarespace, Ark Invest & Hospitals as the Markets Rebound

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Here’s where the major benchmarks ended:

  • The S&P 500® index (SPX) rose 25.26 points (0.5%) to 5,246.68, the highest since a record close March 28; the Dow Jones Industrial Average® ($DJI) gained 126.60 points (0.3%) to 39,558.11; the NASDAQ Composite climbed 122.94 points (0.8%) to 16,511.18.
  • The 10-year Treasury note yield (TNX) fell more than 3 basis points to 4.449%.
  • The CBOE Volatility Index® (VIX) decreased 0.18 to  13.42.

Among companies, Home Depot’s (HD) quarterly results reported earlier Tuesday kicked off the unofficial start of the retail earnings season. The home improvement retailer’s earnings topped expectations, but revenue missed forecasts, initially sending the company’s shares down sharply. 

Home Depot also reaffirmed its full-year guidance for a 1% decline in comparable-store sales and a 1% increase in total sales. The company’s shares bounced back to end with a 0.1% loss.

CITE: https://www.r2library.com/Resource

And, the Cathie Wood-led Ark Invest just made some significant trades. The most prominent among them were the increased stakes in Palantir Technologies Inc (NYSE PLTR) and the reduced holdings in Coinbase Global Inc (NASDAQ: COIN).

Moreover, the website-building platform Squarespace is to go private, which it announced it’ll be doing in an all-cash deal with Permira, a private equity firm. Squarespace, which was public for nearly three years, joins a group of other smaller tech companies like Qualtrics that have recently pulled themselves off the public market. (CNBC)

CITE: https://tinyurl.com/2h47urt5

Employers and private insurers are paying hospitals more for inpatient and outpatient services than in previous years, a study from RAND Corporation finds. The American Hospital Association dismissed the report saying it offers a “skewed and incomplete picture.”


And finally … Kaiser Permanente began its 2024 earnings season with more than $2.7 billion in net income and $935 million in operating income, just months after sharing plans to lay off workers.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

Physician Electronic-Mail Bills

“MY CHART”

By AMANDA SEITZ

***

***

E-Mailing your Physician may Cost You like Your Attorneys!

***

WASHINGTON (AP) — The next time you message your doctor to ask about a pesky cough or an itchy rash, you may want to check your bank account first — you could get a bill for the question.

Hospital systems around the country are rolling out fees for some messages that patients send to physicians, who they say are spending an increasing amount of time poring over online queries, some so complex that they require the level of medical expertise normally dispensed during an office visit. Patient advocates, however, worry these new fees may deter people from reaching out to their doctor and that they add another layer of complexity to the U.S. health care system’s already opaque billing process.

“This is a barrier that denies access and will result in hesitancy or fear to communicate and potentially harm patients with lower quality of care and outcomes at a much higher cost,” said Cynthia Fisher, the founder of Patient Rights Advocate, a Massachusetts-based nonprofit that pushes for hospital price transparency.

CITE: https://www.r2library.com/Resource/Title/082610254

The explosion of telehealth over the last three years — driven by the COVID-19 outbreak and relaxed federal regulations for online care — prompted many doctors to adopt more robust telecommunication with their patients. Consultations that once happened in an office were converted to computer or smart phone visits. And health care systems invited patients to use new online portals to message their doctors with a question at any time, American Medical Association president Jack Resneck Jr. told The Associated Press.

“When people figured out this is cool and could improve care, you saw hospitals and practice groups saying to patients, welcome to your portal … you can ping your physician with questions if you want,” Resneck said. “We found ourselves as physicians getting dozens and dozens of these a day and not having time built in to do that work.”

The charges vary for each patient and hospital system, with messages costing as little as $3 for Medicare patients to as much $160 for the uninsured. In some cases, the final bill depends on how much time the doctor spends responding.

READ HERE: https://my.clevelandclinic.org/online-services/mychart/messaging#msdynttrid=bAU8cKe-602S6wFIwSYop1KQswRcT2b2F5mRJ-92OEc

***

COMMENTS APPRECIATED

Thank You

***

ORDER: https://www.amazon.com/Dictionary-Health-Information-Technology-Security/dp/0826149952/ref=sr_1_5?ie=UTF8&s=books&qid=1254413315&sr=1-5

***

ORDER: https://www.amazon.com/Dictionary-Health-Insurance-Managed-Care/dp/0826149944/ref=sr_1_4?ie=UTF8&s=books&qid=1275315485&sr=1-4

***

PODCAST: Hospital Price Transparency Website

BILLY EATS MEDICAL BILLS

By Eric Bricker MD

***

***

COMMENTS APPRECIATED

Thank You

***

***

***

PODCAST: Early Retirement and Health Insurance

By Staff Reporters

***

***

COMMENTS APPRECIATED

Thank You

***

ORDER: https://www.amazon.com/Dictionary-Health-Insurance-Managed-Care/dp/0826149944/ref=sr_1_4?ie=UTF8&s=books&qid=1275315485&sr=1-4

***

DAILY UPDATE: Moderna Down with Mixed Markets

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 20224

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Here’s where the major benchmarks ended:

  • The S&P 500® index (SPX) fell 1.26 points (0.02%) to 5,221.42; the Dow Jones Industrial Average lost 81.33 points (0.2%) to 39,431.51; the NASDAQ Composite® ($COMP) gained 47.37 points (0.3%) to 16,388.24.
  • The 10-year Treasury note yield (TNX) dropped almost 2 basis points to 4.487%.
  • The CBOE Volatility Index® (VIX) surged 1.05 to 13.60.

Biotechnology and food and beverage shares were among the market’s strongest sectors Monday, while communication services stocks were among the biggest laggards. Energy shares took pressure despite a jump of 1.2% in WTI Crude Oil (/CL) futures, which ended above $79 per barrel after slumping last week to two-month lows.

CITE: https://www.r2library.com/Resource

Moderna is “bleeding money” as its forthcoming RSV vaccine doesn’t appear to deliver better results than other RSV shots already on the market. (Bloomberg)

***

It’s ChatGPT-4o’s time to shine. The “o” stands for omni, and it’s the latest iteration of OpenAI’s signature chatbot. According to the company, it’s much faster with enhanced “capabilities across text, vision, and audio.”

CITE: https://tinyurl.com/2h47urt5

23% is the average portion of the bill hospitals collected from patients before treatment in Q1 of this year, up 3% YoY. (the Wall Street Journal)

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

REVIEW: Style-Based Stock Portfolio Performance Evaluations

Stock or Manager Relevance Comparisons and Philosophy

By Dr. David Edward Marcinko MBA, MEd, CMP™

SPONSOR: http://www.CertifiedMedicalPlanner.org

[Publisher-in-Chief]

One relatively recent performance evaluation approach that was developed to help improve the relevance of comparisons is the separation of stock universes and managers by style. This classification method attempts to distinguish between stocks or manager philosophies based upon general financial characteristics of the investments.

The Managers

In very general terms, a manager is often a growth manager if the investment approach that the manager uses focuses on stocks showing growth and momentum in its earnings and price.

A value manager is generally considered to be a manager that attempts to identify under-valued securities based upon fundamental analysis of the company.  A stock may be considered either “growth” or “value” based on a given set of valuation measures such as price-to-earnings, price-to-book value, and dividend yield.

The Style

The goal of style-based performance comparisons is to take some of the biases of the market environment out of the comparison, since a portfolio’s returns will ideally be evaluated versus a universe of alternatives that represent similar investment characteristics facing the same basic market environment.  Thus, if the environment is one in which investors in stocks with strong past earnings and price momentum have generally performed better than those using fundamental analysis to find under-valued stocks, comparing the growth/momentum portfolio to a growth index or universe should help eliminate the bias.

Style-based universes can help the medical professional better understand the basic environment captured over a given performance time period.

However, there are significant limitations with the various approaches to constructing style-based stock and manager universes that should be understood if they are to be used in direct performance comparisons.  Taking style-based stock universes separately from style-based manager universe, one of the most significant issues regarding the categorization of stocks by “growth” and “value” styles is the lack of agreement in the specification of what a growth stock is versus a value stock.  With some universes divided by price-to-book value, others by price-to-earnings and/or dividend yields and some by combinations of similar variables, stocks are often classified very differently by two different stock universes.  Further, stocks move across a broad spectrum as their price and fundamentals change, resulting in stocks constantly moving between growth and value categories for any given universe.  If there is ambiguity in the rating of a given stock, then the difficulty is only compounded when we attempt to boil what may be complex investment processes of an investment manager or mutual fund portfolio manager to a simple classification of growth or value.  A beaten down cyclical stock that no self-respecting growth/momentum manager would purchase may be classified as “growth” because it has a high price-to-earnings ratio (i.e., from low earnings) or a high price-to-book value (i.e., from asset write-offs).  Value managers are not the only ones to own low valuation stocks that have improving earnings.

***

***

The second problem with style categorization is that managers are often misclassified or they purposefully “game” the categorization of their own process in order to appear more competitive.  As an example, if a manager that typically looks for relatively strong earnings/price momentum is lagging in a period when “growth” managers are outperforming, the rank of the manager can be improved simply by claiming a “value” approach.  Morningstar’s “style box” classification of mutual funds by size and style of the current portfolio highlight this problem for any given fund by showing how their portfolio has changed its classification annually.

Current Events

The stock market has been booming lately. Up almost 100% since March 2009, after being down almost 50%. And so, perhaps this is a good time to re-evaluate the performance of your investment portfolio[s].

Assessment

However, this leads to an interesting question for the medical professional or his/her advisor: If a manager is still using the same basic investment philosophy and disciplines, but their “style” category has changed according to the ratings service, should you fire them?  If the answer is “yes”, then the burden of monitoring and the cost of manager turnover are an inevitable part of narrow style based performance comparisons.

But, if the answer is “no,” then it is easy to see the difficulty of fitting every management approach into a simple style box.  The more reasonable alternative is to use style-based stock and manager universes as a tool for understanding the environment, rather than an absolute performance benchmark.

Conclusion

And so, your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

Our Other Print Books and Related Information Sources:

Subscribe Now: Did you like this Medical Executive-Post, or find it helpful, interesting and informative? Want to get the latest ME-Ps delivered to your email box each morning? Just subscribe using the link below. You can unsubscribe at any time. Security is assured.

Sponsors Welcomed: And, credible sponsors and like-minded advertisers are always welcomed.

***

Product DetailsProduct DetailsProduct Details

  ***

About Tombstone Securities Advertising and the “New Issue” Propsectus

SPONSOR: http://www.CertifiedMedicalPlanner.org

A Primer for Physician Investors and Medical Professionals

By: Dr. David Edward Marcinko; MBA, MEd, CMP™

[Editor-in-Chief]

[PART 2 OF 8]

BU Dr. Marcinko

NOTE: This is an eight part ME-P series based on a weekend lecture I gave more than a decade ago to an interested group of graduate, business and medical school students. The material is a bit dated and some facts and specifics may have changed since then. But, the overall thought-leadership information of the essay remains interesting and informative. We trust you will enjoy it.

Introduction

Despite the SEC restrictions, noted in Part I of this series, some idea of potential demand for a new security issue can be gauged and have a bearing on  pricing decisions.

For example, as CEO of a medical instrument company, or interested investor, would you rather see a great deal of interest in a potential new issue or not very much interest?  There is however, one kind of advertisement that the underwriter can publish during the cooling off period. It’s known as a tombstone ad.  The ad makes it clear that it is only an announcement and does not constitute an offer to sell or  solicit the issue, and that such an offering can only be made by  prospectus.  SEC Rule 134 of the 1933 Act  itself, refers to a tombstone ad as “communication not deemed a prospectus”  because it makes reference to the prospectus in the ad. Tombstones have received their name because of the sparse nature of details found in them.

However, the most popular use of the tombstone ad is to announce the effectiveness of a new issue, after it has been successfully issued. This promotes the success of  both he underwriter, as well as the company.

Since distributing securities involves potential liability to the investment bank, it will do everything possible to protect itself.  So, near the end of the cooling off period, a meeting is held between the underwriter and the corporation. It is known as a due diligence meeting. At this meeting they both discuss amendments that are going to be necessary to make the registration statement complete and accurate. The corporate officers, and the underwriters sign, the final registration statement. They have civil liability for damages that result from omissions of material facts or

Mis-statements of fact. They also have criminal liability if the distribution is done by use of fraudulent, manipulative, or deceptive means. Due diligence takes on a whole new meaning when  incarceration from a half-hearted effort underwriting efforts can occur. The investment bank strives to ensure that there have been no material changes to the issuer or the terms of the issue since the registration statement was filed.

Again, as a physician, how would you feel if you were an investment banker raising capital for a new pharmaceutical company that had developed a drug product that was highly marketable. But, on the day after the issue was effective, there was a major news story indicating that the company was being sued for patent infringement? What effect do you think that would have on the market price of this new issue? It would probably plunge. How could this situation have been prevented? The due diligence meeting is more than a cocktail party or a gathering in a smoke filled room. Otherwise, the company would require specially trained people, to do a patent search lessening the likelihood of this scenario. At the due diligence meeting, work is done on the preparation of the final prospectus, but the investment bank does not set the public offering price or the effective date at this meeting. The SEC will eventually set the effective date for the registration and it is on that date that the final offering price will be determined.

Once the SEC sets the effective date, sales may be executed and money can be accepted by the investment bank. It is at this time that the final prospectus, similar to the red herring but without the red ink and with the missing numbers, is issued. A prospectus is an abbreviated form of the registration statement, distributed to purchasers, on and after the effective date of  the registration. It is not the same as the registration statement. A typical registration statement consists of papers that stand more than a foot high; rarely does a prospectus go beyond 40 or 50 pages. All purchasers will receive a final prospectus and then it becomes permissible for the underwriter to provide sales literature.

In addition to the requirement that a prospectus must be delivered to a purchaser of new issues no later than with confirmation of the trade, there are two other requirements that healthcare executives investors should know.

90-day: When an issuer has an initial public offering (IPO), there is generally a lack of publicly available material relating to the operations of that issuer.  Because of this, the SEC requires that all members of the underwriting group make available a prospectus on an IPO for a period of 90 days after the effective date.

4O-day: Once an issuer has gone public, there are a number of routine filings that must be made with the SEC so there is publicly available information regarding the financial condition of that issuer. Since additional information is now available, the SEC requires that, on all issues other than IPOs, any member of the underwriting group must make available a prospectus for a period of 40 days after the effective date.

In the event that the investment bankers misgauged the marketplace, and the issue moves quite slowly, it is possible that information contained in the prospectus would be rendered obsolete by the SEC. Specifically, the SEC requires that any prospectus used more than 9 months after the effective date, may not have any financial information more than 16 months old. It can however, be amended or stickered, with updated information, as needed.

###

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

###

Syndication Among Underwriters

Because the investment banking firm may be underwriting (distributing) a rather large dollar amount of securities, to spread its risk exposure, it may form a group made up of other investment bankers or underwriters, known as a syndicate. The syndicate is headed by a syndicate manager, or lead underwriter, and it is his job to decide whether to participate in the offering. If so, the managing underwriter will sign a non-binding agreement called a letter of intent. .

If all has gone well and the market place is sufficiently interested in the security, and the SEC has been satisfied with respect to the registration statement, it is time for all parties to the offering to formalize their relationships with a contract including the basic understandings reflected in the letter of intent. Three principal underwriting contracts are involved in the usual public offering, each serving a distinct purpose. These are the: Agreement among Underwriters, Underwriting Agreement, and the Dealer Agreement.

In the Agreement Among Underwriters (AAU), the underwriters committing to a portion of the issue, enter into an agreement establishing the nature and terms of their relationship with each other. It designates the syndicate manager to act on their behalf, particularly to enter into an Underwriting Agreement with the issuer, and to conduct the offering on behalf of each  of them. The AAU will designate the managing underwriter’s compensation (management fee) for managing the offering.

The authority to manage the offering includes the authority to: agree with the issuer as to the public offering price; decide when to commence the offering; modify the offering price and selling commission; control all advertising; and, control the timing and effectiveness of the registration statement by quickly responding to deficiency letters. Each underwriter agrees to purchase a portion of the underwritten securities, which is known as each under-writer’s allotment (allocation).  It is normally signed severally, but not jointly, meaning each underwriter is obligated to sell his allocation but bears no financial obligation for any unsold allotment of another underwriter. This is referred to as a divided account or a Western account. Much less frequently, an undivided or Eastern account, will be used. Each underwriter is responsible for unsold allotments of others, based upon a  proportionate share of the offering.

The above comments referred to firm commitment underwriting. Another type of underwriting commitment  however, is known as best efforts underwriting. Under the terms of  best efforts underwriting, the underwriters make no commitment to buy or sell the issue, they simply do the best they can, acting as an agent for the issuer, and having no liability to the issuer if none of the securities are sold. There is no syndicate formed with a best efforts underwriting. The investment bankers form a selling group, with each member doing his best to sell his allotment. Two variations of a best efforts underwriting are: the all-or-none, and the mini-max (part-or-none) underwriting. Under the provisions of an all-or-none offering, unless all of the shares can be distributed within a specified period of time, the offering will terminate and no subscriptions or orders will be accepted or filled. Under mini-max, unless a set minimum amount is sold, the offering will be terminated.

SEC Rule 15c2-4 requires the underwriter to set up an escrow account for any money received before the closing date, in the event that it is necessary to return the money to prospective purchasers. If the “minimum”, or the “all” contingencies are met, the monies in escrow go to the issuer with the underwriters retaining their appropriate compensation. In order to make sure that investors are properly protected, the escrow account must be maintained at a bank for the benefit of the investors until every appropriate event or contingency has occurred. Then, the funds are properly returned to the investors. If the money is to be placed into an interest bearing account, it must have a maturity date no later than the closing date of the offering, or the account must be redeemable at face with no prepayment penalty as regards principal.

Underwriter Compensation Hierarchy

As we have seen, in a firm commitment the underwriter buys the entire issue from the issuer and then attempts to resell it to the public. The price at which the syndicate offers the securities to the public is known as the public offering price. It is the price printed on the front page of the prospectus.

However, the managing underwriter pays the issuer a lower price than this for the securities. The difference between that lower price and the public offering price is known as the spread or underwriting discount. Everyone involved in the sale of a new issue is compensated by receiving part of the spread. The amount of the spread is the subject of negotiations between the issuer and the managing underwriter, but usually is within a range established by similar transactions between comparable issuers and underwriters. The spread is also subject to NASD [now FINRA] review and approval before sales may commence. The spread is broken down by the underwriters so that a portion of it is paid to the managing underwriter for finding and packaging the issue and managing the offering (usually called the manager’s fee); and a portion is retained by each underwriter (called the underwriting or syndicate allowance) to compensate the syndicate members for their expenses, use of money, and assuming the risk of the underwriting. The remaining portion is allocated to the selling group and is called selling concession. It is often useful to remember the compensation hierarchy pecking order in the following way:

  • Spread (syndicate manager).
  • Underwriters allowance (syndicate members)
  • Selling concession (selling group members)
  • Re-allowance (any other firm)

While the above deal with corporate equity, the only other significant item with respect to corporate debt is the Trust Indenture Act of 1939. This Federal law applies to public issues of debt securities in excess of $5,000,000. The thrust of this act is to require an indenture with an independent trustee (usually a bank or trust company) who will report to the holders of the debt securities on a regular basis.

Successful marketing of a new issue is a marriage between somewhat alien factors: compliance and numerous Federal, state, and self-regulatory rules and statutes; along with finely honed and profit-motivated sales techniques. It’s not too hard to see that there could be a real, or apparent, conflict of interest here. Most successful investment bankers have built their excellent reputations upon their ability to properly balance these two objectives consistently, year after year.

PART ONE:

Understanding investment banking rules, securities markets, brokerage accounts, margin and debt

Channel Surfing the ME-P

Have you visited our other topic channels? Established to facilitate idea exchange and link our community together, the value of these topics is dependent upon your input. Please take a minute to visit. And, to prevent that annoying spam, we ask that you register. It is fast, free and secure.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct DetailsProduct Details

Product Details  Product Details

Product DetailsProduct Details

Product Details

Invite Dr. Marcinko

***

DAILY UPDATE: Ark Invest, Dell and “Buy Now-Pay Later”

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved, USA. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

While Buy Now-Pay Later (BNPL) reduces friction when purchasing, it’s giving some economy watchers unease. As Americans’ budgets buckle under the weight of inflation and higher interest payments, some worry BNPL is more of an invisible burden than a boon, Bloomberg reports. Beware the “phantom debt,” a Wells Fargo economist recently warned, referring to the BNPL industry’s short-term loans, which go largely unaccounted for by those tracking Americans’ debt load. That’s because, unlike credit cards and auto loan providers, Afterpay, Affirm, Klarna, and other BNPL providers don’t usually report transactions to credit scoring agencies.

CITE: https://www.r2library.com/Resource

The Cathie Wood-led Ark Invest just made some significant trades. The most prominent among them were the increased stakes in Palantir Technologies Inc (NYSE: PLTR) and her reduced holdings in Coinbase Global Inc (NASDAQ: COIN).

CITE: https://tinyurl.com/2h47urt5

Dell has recently seen a decline in its revenue. In its most recent earnings report, it revealed that its net revenue shrunk by 11% year-over-year during its fiscal 2024 fourth quarter. For full year 2023, the company’s revenue was down by 14% to $88.4 billion. Partly that was due to a weak personal-computer market and the costs associated with more than 6,000 layoffs. But investors are excited by Dell’s growth potential for its server and computer businesses because of artificial intelligence, the Motley Fool reported.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

VENTURE CAPITAL: Women’s Health Start-Ups

By Staff Reporters

***

***

Women’s health startups are still closing multi million-dollar funding deals despite a challenging venture capital (VC) landscape in which VC dollars are on track to fall by 73% this year compared to last.

CITE: https://www.r2library.com/Resource

For example, in the last year, virtual maternity care program Pomelo Care raised $33 million in seed and Series A rounds led by Andreessen Horowitz; Caraway Health, a digital mental, physical, and reproductive health services platform, raised almost $17 million in a Series A round led by Maveron and GV (formerly Google Ventures); and Intrinsic, which acquires brands that make women’s health products, announced a $15 million equity fund raise (which is when a company raises money by selling its shares).

***

***

COMMENTS APPRECIATED

Subscribe Today!

Thank You

***

***

DAILY UPDATE: National Nurses Week, Multiplan Lawsuit, Rite Aid and Fatburger Down

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

HAPPY MOTHER’S DAY 2024

Fat Brands is the parent company of Fatburger, Johnny Rockets, and a few other restaurant chains. Last year, former CEO Andy Wiederhorn stepped down after the Los Angeles Times reported that the federal government was investigating him for fraud. He has since stayed on as the company’s chairman, but on Friday the Justice Department charged him with perpetuating a $47 million fraud against his own shareholders.

CITE: https://www.r2library.com/Resource

In a recent Becker’s Health Care Newsletter, it is reported that a large multi-state hospital system is suing Multiplan for illegal price fixing and automatic significant price reductions, in particular, for out-of-network providers. The story states that Multiplan, by bombarding healthcare providers with automatic reductions in pricing, has made it impossible for providers to deliver healthcare.

CITE: https://tinyurl.com/2h47urt5

National Nurses Week, which ends today on May 12th, Florence Nightingale’s birthday

Rite Aid has announced that 39 stores are set to close their doors for good, this follows the decision to declare Chapter 11 bankruptcy back in October, 2023.    

The strategy? Reduce the total number of stores to 1,600 nationwide. 

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

HEDGE FUNDS: A Brief Review for Physicians

By Christopher J. Cummings CFA CFP™

By Dr. David Edward Marcinko MBA MEd CMP™

SPONSOR: http://www.CertifiedMedicalPlanner.org

***

***

A hedge fund in the United States is generally a limited partnership providing a limited number of qualified investors with access to general partner investment decisions with little restriction in the type of investments or use of leverage. While the flexibility available to a hedge fund from a regulatory standpoint implies a high degree of potential risk, there is a wide range of investment philosophies, strategies, security types and objectives captured under the broad title of hedge fund.

Thus, generalizations regarding the characteristics of hedge funds are even less appropriate than with mutual funds, and evaluation of the investment characteristics and merits of a hedge fund strategy must be on a case-by-case basis. Likewise, the cost structure of a hedge fund often includes a base management fee to the general partner plus a performance-based fee or percentage of the profits, and must be evaluated on a case-by-case basis.

Several different investment vehicles operate under the oversight of varying regulatory bodies which provide access to an investment-managers’ discretionary decisions. While each approach generally represents ownership of an underlying pool of securities, there is usually a great deal of flexibility for the manager to deviate from a specific asset class or investment approach. Also, the fee structure of each vehicle can vary greatly and be quite large once distribution fees and sales charges are taken into account.

CITE: https://www.r2library.com/Resource

Thus, it is important for a medical professional to remember the following:

1. Evaluate the features and costs of an investment vehicle carefully;

2. Consider the cash flows and valuations of the securities that the manager or management approach will focus on as if the investments were being made directly, and above all;

3. Read the prospectus or agreement carefully before making any investment.

4. Visit: http://www.MarcinkoAssociates.com

COMMENTS APPRECIATED

Thank You.

***

***

PODCAST: RIP James Simons [Renaissance Technologies]

HEDGE FUND

By Staff Reporters

***

***

“I did a lot of math. I made a lot of money, and I gave almost all of it away. That’s the story of my life.”

There are longer versions of the life story of Jim Simons, the legendary mathematician, quantitative investing pioneer, and philanthropist who just died at age 86, but his summary is pretty good.

In 1978, Simons started what would become his wildly successful hedge fund, Renaissance Technologies, where he used his mathematical savvy to deliver a performance that outpaced Warren Buffett and George Soros. Its signature fund averaged 66% annual returns.

With his wife, Marilyn Simons, he also started the Simons Foundation, which gave billions to causes they cared about—including, most recently, the Dublin–New York portals.

PODCAST: https://www.youtube.com/watch?v=QNznD9hMEh0

COMMENTS APPRECIATED

Thank You

***

***

PODCAST: “In-Elastic Demand” in Healthcare Economics

Economic Implications of Pain, Suffering and Imminent Death

***

See the source image

By Eric Bricker MD

Examples of Inelastic Demand in Healthcare Are:
1) Emergencies
2) Patented Medications for Diseases That Have No Other Alternative Drugs
3) Doctor Specialties Where the Patient Has No Choice in the Services Such As Radiologists, Anesthesiologists and Pathologists [RAP]

****

***

COMMENTS APPRECIATED.

Thank You

Join the Medical Executive-Post

***

***

***

PRISONER’S DILEMMA: In Health Economics

DEM white shirt

By Dr. David Edward Marcinko MBA MEd CMP

Understanding the Prisoner’s Dilemma

[From Wikipedia, the free encyclopedia]

As all economists and psychologists know, the prisoner’s dilemma is a standard example of a game analyzed in game theory that shows why two completely “rational” individuals might not cooperate, even if it appears that it is in their best interests to do so. It was originally framed by Merrill Flood and Melvin Dresher working at RAND in 1950. Albert W. Tucker formalized the game with prison sentence rewards and named it, “prisoner’s dilemma” (Poundstone, 1992), presenting it as follows:

Two members of a criminal gang are arrested and imprisoned. Each prisoner is in solitary confinement with no means of communicating with the other. The prosecutors lack sufficient evidence to convict the pair on the principal charge. They hope to get both sentenced to a year in prison on a lesser charge.

Simultaneously, the prosecutors offer each prisoner a bargain. Each prisoner is given the opportunity either to: betray the other by testifying that the other committed the crime, or to cooperate with the other by remaining silent.
The offer is:

  • If A and B each betray the other, each of them serves 2 years in prison
  • If A betrays B but B remains silent, A will be set free and B will serve 3 years in prison (and vice versa)
  • If A and B both remain silent, both of them will only serve 1 year in prison (on the lesser charge)

It is implied that the prisoners will have no opportunity to reward or punish their partner other than the prison sentences they get, and that their decision will not affect their reputation in the future. Because betraying a partner offers a greater reward than cooperating with him, all purely rational self-interested prisoners would betray the other, and so the only possible outcome for two purely rational prisoners is for them to betray each other.
***

thats-outrageous-prisoners-rights-to-free-medical-care-af

***

The interesting part of this result is that pursuing individual reward logically leads both of the prisoners to betray, when they would get a better reward if they both kept silent.

In reality, humans display a systemic bias towards cooperative behavior in this and similar games, much more so than predicted by simple models of “rational” self-interested action. A model based on a different kind of rationality, where people forecast how the game would be played if they formed coalitions and then they maximize their forecasts, has been shown to make better predictions of the rate of cooperation in this and similar games given only the payoffs of the game.

An extended “iterated” version of the game also exists, where the classic game is played repeatedly between the same prisoners, and consequently, both prisoners continuously have an opportunity to penalize the other for previous decisions. If the number of times the game will be played is known to the players, then (by backward induction) two classically rational players will betray each other repeatedly, for the same reasons as the single shot variant. In an infinite or unknown length game there is no fixed optimum strategy, and Prisoner’s Dilemma tournaments have been held to compete and test algorithms.

In Health Economics

Advertising is sometimes cited as a real-example of the prisoner’s dilemma.

When cigarette advertising was legal in the United States, competing cigarette manufacturers had to decide how much money to spend on advertising. The effectiveness of Firm A’s advertising was partially determined by the advertising conducted by Firm B. Likewise, the profit derived from advertising for Firm B is affected by the advertising conducted by Firm A. If both Firm A and Firm B chose to advertise during a given period, then the advertising cancels out, receipts remain constant, and expenses increase due to the cost of advertising. Both firms would benefit from a reduction in advertising.

***

cigarette+smoke

***

However, should Firm B choose not to advertise, Firm A could benefit greatly by advertising. Nevertheless, the optimal amount of advertising by one firm depends on how much advertising the other undertakes. As the best strategy is dependent on what the other firm chooses there is no dominant strategy, which makes it slightly different from a prisoner’s dilemma. The outcome is similar, though, in that both firms would be better off were they to advertise less than in the equilibrium. Sometimes cooperative behaviors do emerge in business situations.

For instance, cigarette manufacturers endorsed the making of laws banning cigarette advertising, understanding that this would reduce costs and increase profits across the industry. This analysis is likely to be pertinent in many other business situations involving advertising

Without enforceable agreements, members of a cartel are also involved in a (multi-player) prisoners’ dilemma. ‘Cooperating’ typically means keeping prices at a pre-agreed minimum level. ‘Defecting’ means selling under this minimum level, instantly taking business (and profits) from other cartel members. Anti-trust authorities want potential cartel members to mutually defect, ensuring the lowest possible prices for consumers.

More Healthcare Examples:

Assessment

The prisoner’s dilemma game can be used as a model for many real world situations involving cooperative behavior. In casual usage, the label “prisoner’s dilemma” may be applied to situations not strictly matching the formal criteria of the classic or iterative games: for instance, those in which two entities could gain important benefits from cooperating or suffer from the failure to do so, but find it merely difficult or expensive, not necessarily impossible, to coordinate their activities to achieve cooperation.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

COMMENTS APPRECIATED

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™ Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

DAILY UPDATE: Mortgage Rates, Ascension Healthcare Network Security Event with Mixed Markets

MEDICAL EXECUTIVE-POST – TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Novavax, the Covid vaccine-maker’s value doubled after it announced a $1.2 billion deal to develop new shots with Sanofi.

And, Mortgage rates fell for the first time since March, to just over 7%.

Here’s where the major stock market benchmarks ended:

  • The S&P 500 index rose 8.60 points (0.2%) to 5,222.68, up 1.9% for the week; the Dow Jones Industrial Average® ($DJI) advanced 125.08 points (0.3%) to 39,512.84, up 2.2% for the week and its eighth straight daily gain; the NASDAQ Composite® ($COMP) fell 5.40 points (0.03%) to 16,340.87, up 1.1% for the week.
  • The 10-year Treasury note yield (TNX) increased more than 5 basis points to 4.50%.
  • The CBOE Volatility Index® (VIX) fell 0.14 to 12.55.

Chip makers ranked among top gainers Friday after Taiwan Semiconductor Manufacturing (TSM) shares surged 4.5% after the company said its April revenue soared 60% behind AI-driven demand. The Philadelphia Semiconductor Index (SOX) climbed 1% and posted a 1.9% gain for the week. Consumer staples and transportation shares were also strong. Energy shares slipped behind a 1.2% drop in WTI Crude Oil (/CL) futures, though oil still ended slightly higher for the week.

CITE: https://www.r2library.com/Resource

National hospital operator Ascension said a “cyber security event” has disrupted some of its clinical operations, according to a news release. Ascension, a St. Louis-based nonprofit and Catholic healthcare network, announced it had detected “unusual activity” on some of its systems. In response, the company kicked off an investigation and remediation efforts—including turning to outside cybersecurity firm Mandiant for help, as well as notifying the “appropriate authorities,” per the release.

CITE: https://tinyurl.com/tj8smmes

Planet Fitness to raise membership price for the first time since 1998. It’s going to take more than $10/month to join a gym once Planet Fitness raises the price of a basic membership for new members to $15 per month this summer. The $10 amount, which has held steady for 26 years, was considered a sweet spot where people were happy to sign up and wouldn’t bother to cancel once they gave up on their fitness goals. But after posting weaker-than-expected Q1 results, the gym chain decided it’s time to change, even though execs acknowledged that customers are looking to save rather than spend.

CITE: https://tinyurl.com/2h47urt5

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Your Referrals -0-

Thank You

PHYSICIAN FINANCIAL PLANNING: https://www.amazon.com/Comprehensive-Financial-Planning-Strategies-Advisors/dp/1482240289/ref=sr_1_1?ie=UTF8u0026amp;qid=1418580820u0026amp;sr=8-1u0026amp;keywords=david+marcinko

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

The M1 and M2 Money Supply

By Staff Reporters

***

***

DEFINITION: In macro-economics, the money supply (or money stock) refers to the total volume of currency held by the public at a particular point in time. There are several ways to define “money”, but standard measures usually include currency in circulation (i.e. physical cash) and demand deposits (depositors’ easily accessed assets on the books of financial institutions . The Central Bank [FOMC] of a country may use a definition of what constitutes legal tender for its purposes.

CITE: https://www.r2library.com/Resource

***

Though there are a few variations of money supply, most economists tend to focus on M1 and M2. The former takes into account cash and coins in circulation, as well as demand deposits in checking accounts and traveler’s checks. In other words, money that’s either in your hand or can be accessed very easily.

Meanwhile, M2 accounts for everything in M1 and adds savings accounts, money market funds, and certificates of deposit (CDs) below $100,000. It’s money you have access to, but it takes a little extra effort to put this capital to work. It’s M2 money supply that’s raising eyebrows on Wall Street and making history.

***

What’s of interest is what’s happened to M2 money supply over the trailing year. Following a peak of $21.7 trillion in July 2022, M2 has fallen to a fresh reading of $20.81 trillion, as of May 2023. Although the May reading was higher than April and broke a nine-month downtrend, we’ve still witnessed a 4.1% aggregate drop in M2 from its all-time high. 

Considering that M2 enjoyed a historic expansion during the pandemic, it’s certainly possible that a 4.1% decline can be shrugged off as nothing more than money supply reverting back to the mean. But history suggests otherwise.

Though history rarely repeats itself on Wall Street, it often rhymes. We haven’t seen a meaningful year-over-year decline in M2 money supply since the Great Depression in 1933.

***

And so, based on what we’re seeing from M2 money supply, commercial bank lending, and domestic banks tightening their lending standards for C&I loans, the ingredients for a U.S. recession are most definitely there. Stock losses have, historically, been most pronounced in the months that follow the official declaration of a recession by the eight-economist panel of the National Bureau of Economic Research.

However, Wall Street’s performance is largely dependent on your investment time frame. If you’re patient, these and other potentially worrisome money metrics represent nothing more than temporary white noise.

***

COMMENTS APPRECIATED

Thank You

***

***