Craig Venter Unveils Synthetic Life

Some Positive News on Memorial Weekend 2024

By Dr. David Edward Marcinko; MBA, MEd, CMP™

Was Artificial Life Created A Decade Ago?

According to Craig Venter “synthetic life” was created. Venter is the American biologist and entrepreneur most famous for his role in being one of the first to sequence the human genome. He has now reportedly synthesized the first artificial cell.

I don’t know about you, but this is huge news – regardless of whether you call it “life” or not.

An Arm Chair Philosopher

Now, I am not speaking as a doctor or scientist; but rather as an armchair economist and philosopher recalling my undergraduate days at Loyola University Maryland, under the tutelage of the late Aldo Tassi PhD. So, I repeat, this was huge news and an interesting piece of science. It is historic, and has large implications for the future and even the economy. Why?

The Invisible Hand

Much of our time here at the ME-P is spent integrating the hard and soft sciences of practice management, economics and financial planning for a medical audience. But occasionally, negative situations, political cycles and pessimistic opinions on our topic channels are expressed. These disparaging political remarks even indirectly target the USA and our very survival as a free nation and self-governing people.

IOW: Contrary to innovations, and innovators, like Craig Venter.

Nevertheless, there an “invisible hand” – call it economics or capitalism – that keeps us moving in the direction of survival. And, we are conscious beings capable of controlling the rate of that progression in all fields of human endeavor.

What it Is

A chromosome was designed in digital code on a computer and then transplanted into a bacterial cell, transforming that cell into a new bacterial species. Apart from the usual blueprint for proteins, the DNA also carried the names of the key contributors and even its own email address.

How it Works

As reported according to Venter, “This is the first self-replicating species on the planet, whose parent is a computer.”

And, he has already mentioned some potential practical applications for his discovery: a vaccine for HIV and a new strain of algae that can significantly decrease CO2-levels and provide a source for gasoline.

Assessment

And so, on this Memorial Weekend – a day for remembering death and sacrifice – let us celebrate life and achievement instead by stating that we are not apologists for the USA.

As the last best hope for this planet, we are not always right or politically correct, but this country offers the greatest opportunity on earth for human advancement, capitalism and success through conscientious work effort.

We do not believe America has seen better days. Those who fought did not die in vain. Better days are still in our future. We are optimistic about the long-term future of our country when looking at our progression to ameliorate the planet’s ills, to-date. We have come out of hard times before – like the current recession – by taking innovative steps forwards, not backwards. While we are likely to go through a period of adjustment in the near-term, the end result will be further individual, national and private progress in the USA. God Bless America.

Rest assured, we will continue to lead and create the world, much like Crag Venter created artificial life. Candor – Intelligence – Goodwill to all

Conclusion

And so, your thoughts and comments on this ME-P are appreciated. What do you think of this development? What economic discoveries, medical cures, life enhancing inventions and/or break-thru innovations will this creation open up?

Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, be sure to subscribe. It is fast, free and secure.

Channel Surfing the ME-P

Have you visited our other topic channels? Established to facilitate idea exchange and link our community together, the value of these topics is dependent upon your input. Please take a minute to visit. And, to prevent that annoying spam, we ask that you register. It is fast, free and secure.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

INVITE: Professor Marcinko to Your Next Seminar or Event

See You Soon

CMP logo

SPONSOR: http://www.CertifiedMedicalPlanner.org

Colleagues know that I enjoy personal coaching and public speaking and give as many talks each year as possible, at a variety of medical society and financial services conferences around the country and world. All in a Corona safe environment.

Avatar of Dr. Marcinko Speaking as MSL

MARCINKO in the METAVERSE

These include lectures and visiting professorships at major academic centers, keynote lectures for hospitals, economic seminars and health systems, end-note lectures at city and statewide financial coalitions, and annual lectures for a variety of internal yearly meetings.

LIVE or PODCAST enabled, as well.

Topics Link: imba-inc-firm-services

Teleconference: https://medicalexecutivepost.com/2020/10/14/me-marcinko-and-my-avatar/

My Fond Farewell to Tuskegee University

And so, we appreciate your consideration.

Invite Dr. Marcinko

CONTACT: ANN MILLER RN MHA CMP®

[ME-P Executive-Director]

PH: 770-448-0769

EM: MarcinkoAdvisors@msn.com

THANK YOU

***

PODCAST: Health Insurance Denials Contradict DEI, ESG and Fairness Initiatives

By Eric Bricker MD

***

***

CITE: https://www.r2library.com/Resource/Title/0826102549

***

ORDER: https://www.amazon.com/Dictionary-Health-Insurance-Managed-Care/dp/0826149944/ref=sr_1_4?ie=UTF8&s=books&qid=1275315485&sr=1-4

***

COMMENTS APPRECIATED

Thank You

***

PODCAST: How to Select a Physician?

By Eric Bricker MD

***

***
COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Sunday Stock Market Weekend Recap

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

CITE: https://www.r2library.com/Resource

  • A tough week just ended with the Dow Jones just barely in the green, though the index snapped its 5-week winning streak thanks in large part to its worst day of trading this year on Thursday. The NASDAQ hit a new all-time high on the back of Nvidia’s strong earnings, while the S&P 500 rose but ended the week flat.
  • Bond yields rose this week as investors came to terms with the idea that the Federal Reserve may not cut rates more than once in 2024, fleeing to the safety of Treasuries. Gold ended the week down overall.
  • The market turned on copper selling off for a third straight day. And oil finally snapped its losing streak, rising on the hopes of a travel-heavy Memorial Day weekend, though crude still ended the week lower than where it started.
  • The big winner was ethereum thanks to the approval of a spot ethereum ETF by the SEC.

CITE: https://tinyurl.com/2h47urt5

The U.S. Markets were closed on Monday, May 27th, 2024. Please be aware that, transactions made after 4 p.m. EST on Friday, May 24th, 2024, will receive the closing price as of Tuesday, May 28th, 2024.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

More on “Money Psychology” for Doctors

By Rick Kahler MS CFP® ChFC CCIM http://www.KahlerFinancial.com

Rick Kahler CFPAnyone who sent a check to the IRS last month certainly doesn’t need to be convinced that there is a relationship between money and feelings. I can personally attest that paying a hefty tax brings up a great deal of painful emotion.

Unification

The case for the union of money and psychology is overwhelming. Almost everyone experiences fear, sadness, grief, anger, or happiness around money events. Large life events like divorce, death, bankruptcy, losing a job, and selling a home clearly involve money and evoke emotions.

We may be less likely to notice the psychological aspects of smaller money events. Yet even acts like paying monthly bills, buying birthday gifts, or shopping for groceries have an emotional component.

The Research

Researchers like psychologist Daniel Kahneman PhD (who won the Nobel prize in economics) find that 90% of all financial decisions are made emotionally, not logically. Even the seemingly cold and calculating world of investing is driven by emotions. Economic theory is being set on its head as economist are slowly coming to realize that, regarding money, consumers often don’t make rational decisions that are in their best interests.

Yet decades after a small group of pioneering financial planners and therapists first met to explore the relationship of emotions and money, the field of financial psychology is still in its infancy. It’s really no wonder.

The Money Side

On the money side of the equation, we have institutions like large brokerage houses, insurance companies, and banks. Like all businesses, they need to be profitable. Any concern these institutions may have about the union of finance and psychology is likely to focus on ways to manipulate customers’ emotions in order to sell more of their goods and services.

The Emotional Side

On the emotional side, psychologists and therapists rarely mention money issues. When they do talk about money, it’s often in the context of their own fees. Their training doesn’t address the idea that both they and their clients may have emotional issues or beliefs around money that could be destructive.

Tax

The Gap

This leaves a big gap. In the middle of it are consumers who don’t know how to develop healthier patterns of behavior around money. They may overspend to relieve stress, feel overwhelmed by credit card debt, be unreasonably fearful about financial security, be overly trusting or overly suspicious, or give or lend too much to family members.

Some of these consumers have at least some idea that their destructive financial patterns are psychological. They may realize they need more than financial facts to change those patterns. Yet they may have no idea where to find the help they need.

More:

The Financial Planners

The one group of professionals that is moving to fill that need is client-focused financial planners. Unlike advisors who sell financial products, client-focused financial planners receive no commissions but charge fees for their advice. By law, they must act as fiduciaries and advocates for their clients.

Historically, financial planners have not embraced the notion of money psychology. Obtaining the Certified Financial Planner® designation still requires no formal training even in client communications or conflict resolution. Yet a small but growing group of client-centered financial planners is seeking out training in psychology and communication. A few even partner with financial therapists.

Assessment

The challenge for consumers is how to find these professionals. One source is the Financial Therapy Association, which has a list on its website at http://www.financialtherapyassociation.org.

Gradually, more consumers as well as professionals are realizing that it’s possible to combine financial knowledge and psychology to create more balanced relationships with money. This awareness is sure to increase the demand for financial psychology services. It will be exciting to watch this infant profession as it grows.

COACHING: https://medicalexecutivepost.com/coach/

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™


***

PHYSIOLOGY v. PSYCHOLOGY: The Financial Planning Divide

THE PHYSIOLOGIC v. PSYCHOLOGICAL FINANCIAL PLANNING DIVIDE

[Holistic Life Planning, Behavioral Economics & Trading Addiction]

READ HERE: Psychology Behavioral Economics Finance

***

***
By Dr. David Edward Marcinko MBA MEd CMP

COMMENTS APPRECIATED

THANK YOU
***

***

Activity-Based-Medical-Cost Accounting and Management

A Non-Traditional Accounting System

[By Dr. David Marcinko MBA MEd CMP]CPA

Sooner or later you will want to ascertain and then demonstrate the cost effectiveness of your medical care. By using the process of Activity Based Cost (ABC) management, you will be able to do so.  But, if you’re using a traditional accounting system, you won’t know a thing about your activity costs. Here’s how. 

Traditional Cost Accounting Methods 

In a traditional medical practice cost accounting system, costs are assigned to different procedures and services based on volume.  In others words, office costs are spread over the entire office’s product line and you may not know the true profitability of any single medical activity. So, if the office is doing more “procedures” than general medicine, for example, more indirect office overhead costs will be allocated to the procedural portion of the practice. 

ABC management, on the other hand, determines the actual costs of the resources that each service consumes. Because general medicine requires more human resources than “technical procedures,” ABC management will assign more costs to the general medical portion of the practice. 

Accordingly, most physicians, office managers, and their accountants are surprised that a prior notion of office profitability is different than previously thought. ABC management is just more accurate in measuring medical service profitability than traditional accounting methods. 

Medical Activity Cost Drivers 

Examples of medical activities that are office cost drivers include such items as monitoring vital signs, taking radiographic images, removing dressings or casts, performing laboratory tests or veni-punctures, surgical set-ups or operative procedures; etc.  

However, in the office setting, the most economically important activities are listed as specific CPT codes for each medical specialty.  The most important end result of ABC management is the shift of general overhead costs to low volume services from high volume services. These effects are not symmetrical as there is a bigger dollar effect on the per-unit costs of the low volume service.  

ABC Managerial Accounting Improvements 

ABC management improves office managerial cost accounting systems in three ways: 

  1. It increases the number of cost pools used to accumulate general overhead office costs. Rather than accumulate overhead costs in a single office-wide pool, costs are accumulated by activity, service or procedure.
  2. It changes the base used to assign general overhead costs to services or patients. Rather than assigning costs on the basis of a measure of volume (employee or doctor hours), costs are assigned on the basis of medical services or activities that generated those costs.
  3. It changes the nature of many overhead costs in that those formerly considered indirect, are now traced to specific activities or services. The office service mix may then be adjusted accordingly, for additional profit.   

Methodology 

In order to perform an ABC analysis for your medical office, calculate the cost of delivering a single unit of medical or surgical activity using only the work component of the resource based relative value scale (RBRVS).

Do this by adding up your office’s average variable expenses for the prior 1-3 years.  Now, count the number of work resource based relative value units (RBRVUs) delivered for each CPT code for the same time period, using the latest edition of the Federal Register to obtain the latest list of RVUs by CPT code. Then divide total variable expenses by the total number of work RVUs in order to arrive at the marginal cost of a single unit of service for the time period being evaluated.

For example, if your office had variable expenses of $480,000, and produced 80,000 work RVUs last year, it cost $6, on top of the office’s fixed expenses, to deliver one unit of work product. So, if an HMO plan offers to reimburse you at a rate of $11 per member, per month, and you can expect to reasonably deliver on average of one RVU pm/pm, you’ll earn enough on the contract to cover your marginal costs and some of your fixed and direct expenses. 

CASE MODELs: CVPA 4 and CVPA 3

dhimc-bookAssessment

Remember, this method assumes that you have the excess operating capacity and time slots, available and unused, to see the additional patients of the new plan without adding extra overhead expenses to service the contract.

If not, or if you plan for capitation to become a major portion of your practice, you might want the capitated contract(s) to cover all your office expenses, so be sure to include both the fixed and other direct costs to your variable cost calculations. ABC determines the actual costs of resources rendered for each activity and represents a real measure of practice profitability. Office service mix can then be changed to either maximize revenues or better suit your practice personality.

A Caveat

Suppose however, that a medical service is competitively priced but still shows that the CPT code is unprofitable. For example, the costs of special requests can adversely affect office profits. Yet, special patient requests are one of the biggest reasons that a CPT code or procedure isn’t profitable.

In this case, look closely at activity costs and determine which ones are being performed inefficiently. Improving the efficiency of those kinds of medical services, or referring them out or abandoning them all together, will increase office profitability.

MORE: ABCM

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

PHYSICIANS: www.MedicalBusinessAdvisors.com
HOSPITALS: http://www.crcpress.com/product/isbn/9781466558731
CLINICS: http://www.crcpress.com/product/isbn/9781439879900
BLOG: www.MedicalExecutivePost.com
FINANCE: Financial Planning for Physicians and Advisors
INSURANCE: Risk Management and Insurance Strategies for Physicians and Advisors

***

Product DetailsProduct DetailsProduct Details     

Product DetailsProduct Details

***

MEMORIAL DAY: Weekend Origination Thoughts 2024

“Decoration Day”

By Dr. David E. Marcinko MBA MEd CMP

”Memorial Day (Decoration Day) is a federal holiday in the United States for honoring and mourning the military personnel who died while serving in the United States Armed Forces.

The holiday is now observed on the last Monday of May, having been observed on May 30th from 1868 to 1970.

***

***

DAILY UPDATE: Friday Before Memorial Day Weekend and the Stock Market Collapse

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

The Friday before Memorial Day is never action packed, and this year is no exception as earnings season begins to wrap up and economic readings slow down. Two reports to watch for tomorrow: April Durable Goods Orders and University of Michigan’s May sentiment report.

Durable Goods Orders are big-ticket items with a shelf life of three or more years—think appliances and furniture for consumers, or machinery, equipment, and vehicles for businesses. More durable goods orders indicate a healthy economy, as consumers and companies alike wouldn’t spend as much if they weren’t confident they could afford it, and also provides insight into how strong the manufacturing industry is.

The University of Michigan’s consumer sentiment index is a survey of consumers via telephone to better understand how they feel about the economy, what they’re spending their money on, etc. The preliminary findings earlier this month weren’t great thanks to sticky inflation, and tomorrow’s finalized readings won’t change much. But with the latest CPI reading indicating inflation might yet be tamed, next month’s report could be much more illuminating.

CITE: https://www.r2library.com/Resource

Here’s where the major benchmarks ended:

  • The S&P 500® index (SPX) fell 39.17 points (0.7%) to 5,267.84; the Dow Jones Industrial Average lost 605.78 points (1.5%) to 39,065.26; the NASDAQ Composite® ($COMP) shed 65.51 points (0.4%) to 16,736.03.
  • The 10-year Treasury note yield rose more than 4 basis points to 4.479%.
  • The CBOE Volatility Index® (VIX) rose 0.48 to 12.77.

Financial shares were among Thursday’s weakest performers amid ideas a “higher-for-longer” Fed rate outlook could pressure bank margins. The KBW Regional Bank Index (KRX) dropped almost 3% to a three-week low. Other interest-rate-sensitive sectors, including real estate and utilities, took pressure.

In other markets, WTI Crude Oil (/CL) futures fell for the fourth straight trading day and closed at a three-month low under $76 per barrel.

CITE: https://tinyurl.com/2h47urt5

Spot Ethereum ETFs were approved by the SEC in another big win for crypto, following the approval of spot bitcoin ETFs earlier this year.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

On Death Talk, Risk Management and Financial Planning

A financial planning challenge

Rick Kahler MS CFP

By Rick Kahler MS CFP®

One of the challenges in financial planning is the strong taboo in our society against talking about money. Another powerful taboo is talking about death when someone has a serious illness.

When someone is diagnosed with cancer, for example, the focus is almost always on treatment and recovery. Rarely is there any discussion of what happens if the treatment doesn’t work. There seems to be an unspoken belief that if we don’t talk about it, it won’t happen.

Not talking about death isn’t limited to family and friends, according to Dr. Carol McClanahan CFP®

For example, in a recent presentation to financial advisors at the Insiders Forum in Phoenix, she pointed out that many doctors shy away from talking about dying until the very end.

Given this strong reluctance to talk about both money and dying, how can you work with a financial advisor to deal with the financial and emotional issues that go along with a family member’s serious illness?

Here are some suggestions based on Dr. McClanahan’s talk:

Don’t expect someone facing a serious illness to give you an accurate prognosis of their disease, as they are often in denial. McClanahan suggests turning to “Dr. Google” for accurate information. Specifically, she recommends the National Institutes of Health (www.nih.gov), which has statistics on every disease imaginable.

  1. Learn to interpret what doctors say. For example, when a cancer patient is told chemotherapy has a 25% chance of working, the average patient hears “working” as “being cured.” “Working” actually means there is a 25% chance of the tumor shrinking. Often the chances of being cured are far less than 25%, and the physical effects of chemotherapy can be devastating to one’s remaining quality of life. McClanahan says, “Most of what we do to people at the end of life is unnecessary torture.”
  2. Find out early about options for palliative care. This is multidisciplinary care focused on treating the symptoms of treatment, relieving suffering, and improving the quality of life. Because of denial and unwillingness to talk about what happens if they don’t get better, many patients never get into palliative care or get into it way too late. Similarly, most patients wait too long to get into hospice care. The average time in hospice care, according to McClanahan, is just 19 days.
  3. Share your money concerns with the advisor. McClanahan says that anxiety over having enough money to pay for their care and the resulting effect on the family finances are two of the top concerns patients have. Interestingly, most financial advisors focus instead on whether advance directives, estate documents, and funeral plans are in place.
  4. Call the advisor’s attention to signs that a person’s illness is advancing. These can include a shortened attention span, not remembering details of conversations, word-finding difficulties, inability to multitask, mental fuzziness, and depression. Ask advisors to deal with these symptoms: meet early in the day, address the most important issues first, keep meetings short, include family members as appropriate, and put action items in writing.
  5. Realize that sharing your emotions is part of financial planning. Serious illness affects people in many different ways, but the underlying concerns are always emotional. Discuss those concerns with the advisor, and work together to create a comprehensive plan addressing both death and recovery. Remember that, as McClanahan put it, “preparation for a negative outcome does not reduce the risk of cure.”

***

halloween

***

The role of the financial planner

The role of a financial planner is to help clients prepare for the future, including the end of life. When that future becomes “now,” don’t hesitate to ask for the planner’s emotional support as well as financial advice. 

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

 Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™  Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

PHYSICIAN OUT-PATIENT AMBULATORY CENTERS: Consulting on ASCs and More!

SPONSOR: http://www.MARCINKOASSOCIATES.com

START TO FINISH CYCLE

***

Our Process

***

READ HERE: https://marcinkoassociates.com/asc/

COMMENTS APPRECIATED

Thank You

***

***

***

ASSET PROTECTION: Fundamentals for Physicians

Don’t Leave Yourself Unprotected

By Nicholas Efthemis CFP®

The largest concern facing physicians today is how to protect their wealth against the proliferation of malpractice claims and extraordinarily high jury verdicts. Malpractice insurance has become so expensive that physicians are greatly reducing their coverage.

Even worse, some carriers are dropping physicians that have poor claims history. When meeting with physicians my message is a simple one. Take action and do so now. Constructing a complete asset protection plan is the single most critical step towards attaining financial freedom. Physicians work hard and long hours to create wealth, and are potentially one medical malpractice claim or general negligence claim away from financial catastrophe. Detailing every asset protection strategy is beyond the scope of this article, however I will review some important concepts you should know.

Good asset protection will prevent lawsuits. Conversely, the more personal assets that remain unprotected the more likely an attorney is willing to go after you. In fact, a physician with very high malpractice coverage and unprotected assets has a target on his back. This can be avoided through lower policy limits and a complete Asset Protection Plan.

What is the Best Asset Protection Plan?

The best Asset Protection Plan for a physician or any high net worth client removes all assets from the client’s name. The worst plan has all the assets in the client’s name. You will need to work with a specialized attorney to find the ideal plan for you. In many cases your largest asset are the funds in your retirement plan or IRA. The good news is that creditors cannot reach ERISA qualified plan assets. Common ERISA plans include:

1. 401(k) 403(b) Plan

2. Profit Purchase Plan

3. Money Purchase Plan

4. New Comparability Plans

5. Defined Benefit Plan

Keep in mind IRAs are not considered ERISA qualified plans and have no federal protection from creditors. Many individual states have protected IRAs in part or in full. In my state, New York, IRAs are fully protected. If you live in a state where they are not you should seriously consider moving the money into an ERISA qualified plan. This can be accomplished even if you are retired.

What about my house?

It is never a good idea, from an asset protection standpoint to own property in just your name. If you get sued the property is almost entirely at risk. Owning the marital home jointly with your spouse can be effective. You will protect the home from each other’s individual creditors (though not joint creditors). You should not title many assets as tenants by the entirety for several reasons. Physicians suffer a higher divorce rate than the already high national average of fifty percent. Should a divorce occur you will have ensured the spouse will receive half of that asset. Also, you do nothing to protect the asset against joint creditors.

How should my other assets be held?

You will need to consult a specialized asset protection attorney. Most effective plans involve the use of a corporate structure, limited liability company, or family limited partnership. Keep in mind that the entity you choose will have its own unique asset protection and tax consequences.

  • Sole proprietorships and partnerships are the worst way to own a business. If a sole proprietor is found negligent in his duties for the business that injures a third person, the sole proprietor is personally liable. If a product or employee harm a third person or someone is harmed on the premises, the sole proprietor is personally liable. With a partnership you have all of the above risks coupled with a partner who can cause you even more liability.
  • Limited Liability Companies (LLCs), Family Limited Liability Companies (FLLCs) and Family Limited Partnerships (FLPs) are the most commonly used tools by asset protection specialists today. A creditor attempting to obtain assets of a debtor when the assets are in a LLC will likely have very limited success. In fact, a charging order is the only remedy a court can give a creditor. A charging order does not allow creditors to sell assets of the LLC or force distributions of income. It also cannot transfer interest in the LLC to the creditor. A creditor who obtains a charging order against an LLC may in fact receive a K-1 for income they never did and may never receive.

What should I consider holding in an LLC?

I advise my physician clients to consider holding rental real estate, after tax investment accounts, planes, boats and any personal assets of value in an LLC. Unless you are single and your home is titled in your name alone, the marital home may not be a good candidate for transfer to an LLC. By doing so, you forego the capital gains exemption of $250,000 per spouse. Brokerage accounts can be owned by an LLC, and when constructed correctly you will have full ability to invest as you desire. The investments within the account would then be protected. Assets such as planes and boats may be best held in their own LLCs to protect the rest of your estate from their unique risk profiles.

Example:

  • Personal Residence $750,000 Tenants by the entirety
  • Vacation Property $300,000 LLC #1
  • Investment Account $900,000 LLC #1
  • 401 (k) 2,400,000 ERISA plans are federally protected
  • Boat $55,000 LLC #2

Assessment

The topic of asset protection is vast and complicated, but I hope to break out additional topics such as off-shoring, accounts receivable leveraging, fiduciary duties, and insurance in subsequent articles. My hope is that I have given you enough ideas and motivation to act now. You cannot wait until there is an issue. It is critical that your financial planner, attorney and accountant are all very knowledgeable on asset protection. Do not rely on a generalist to navigate such a complex yet critical issue.

About the Author:

Nicholas Efthemis is a Certified Financial Planner™ who helps physicians plan wisely and live fully by creating a financial plan that helps them focus on their medical practice and live a better life.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

***

***

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

NVIDIA: Booming Artificial Intelligence & Stock!

SPLITS STOCK 10:1 ANNOUNCED

By Staff Reporters

***

***

Nvidia sales rose 262% as AI keeps booming

The company whose chips are powering the Artificial Intelligence revolution saw an even bigger jump in sales last quarter than analysts had expected: to $26 billion.

CITE: https://www.r2library.com/Resource/Title/082610254

That’s a good sign for the future of AI and probably for the entire stock market, on which Nvidia has an outsized influence. CEO Jensen Huang declared “the next industrial revolution has begun,” as Nvidia predicted $28 billion in sales this quarter. The company also announced plans to split its stock 10-for-1 next

Stock Splits: https://medicalexecutivepost.com/2023/08/14/stock-splits-a-vital-equity-investing-concept-for-physician-investors/

AI: https://www.sas.com/en_us/insights/analytics/what-is-artificial-intelligence.html

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Uber Health, Lyft Healthcare, HHS Cyber Attacks as Markets Swoon

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

Your referral Count -0-

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Here’s where the major benchmarks ended:

  • The S&P 500 index lost 14.40 points (0.3%) to 5,307.01; the Dow Jones Industrial Average® ($DJI) declined 201.95 points (0.5%) to 39,671.04; the NASDAQ Composite® ($COMP) slipped 31.08 points (0.2%) to 16,801.54.
  • The 10-year Treasury note yield (TNX) rose more than 1 basis point to 4.426%.
  • The CBOE Volatility Index® (VIX) increased 0.43 to 12.29.

Retailer shares were among the market’s weakest performers after Target’s (TGT) quarterly results, released before Wednesday’s open, fell short of expectations. Target shares tumbled 8% after the company reported revenue fell 3% in the first quarter from the year-earlier period. During the company’s earnings call, Target CEO Brian Cornell noted “continued soft trends in discretionary categories” contributed to the revenue decline.

Energy companies were also under pressure after WTI Crude Oil (/CL) futures closed at a three-month low just above $77 per barrel.

CITE: https://www.r2library.com/Resource

Following a series of high-profileand costlycyberattacks against the healthcare industry, the federal government is stepping in with a $50+ million initiative intended to boost hospital cybersecurity, a division of the Department of Health and Human Services (HHS) announced on May 20th.

CITE: https://tinyurl.com/2h47urt5

Uber Health will begin rolling out a new solution designed for caregivers this summer, allowing individuals to add a caregiver to their Uber profile. That caregiver can then see and spend that person’s health benefits on eligible services, request rides to doctors’ appointments or order groceries. In the coming months, Uber Health will be working with Medicare Advantage, Medicaid and commercial plans to offer the solution.


U.S. Sens. Sheldon Whitehouse and Bill Cassidy, M.D., want to reform how primary care providers get paid through Medicare, and they also want to hear from the healthcare industry about the best way to do it. Together, they introduced a bipartisan bill, the Pay PCPs Act (S. 4338), last week to better support and improve pay for high-quality primary care providers. 


And… digital maternal health company Babyscripts announced a partnership with Lyft Healthcare to offer sponsored rides for people who are pregnant or postpartum and face barriers to transportation. The Lyft partnership will identify transportation-insecure patients and offer free rides to in-person appointments in traditional care settings and community-based healthcare services and programs.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

METAVERSE MEDICINE: Doctor, Patient Avatars Ahead?

By WebMD

In what some are calling the next iteration of the internet, the metaverse is an unfamiliar digital world where you could be an avatar navigating computer-generated places and interacting with others in real time. In this space, the constraints of our physical, bricks and mortar world and travel habits fade. And new opportunities and challenges emerge.

***


***

READ HERE: https://www.webmd.com/a-to-z-guides/news/20220812/metaverse-medicine-doctor-patient-avatars-ahead

Cite: https://www.amazon.com/Dictionary-Health-Information-Technology-Security/dp/0826149952/ref=sr_1_5?ie=UTF8&s=books&qid=1254413315&sr=1-5

***

COMMENTS APPRECIATED

Thank You

***

PODCAST: Medicare Value Based Payments Explained

By Eric Bricker MD

***

***

COMMENTS APPRECIATED

Thank You

***

***

***

PHYSICIAN’S BEWARE: Psychological “INVESTING MIND TRAPS”

By Dr. David Edward Marcinko MBA MEd CMP

SPONSOR: http://www.MarcinkoAssociates.com

As, as human beings, our brains are booby-trapped with psychological barriers that stand between making smart financial decisions and making dumb ones. The good news is that once you realize your own mental weaknesses, it’s not impossible to overcome them. 

CITE: https://www.r2library.com/Resource

In fact, psychiatrist and medical colleague Wes Boyd MD PhD MA related the following mind-traps and investing impediments that have yet to be appreciated by the financial planning community writ-large:

  • Anchoring happens when we place too much emphasis on the first piece of information we receive regarding a given subject. For instance, when shopping for a wedding ring a salesman might tell us to spend three months’ salary. After hearing this, we may feel like we are doing something wrong if we stray from this advice, even though the guideline provided may cause us to spend more or less than we can afford. Ditto for buy / sell stock recommendations without our own due diligence.
  • Myopia makes it hard for us to imagine what our lives might be like in the future. For example, because we are young, healthy, and in our prime medical practice earning years now, it may be hard for us to picture what life will be like when our health depletes and we know longer have the earnings necessary to support our standard of living. This short sighted thinking makes it hard to save adequately when we are young, when saving does the most good.
  • Gambler’s fallacy occurs when we subconsciously believe we can use past events to predict the future. It is common for the hottest sector during one calendar year to attract the most doctor investors the following year. Of course, just because an investment did well last year doesn’t mean it will continue to do well this year. In fact, it is more likely to lag the market.
  • Avoidance is simply procrastination. Even though you may only have the opportunity to adjust your health care plan through your employer once per year, researching alternative health plans is too much work and too boring for us to get around to it. Consequently, we stick with a plan that may not be best for us.
  • Loss aversion affected many investors during the stock market crash of 2008. During the crash, many doctors decided they couldn’t afford to lose more and sold their investments. Of course, this caused the investors to sell at market troughs and miss the quick, dramatic recovery.
  • Overconfident investing happens when we believe we can out-smart other investors via market timing or through quick, frequent trading. Data convincingly shows that people who trade most often under-perform the market by a significant margin over time.
  • Mental accounting takes place when we assign different values to money depending on where we get it from. For instance, even though we may have an aggressive saving goal for the year, it is likely easier for us to save money that we worked for than money that was given to us as a gift.
  • Herd mentality makes it very hard for humans to not take action when everyone around us does. For example, we may hear stories of people making significant profits buying, fixing up, and flipping homes and have the desire to get in on the action, even though we have no experience in real estate.

CMP: http://www.CertifiedMedicalPlanner.org

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Hims & Hers, MSFT-AI, Neuralink, FDIC and New Market Highs

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Microsoft unveiled new PCs with AI-powered features.

CITE: https://www.r2library.com/Resource

Hims & Hers stock soared as much as 38% on the news that it’ll provide GLP-1 injections with the same active ingredient as Ozempic or Wegovy for just $199/month—an 85% discount compared to Wegovy’s ~$1,350 monthly price tag (without insurance).

***

FDIC Chair Martin Gruenberg will resign after an investigation found widespread sexual harassment at the agency. But he won’t step down until a successor is named.

CITE: https://tinyurl.com/2h47urt5

The FDA granted Elon Musk’s neurotech company Neuralink, approval to place its brain chip into a second human test subject using a new method designed to correct issues that arose after its inaugural insertion in January, per the Wall Street Journal.

And, Optum Rx is shaking up its pharmacy model. The business says it will make drug costs more predictable and transparent for clients.

CITE: https://tinyurl.com/tj8smmes

  • All three indexes ended the day higher after Fed Governor Christopher Waller stopped by CNBC and mentioned he doesn’t think raising interest rates is in the cards, even if the Fed is waiting for more data before making cuts. The NASDAQ continued to hit new all-time highs today as investors place their bets before Nvidia’s earnings announcement tomorrow afternoon, and the S&P 500 hit yet another record.
  • Copper continued to rise as the market comes to terms with the metal’s importance, while oil fell on the news that the Biden administration will release 1 million barrels of gasoline this summer from the Northeast reserve. Meanwhile, ethereum continued to climb on the news that a new ETF may be joining the fray.

Here’s where the major benchmarks ended:

  • The S&P 500 index rose 13.28 points (0.3%) to 5,321.41; the Dow Jones Industrial Average® ($DJI) gained 66.22 points (0.2%) to 39,872.99; the NASDAQ Composite advanced 37.75 points (0.2%) to 16,832.62.
  • The 10-year Treasury note yield (TNX) lost more than 2 basis points to 4.414%.
  • The CBOE Volatility Index® (VIX) fell 0.29 to 11.86.

Banking and consumer staples were among the market’s strongest performers Tuesday, while utility shares extended a sharp upswing over the past month. The Dow Jones Utility Average® ($DJU) added 0.5% and closed at a 12-month high. Transportation companies were among the weakest performers.

In other markets, Gold (/GC) futures slipped from Monday’s record high above $2,454 per ounce, while Silver (/SI) futures ended near a 12-year high around $32.21. Gold futures are still up 17% this year due to several factors, including reports of China’s central bank buying actual gold as well as escalating conflict in the Middle East. Gold is viewed by some as a safe-haven asset during periods of heightened geopolitical tension.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

PHYSICIANS & DENTISTS: Financial Consulting & Planning

Sponsored by: http://www.MARCINKOASSOCIATES.com

START TO FINISH CYCLE

***

Our Process

***

READ HERE: https://marcinkoassociates.com/financial-planning/

RELATED: https://medicalexecutivepost.com/2023/12/15/doctor-are-you-a-financial-advisors-customer-or-client/

COMMENTS APPRECIATED

Thank You

***

***

PHYSICIANS ONLY: Hedge Funds and Venture Capitalists

SPONSORED: http://www.MARCINKOASSOCIATES.com

START TO FINISH CYCLE

***

Our Process

***

READ HERE: https://marcinkoassociates.com/hedge-funds/

MORE: https://medicalexecutivepost.com/2023/02/19/what-is-an-unregistered-security/

COMMENTS APPRECIATED

Thank You

***

***

EXPLAINED: Medical “Bottle Neck” Accounting

VARIANCE AND BOTTLE-NECK ACCOUNTING

DR. DAVID E. MARCINKO MBA MEd CMP

Any healthcare organization usually has several processes involved in the utilization of its patient services. Unfortunately, bottlenecks may arise which constrain the amount of services any given healthcare entity can deliver. 

Accounting Definition 

An accounting “bottleneck” is a process that has a low output and limits total healthcare entity revenues. If a medical business entity wants to increase sales or revenues, it has to solve its bottleneck [ie., access management] problems. 

Traditional Variance Analysis Dilemma 

With traditional variance analysis [VA], managers and administrators analyze the difference between budgeted patient revenues and actual revenues. Typically, differences between budgeted revenues and actual revenues are analyzed as seen in the example below.

Initially postulated by Horngren and Foster for manufacturing processes, VA can now be modified for medical business entity use. 

Example: 

  Patient Service Units   Contract/UCR Fee    
Budgeted sales revenues 10,000,000 * 1,23 = $ 12,300,000
Actual sales revenues 9,000,000 * 1,21 = $ 10,890,000
          -/- —————-
Total variance         $ 1,410,000
Traditional Assessment
Actual patient revenues were lower than budgeted; and the unfavorable patient sales volume variance was (9,000,000 – 10,000,000) * $ 1,23 = – $ 1,230,000. 


The actual patient revenue price was lower than budgeted as the unfavorable price variance was: ($ 1,21 – $ 1,23) * 9,000,000 = – 180,000.

Traditional variance analysis however does not point out which of the processes were bottlenecks, which caused the negative volume variance.Thus, a normal variance analysis can’t be used to solve bottlenecks in a clinic, hospital or medical practice.

Enter B-N Accounting

In bottleneck accounting however, managers and healthcare administrators determine the bottlenecks in a medical organization.And, a bottleneck accounting report shows which process were bottlenecks occur and how much money is lost in each bottleneck.

Example:

Bottleneck Patient Sales Revenues $ 800,000
Bottleneck Dep. II $ 350,000
Other Bottlenecks $ 80,000
  + —————-
Total Volume Variance $ 1,230,000

Conclusion: 

The managerial accounting modification for “bottlenecks” not only points out the bottlenecks to solve, it also shows which bottleneck is to be handled first.

And so, what are your thoughts on this accounting machination? Please comment.

References: Horngren, C. T. and G. Foster, ‘Cost Accounting, A Managerial Emphasis’, Prentice-Hall, Inc. 1987. 

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com 

Subscribe Now: Security is assured.

***

***

***

PSYCHOLOGICAL “TRAPS” of Investing

MIND TRAPS PHYSICIAN INVESTORS MUST REDUCE AND AVOID AT ALL COSTS

See the source image

By Dr. David E. Marcinko MBA MEd CMP®

SPONSOR: http://MarcinkoAssociates.com

CMP logo

SPONSOR: http://www.CertifiedMedicalPlanner.org

As human beings, our brains are booby-trapped with psychological barriers that stand between making smart financial decisions and making dumb ones. The good news is that once you realize your own mental weaknesses, it’s not impossible to overcome them.

CITE: https://www.r2library.com/Resource/Title/0826102549

In fact, Mandi Woodruff, a financial reporter whose work has appeared in Yahoo! Finance, Daily Finance, The Wall Street Journal, The Fiscal Times and the Financial Times among others; related the following mind-traps in a September 2013 essay for the finance vertical Business Insider; as these impediments are now entering the lay-public zeitgeist.

***

8 Psychological Traps All Stock Investors Should Avoid - YouTube

 Anchoring happens when we place too much emphasis on the first piece of information we receive regarding a given subject. For instance, when shopping for a wedding ring a salesman might tell us to spend three months’ salary. After hearing this, we may feel like we are doing something wrong if we stray from this advice, even though the guideline provided may cause us to spend more than we can afford.

 Myopia makes it hard for us to imagine what our lives might be like in the future. For example, because we are young, healthy, and in our prime earning years now, it may be hard for us to picture what life will be like when our health depletes and we know longer have the earnings necessary to support our standard of living. This short-sightedness makes it hard to save adequately when we are young, when saving does the most good.

 Gambler’s fallacy occurs when we subconsciously believe we can use past events to predict the future. It is common for the hottest sector during one calendar year to attract the most investors the following year. Of course, just because an investment did well last year doesn’t mean it will continue to do well this year. In fact, it is more likely to lag the market.

 Avoidance is simply procrastination. Even though you may only have the opportunity to adjust your health care plan through your employer once per year, researching alternative health plans is too much work and too boring for us to get around to it. Consequently, we stick with a plan that may not be best for us.

 Loss aversion affected many investors during the stock market crash of 2008. During the crash, many people decided they couldn’t afford to lose more and sold their investments. Of course, this caused the investors to sell at market troughs and miss the quick, dramatic recovery.

 Overconfident investing happens when we believe we can out-smart other investors via market timing or through quick, frequent trading. Data convincingly shows that people who trade most often underperform the market by a significant margin over time.

 Mental accounting takes place when we assign different values to money depending on where we get it from. For instance, even though we may have an aggressive saving goal for the year, it is likely easier for us to save money that we worked for than money that was given to us as a gift.

MORE: https://medicalexecutivepost.com/2021/09/04/more-on-money-psychology/

RELATED: https://medicalexecutivepost.com/2014/12/15/on-internet-investing-psychology/

 Herd mentality makes it very hard for humans to not take action when everyone around us does. For example, we may hear stories of people making significant profits buying, fixing up, and flipping homes and have the desire to get in on the action, even though we have no experience in real estate.

YOUR COMMENTS ARE APPRECIATED.

Thank You

***

RISK MANAGEMENT: https://www.routledge.com/Risk-Management-Liability-Insurance-and-Asset-Protection-Strategies-for/Marcinko-Hetico/p/book/9781498725989

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors : Best Practices from Leading Consultants and Certified Medical Planners™ book cover

***

“ACTIVE” INVESTMENT STRATEGIES: For Physicians

And … why doctors are different?

By Dr. David Edward Marcinko MBA MEd CMP

SPONSOR: http://www.MarcinkoAssociates.com

By Dr. David Edward Marcinko MBA CMP

There are two distinct forms of financial analysis investment strategies often used by medical colleague investors who desire to pursue an active investment strategy.

Technical Analysis: Technical analysts, sometimes referred to as chartists, use historical price data and transaction volume data to identify mis-priced securities. A key belief shared by technical analysts is that stock prices follow recurring patterns and that once these historical patterns are identified, they can be used to identify future security prices. The heart of technical analysis is identifying significant shifts in the macro/micro economic supply and demand factors for a particular securities investment.

Skeptics of technical analysis generally subscribe to the notion that the markets efficiently and accurately price securities. In fact, the weak form of the Efficient Market Hypothesis [EMH] is based on the view that investors cannot consistently earn superior returns using historical data and technical analysis alone.

Fundamental Analysis: In contrast to technical analysis – which relies on historical market returns / transactions data – fundamental analysis focuses on the underlying company’s assets, earnings, risks, dividends and intrinsic security factors to identify mis-priced securities.

Furthermore, investors using fundamental analysis can use either a top-down or bottom-up approach:

  • The top-down investor starts with global economics, including both international and national economic indicators. These may include GDP growth rates, inflation, interest rates, exchange rates, productivity and energy prices. They subsequently narrow their search to regional / industry analysis of total sales, price levels, the effects of competing products, foreign competition and entry or exit from the industry. Often they refine their search to the best business in the area being studied.
  • The bottom-up investor starts with specific businesses, regardless of their industry / region, and proceeds in reverse of the top-down approach. Bottom-up investing is an approach that focuses on analyzing individual stocks and de-emphasizes the significance of macroeconomic and market cycles. In other words, bottom-up investing typically involves focusing on a specific company’s fundamentals, such as revenue or earnings, versus the industry or the overall economy. The bottom-up investing approach assumes individual companies can perform well even in an industry that is under performing, at least on a relative basis.

And so, a medical professional utilizing fundamental analysis is attempting to find securities that are trading at market prices below their intrinsic value. Skeptics suggest this is difficult or almost impossible to achieve.

Thus, while technical analysis focuses on market price history, a security’s intrinsic fundamental analysis is determined independent of the security’s market value. Of course, a combination of both fundamental and technical analysis can also be considered.

DOCTORS ARE DIFFERENT: https://marcinkoassociates.com/doctors-unique/

CMP: http://www.CertifiedMedicalPlanner.org

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Abbvie, Treasuries, Gold, Copper and the NASDAQ Rally

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

The yield on the 10-year Treasury rose as investors wait for word from the FOMC on Wednesday, while oil initially rose on the news of the death of the president of Iran, though it fell back down to end the day lower after succession of the presidency was settled. But investors were clearly still feeling jittery as gold hit new highs on the back of geopolitical concerns. Copper also rose to a new all-time high.

Here’s where the major benchmarks ended:

  • The S&P 500 index gained 4.86 points (0.1%) to 5,308.13; the Dow Jones Industrial Average® ($DJI) lost 196.82 points (0.5%) to 39,806.77; the NASDAQ Composite rallied 108.91 points (0.7%) to 16,794.87.
  • The 10-year Treasury note yield (TNX) increased more than 2 basis points to 4.443%.
  • The CBOE Volatility Index® (VIX) rose 0.15 to 12.14.

Nvidia’s gain helped push the PHLX Semiconductor Index (SOX) more than 2% to a two-and-a-half-month high and just under a record close posted in early March. The small-cap Russell 2000® Index (RUT) added 0.3% and ended slightly below a six-week high posted last Wednesday. 

CITE: https://www.r2library.com/Resource

JPMorgan shares fell 4.5% as investors realized that they won’t have Jamie Dimon around forever—he told shareholders at a meeting today that his 5-year timetable for leaving the company no longer applies.

CITE: https://tinyurl.com/2h47urt5

After AbbVie’s Humira, the best-selling drug in the world, lost patent exclusivity in 2023, company executives placed their bets on two other AbbVie drugs, Skyrizi and Rinvoq, to make up for an anticipated steep decline in revenue.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

15 YEAR JOURNEY: From Active to Passive Investing?

By Staff Reporters

***

***

Historical Review

As can now be discerned 15 years later, two trends emerged from the aftermath of the 2008 financial crisis. One was a new type of investment that concentrated capital among a small number of firms. The other was left-wing activism in the style of Occupy Wall Street. Combined, these trends helped empower Wall Street behemoths to push much of the corporate wokeness that is so common today. The financial meltdown precipitated a transition from active to passive investment.

Definitions

Active investment is what one typically thinks of as investing — making risky stock purchases in an attempt to beat the market in the short-term.

More: https://medicalexecutivepost.com/2023/03/06/understanding-active-asset-allocation/

Passive investment, on the other hand, requires much less effort. According to Investopedia, it is a long-term strategy where investors try to “replicate market performance by constructing well-diversified portfolios” (e.g. mutual funds) typically based on a “representative benchmark” like the S&P 500 index.  In other words, it bets on the market rather than against it.

More: https://medicalexecutivepost.com/2015/03/19/more-on-passive-investing-for-physicians/

Dichotomy

Passive investing took off after the financial crisis when investors realized it wasn’t worth trying to beat the market. Why pay a broker a one to two percent fee every year to actively manage your assets, especially when the downturn revealed they often under-performed the regular market returns? Many opted for passive asset management that cost a fraction of a brokerage fee.

More: https://medicalexecutivepost.com/2022/03/09/active-or-passive-investing-pursuits/

Today

In fact, one study found that between 2008 and 2015, active funds lost $800 billion while passive funds gained over $1 trillion in new investment. As of 2019, more money is now invested in passive than in active funds.

Cite: https://www.cambridge.org/core/journals/business-and-politics/article/hidden-power-of-the-big-three-passive-index-funds-reconcentration-of-corporate-ownership-and-new-financial-risk/30AD689509AAD62F5B677E916C28C4B6

***

***

COMMENTS APPRECIATED

Thank You

***

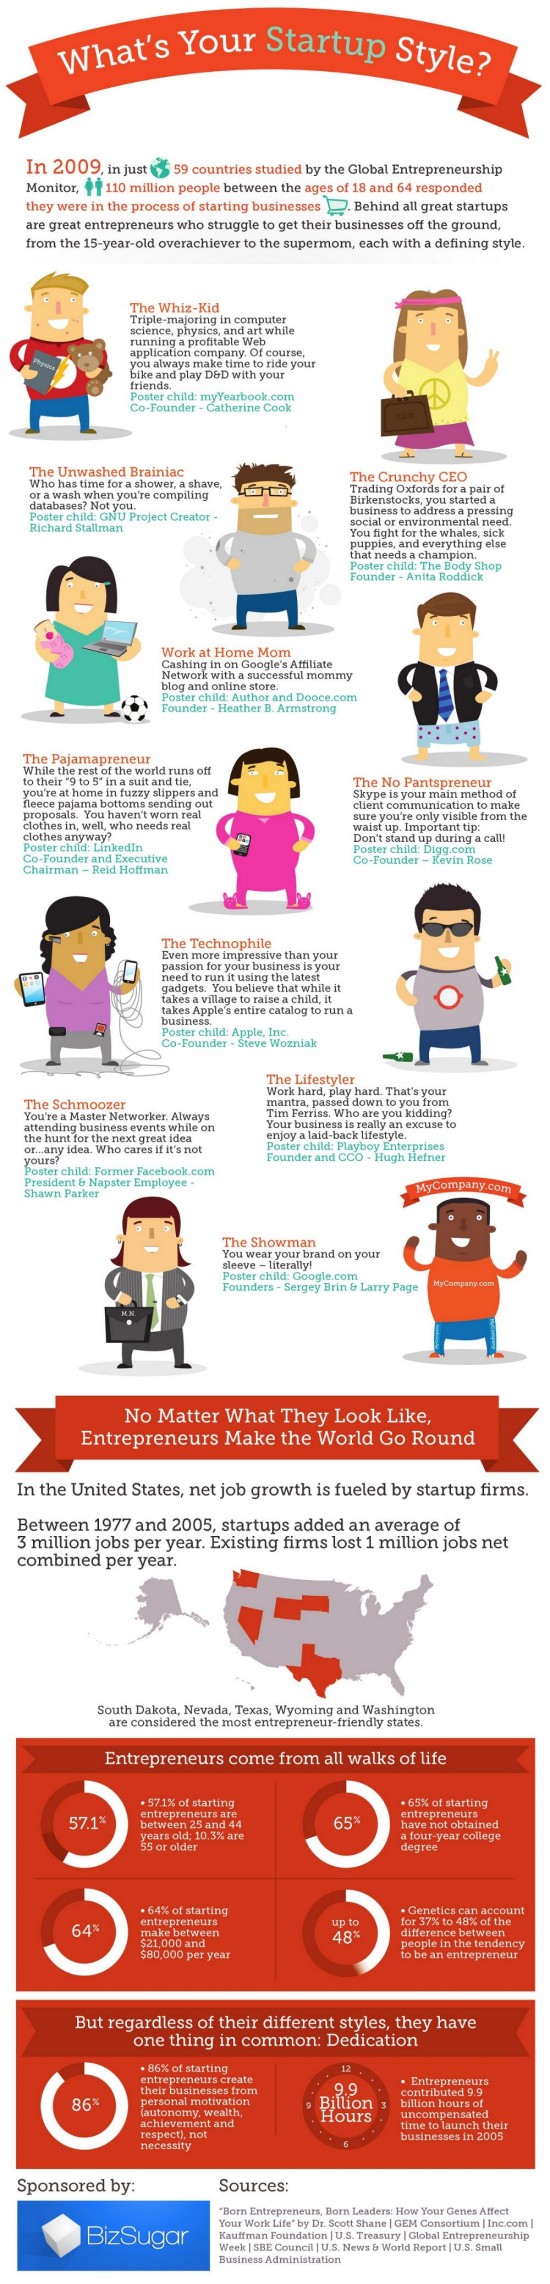
What’s Your Business [Medical Practice] Start Up Style?

Entrepreneurs, their Styles and the Drive Behind Them!

[By staff reporters]

SPONSOR: http://www.MarcinkoAssociates.com

It goes without saying that it takes a special kind of person to become a doctor, and an entrepreneur.

Driven, motivated, innovative – these are just a few of the many ways to describe individuals who risk everything to transform their vision into reality; or to save lives.

We created this infographic to celebrate the entrepreneur, not only for their individual, quirky styles, but also for their contributions to the global economy.

Source: bizsugar.com

How it Works

***

***

Assessment

Are medical professionals the same or different today -OR- in the health 2.0 future?

MUCH MORE FOR DOCTORS: https://marcinkoassociates.com/welcome-medical-colleagues/

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product Details

 ***

DAILY UPDATE: Fiduciary Rule with Stock Market Earnings Week

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

For last the week, the NASDAQ Composite (^IXIC) rose more than 2% while the S&P 500 (^GSPC) popped more than 1.5%. The Dow Jones Industrial Average (^DJI) rose more than 1%, closing above 40,000 for the first time ever on Friday.

In the week ahead, highly anticipated earnings results from Nvidia (NVDA) are expected to be the key catalyst for markets. Results from Target (TGT), Palo Alto Networks (PANW), and Lowe’s (LOW) will also be closely tracked by investors.

The week is also expected to be quieter on the economic front, with updates on activity in the manufacturing and services sectors as well as the final reading of consumer sentiment for May on tap. Minutes from the Fed’s May meeting are also expected on Wednesday afternoon.

CITE: https://www.r2library.com/Resource

The rule, finalized last month by the Labor Department, requires investment advisers to provide “prudent, loyal, honest advice free from overcharges” and avoid recommendations that favor their interests at the expense of their clients. It also updates the definition of an investment advice fiduciary under the Employee Retirement Income Security Act (ERISA) and Internal Revenue Code. 

Under the new definition, a fiduciary includes any financial services provider who offers investment advice to a retirement investor for a fee and who claims to be acting as a fiduciary or who a reasonable investor understands to be a trusted adviser acting in their best interest. The update removes the requirement that fiduciaries provide advice on a regular basis, bringing one-time advice under the rule. The Biden administration has argued that the previous definition, which was written in 1975, is outdated and has not kept pace with changes to the retirement landscape. 

CITE: https://tinyurl.com/2h47urt5

And, confidence in the U.S. dollar has waned, as forecasts suggest that a dip in inflation might allow the Federal Reserve to slash interest rates. With a notable 5% climb earlier this year, the dollar is now bracing for its first loss of 2024, triggered by a promising inflation report.

CITE: https://tinyurl.com/tj8smmes

Finally, fourteen of the world’s 20 largest stock markets have hit all-time highs recently, including England, Japan, Brazil, India, and Canada, according to Bloomberg. In the USA, the S&P 500 (also at a record) hasn’t dropped more than 2% in a trading session in 311 days, the longest streak in five years.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

PODCAST: Medicare Launched the First VBC Initiative 40 Years Ago!

****

See the source image

BY DR. ERIC BRICKER MD

***

Value-Based Care Happened 40 Years

Why Was Medicare Able to Bring About So Much Value-Based Payment Change in 3 Years (’83-’86) Compared to the Relatively Little Change That Has Occurred in the 11 Years Since the Affordable Care Act?

Watch the Video to Find Out.

YOUR COMMENTS ARE APPRECIATED.

Thank You

***

PODCAST: Healthcare Start-Up Accelerators and Incubators

By Dr. Eric Bricker MD

***

***
MORE: https://medicalexecutivepost.com/2017/04/02/on-digital-health-accelerator-and-corporate-start-up-programs/

COMMENTS APPRECIATED

Thank You

***

***

***

DAILY UPDATE: Jerome Powell, DJIA, Reddit and Life Insurance

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Young adults are delaying life insurance purchases due to financial constraints and a preference for spending on immediate experiences. The insurance industry is responding with digital-first strategies and more flexible products.

CITE: https://www.r2library.com/Resource

The DJIA closed above 40,000 for the first time after briefly crossing the milestone the day before and clinching its fifth winning week. Reddit shot up after announcing a partnership with OpenAI that lets the AI train on your posts and gives Reddit advertising dollars and the ability to use the tech to make new tools.

But, GameStop stock plunged after the recently reinvigorated meme stock filed to sell 45 million new shares and revealed that sales were down last quarter.

CITE: https://tinyurl.com/2h47urt5

Jerome Powell, chair of the Federal Reserve has tested positive for Covid. But the economy needn’t worry because he’s working from home.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

RE-BROADCAST: An Interview with Fiduciary Bennett Aikin AIF®

On Financial Fiduciary Accountability

[By Dr. David E. Marcinko MBA MEd CMP™]

[By Ann Miller; RN, MHA]

Currently, there is a growing dilemma in the financial sales and services industry. It goes something like this:

  • What is a financial fiduciary?
  • Who is a financial fiduciary?
  • How can I tell if my financial advisor is a fiduciary?

Now, in as much as this controversy affects laymen and physician-investors alike, we went right to the source for up-to-date information regarding this often contentious topic, for an email interview and Q-A session, with Ben Aikin.ben-aikin

About Bennett Aikin AIF® and fi360.com

Bennett [Ben] Aikin is the Communications Coordinator for fi360.com. He oversees all communications for fi360. His responsibilities include messaging, brand management, copyrights and trademarks, and publications. Mr. Aikin received his BA in English from Virginia Tech in 2003 and is currently an MS candidate in Journalism from Ohio University.

Q. Medical Executive Post 

You have been very helpful and gracious to us. So, let’s get right to it, Ben. In the view of many; attorneys, doctors, CPAs and the clergy are fiduciaries; most all others who retain this title seem poseurs; sans documentation otherwise.

A. Mr. Aikin

You are correct. Attorneys, doctors and clergy are the prototype fiduciaries. They have a clear duty to put the best interests of their clients, patients, congregation, etc., above their own. [The duty of a CPA isn’t as clear to me, although I believe you are correct]. Furthermore, this is one of the first topics we address in our AIF training programs, and what we call the difference between a profession and an industry.  The three professions you name have three common characteristics that elevate them from an industry to a profession:

  1. Recognized body of knowledge
  2. Society depends upon practitioners to provide trustworthy advice
  3. Code of conduct that places the clients’ best interests first

Q. Medical Executive Post 

It seems that Certified Financial Planner®, Chartered Financial Analysts, Registered Investment Advisors and their representatives, Registered Representative [stock-brokers] and AIF® holders, etc, are not really financial fiduciaries, either by legal statute or organizational charter. Are we correct, or not? Of course, we are not talking ethics or morality here. That’s for the theologians to discuss.

A. Mr. Aikin

One of the reasons for the “alphabet soup”, as you put it in one of your white papers [books, dictionaries and posts] on financial designations, is that while there is a large body of knowledge, there is no one recognized body of knowledge that one must acquire to enter the financial services industry.  The different designations serve to provide a distinguisher for how much and what parts of that body of knowledge you do possess.  However, being a fiduciary is exclusively a matter of function. 

In other words, regardless of what designations are held, there are five things that will make one a fiduciary in a given relationship:

  1. You are “named” in plan or trust documents; the appointment can be by “name” or by “title,” such as CFO or Head of Human Resources
  2. You are serving as a trustee; often times this applies to directed trustees as well
  3. Your function or role equates to a professional providing comprehensive and continuous investment advice
  4. You have discretion to buy or sell investable assets
  5. You are a corporate officer or director who has authority to appoint other fiduciaries

So, if you are a fiduciary according to one of these definitions, you can be held accountable for a breach in fiduciary duty, regardless of any expertise you do, or do not have. This underscores the critical nature of understanding the fiduciary standard and delegating certain duties to qualified “professionals” who can fulfill the parts of the process that a non-qualified fiduciary cannot.

Q. Medical Executive Post 

How about some of the specific designations mentioned on our site, and elsewhere. I believe that you may be familiar with the well-known financial planner, Ed Morrow, who often opines that there are more than 98 of these “designations”? In fact, he is the founder of the Registered Financial Consultants [RFC] designation. And, he wrote a Foreword for one of our e-books; back-in-the-day. His son, an attorney, also wrote as a tax expert for us, as well. So, what gives?

A. Mr. Aikin

As for the specific designations you list above, and elsewhere, they each signify something different that may, or may not, lend itself to being a fiduciary: For example:

• CFP®: The act of financial planning does very much imply fiduciary responsibility.  And, the recently updated CFP® rules of conduct does now include a fiduciary mandate:

• 1.4 A certificant shall at all times place the interest of the client ahead of his or her own. When the certificant provides financial planning or material elements of the financial planning process, the certificant owes to the client the duty of care of a fiduciary as defined by CFP Board. [from http://www.cfp.net/Downloads/2008Standards.pdf]

•  CFA: Very dependent on what work the individual is doing.  Their code of ethics does have a provision to place the interests of clients above their own and their Standards of Practice handbook makes clear that when they are working in a fiduciary capacity that they understand and abide by the legally mandated fiduciary standard.

• FA [Financial Advisor]: This is a generic term that you may find being used by a non-fiduciary, such as a broker, or a fiduciary, such as an RIA.

• RIA: Are fiduciaries.  Registered Investment Advisors are registered with the SEC and have obligations under the Investment Advisers Act of 1940 to provide services that meet a fiduciary standard of care.

• RR: Registered Reps, or stock-brokers, are not fiduciaries if they are doing what they are supposed to be doing.  If they give investment advice that crosses the line into “comprehensive and continuous investment advice” (see above), their function would make them a fiduciary and they would be subject to meeting a fiduciary standard in that advice (even though they may not be properly registered to give advice as an RIA).

• AIF designees: Have received training on a process that meets, and in some places exceeds, the fiduciary standard of care.  We do not require an AIF® to always function as a fiduciary. For example, we allow registered reps to gain and use the AIF® designation. In many cases, AIF designees are acting as fiduciaries, and the designation is an indicator that they have the full understanding of what that really means in terms of the level of service they provide.  We do expect our designees to clearly disclose whether they accept fiduciary responsibility for their services or not and advocate such disclosure for all financial service representatives.

Q. Medical Executive Post 

Your website, http://www.fi360.com, seems to suggest, for example, that banks/bankers are fiduciaries. We have found this not to be the case, of course, as they work for the best interests of the bank and stockholders. What definitional understanding are we missing?

A. Mr. Aikin

Banks cannot generally be considered fiduciaries.  Again, it is a matter of function. A bank may be a named trustee, in which case a fiduciary standard would generally apply.  Banks that sell products are doing so according to their governing regulations and are “prudent experts” under ERISA, but not necessarily held to a fiduciary standard in any broader sense.

Q. Medical Executive Post 

And so, how do we rectify the [seemingly intentional] industry obfuscation on this topic. We mean, our readers, subscribers, book and dictionary purchasers, clients and colleagues are all confused on this topic. The recent financial meltdown only stresses the importance of understanding same.

For example, everyone in the industry seems to say they are the “f” word. But, our outreach efforts to contact traditional “financial services” industry pundits, CFP® practitioners and other certification organizations are continually met with resounding silence; or worse yet; they offer an abundance of parsed words and obfuscation but no confirming paperwork, or deep subject-matter knowledge as you have kindly done. We get the impression that some FAs honesty do-not have a clue; while others are intentionally vague.

A. Mr. Aikin

All of the evidence you cite is correct.  But that does not mean it is impossible to find an investment advisor who will manage to a fiduciary standard of care and acknowledge the same. The best way to rectify confusion as it pertains to choosing appropriate investment professionals is to get fiduciary status acknowledged in writing and go over with them all of the necessary steps in a fiduciary process to ensure they are being fulfilled. There also are great resources out there for understanding the fiduciary process and for choosing professionals, such as the Department of Labor, the SEC, FINRA, the AICPA’s Personal Financial Planning division, the Financial Planning Association, and, of course, Fiduciary360.

We realize the confusion this must cause to those coming from the health care arena, where MD/DO clearly defines the individual in question; as do other degrees [optometrist, clinical psychologist, podiatrist, etc] and medical designations [fellow, board certification, etc.]. But, unfortunately, it is the state of the financial services industry as it stands now.

Q. Medical Executive Post 

It is as confusing for the medical community, as it is for the lay community. And, after some research, we believe retail financial services industry participants are also confused. So, what is the bottom line?

A. Mr. Aikin

The bottom line is that lay, physician and all clients have a right to expect and demand a fiduciary standard of care in the managing of investments. And, there are qualified professionals out there who are providing those services.  Again, the best way to ensure you are getting it is to have fiduciary status acknowledged in writing, and go over the necessary steps in a fiduciary process with them to ensure it is being fulfilled.

Q. Medical Executive Post 

The “parole-evidence” rule, of contract law, applies, right? In dealing with medical liability situations, the medics and malpractice attorneys have a rule: “if it wasn’t written down, it didn’t happen.”  

A. Mr. Aikin

An engagement contract accepting fiduciary status should trump a subsequent attempt to claim the fiduciary standard didn’t apply. But, to reiterate an earlier point, if someone acts in one of the five functional fiduciary roles, they are a fiduciary whether they choose to acknowledge it or not.  I have attached a sample acknowledgement of fiduciary status letter with copies of our handbook, which details the fiduciary process we instruct in our programs, and our SAFE, which is basically a checklist that a fiduciary should be able to answer “Yes” to every question to ensure the entire fiduciary process is being covered.

Q. Medical Executive Post 

It is curious that you mention checklists. We have a post arguing that very theme for doctors and hospitals as they pursue their medial error reduction, and quality improvement, endeavors. And, we applaud your integrity, and wish only for clarification on this simple fiduciary query?

A. Mr. Aikin

Simple definition: A fiduciary is someone who is managing the assets of another person and stands in a special relationship of trust, confidence, and/or legal responsibility.

Q. Medical Executive Post 

Who is a financial fiduciary and what, if any, financial designation indicates same?

A. Mr. Aikin

Functional definition: See above for the five items that make you a fiduciary.

Financial designations that unequivocally indicate fiduciary duty: Short answer is none, only function can determine who is a fiduciary. 

Q. Medical Executive Post 

Please repeat that?

A. Mr. Aikin

Financial designations that indicate fiduciary duty: none. It is the function that determines who is a fiduciary.  Now, having said that, the CFP® certification comes close by demanding their certificants who are engaged in financial planning do so to a fiduciary standard. Similarly, other designations may certify the holder’s ability to perform a role that would be held to a fiduciary standard of care.  The point is that you are owed a fiduciary standard of care when you engage a professional to fill that role or they functionally become one.  And, if you engage a professional to fill a non-fiduciary role, they will not be held to a fiduciary standard simply because they have a particular designation.  One of the purposes the designations serve is to inform you what roles the designation holder is capable of fulfilling.

It is also worth keeping in mind that just being a fiduciary doesn’t equate to a full knowledge of the fiduciary standard. The AIF® designation indicates having been fully trained on the standard.

Q. Medical Executive Post 

Yes, your website mentions something about fiduciaries that are not aware of same! How can this be? Since our business model mimics a medical model, isn’t that like saying “the doctor doesn’t know he is doctor?” Very specious, with all due respect!

A. Mr. Aikin

I think it is first important to note that this statement is referring not just to investment professionals.  Part of the audience fi360 serves is investment stewards, the non-professionals who, due to facts and circumstances, still owe a fiduciary duty to another.  Examples of this include investment committee members, trustees to a foundation, small business owners who start 401k plans, etc.  This is a group of non-sophisticated investors who may not be aware of the full array of responsibilities they have. 

However, even on the professional side I believe the statement isn’t as absurd as it sounds.  This is basically a protection from both ignorant and unscrupulous professionals.  Imagine a registered representative who, either through ignorance or design, begins offering comprehensive and continuous investment advice.  Though they may deny or be unaware of the fact, they have opened themselves up to fiduciary liability. 

Q. Medical Executive Post 

Please clarify the use of arbitration clauses in brokerage account contracts for us. Do these disclaim fiduciary responsibility? If so, does the client even know same?

A. Mr. Aikin

By definition, an engagement with a broker is a non-fiduciary relationship.  So, unless other services beyond the scope of a typical brokerage account contract are specified, fiduciary responsibility is inherently not applicable.  Unfortunately, I do imagine there are clients who don’t understand this. Furthermore, AIF® designees are not prohibited from signing such an agreement and there are some important points to understand the reasoning.

First, by definition, if you are entering into such an agreement, you are entering into a non-fiduciary relationship. So, any fiduciary requirement wouldn’t apply in this scenario.

Second, if this same question were applied into a scenario of a fiduciary relationship, such as with an RIA, this would be a method of dispute resolution, not a practice method. So, in the event of dispute, the advisor and investor would be free to agree to the method of resolution of their choosing. In this scenario, however, typically the method would not be discussed until the dispute itself arose.

Finally, it is important to know that AIF/AIFA designees are not required to be a fiduciary. It is symbolic of the individuals training, knowledge and ongoing development in fiduciary processes, but does not mean they will always be acting as a fiduciary.

Q. Medical Executive Post 

Don’t the vast majority of arbitration hearings find in favor of the FA; as the arbitrators are insiders, often paid by the very same industry itself?

A. Mr. Aikin

Actual percentages are reported here: http://www.finra.org/ArbitrationMediation/AboutFINRADR/Statistics/index.htm However, brokerage arbitration agreements are a dispute resolution method for disputes that arise within the context of the securities brokerage industry and are not the only means of resolving differences for all types of financial advisors.  Investment advisers, for example, are subject to respond to disputes in a variety of forums including state and federal courts.  Clients should look at their brokerage or advisory agreement to see what they have agreed to. If you wanted to go into further depth on this question, we would recommend contacting Brian Hamburger, who is a lawyer with experience in this area and an AIFA designee. Bio page: http://www.hamburgerlaw.com/attorneys/BSH.htm.

Q. Medical Executive Post 

What about our related Certified Medical Planner® designation, and online educational program for financial advisors and medical management consultants? Is it a good idea – reasonable – for the sponsor to demand fiduciary accountability of these charter-holders? Cleary, this would not only be a strategic competitive advantage, but advance the CMP™ mission to put medical colleagues first and champion their cause www.CertifiedMedicalPlanner.org above all else. 

A. Mr. Aikin

I think it is a good idea for any plan sponsor to demand fiduciary status be acknowledged from anyone engaged to provide comprehensive and continuous investment advice.  I also think it is a good idea to be proactive in verifying that the fiduciary process is being followed.

Q. Medical Executive Post 

Is there anything else that we should know about this topic?

A. Mr. Aikin

Yes, a further note about fi360’s standards. I wrote generically about the fiduciary standard, because there is one that is defined by multiple sources of regulation, legislation and case law.  The process defined in our handbooks, we call a Fiduciary Standard of Excellence, because it covers that minimum standard and also best practice standards that go above and beyond.  All of our Practices, which comprise that standard, are legally substantiated in our Legal Memoranda handbook, which was written by Fred Reish’s law firm, who is considered a leading ERISA attorney.

Additional resources:

Q. Medical Executive Post 

Thank you so much for your knowledge and willingness to frankly share it with the Medical-Executive-Post.

Assessment

All are invited to continue the conversation with Mr. Aikin, asynchronously online, or thru this contact information:

fi360.com
438 Division Street
Sewickley, PA 15143
412-741-8140 Phone
866-390-5080 Toll-free phone
412-741-8142 Fax

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

HOSPITALS: http://www.crcpress.com/product/isbn/9781466558731
CLINICS: http://www.crcpress.com/product/isbn/9781439879900
ADVISORS: www.CertifiedMedicalPlanner.org
BLOG: www.MedicalExecutivePost.com

Product DetailsProduct DetailsProduct Details

Product Details  Product Details

Product DetailsProduct Details

Product Details

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

What is the Eisenhower Matrix?

What is the Eisenhower Matrix?

[By staff reporters]

The Eisenhower Matrix is a business management and strategic planning productivity tool that helps to sort tasks and spread them reasonably over time.

The sort out is based on the principals of urgency and importance. When assigned to each task, those two factors place the task to the relevant quadrant of the matrix.

After this routine is done, it’s enough to take a look at the matrix to visually estimate what you should start with.

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Book Marcinko: https://medicalexecutivepost.com/dr-david-marcinkos-bookings/

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, IT, business and policy management ecosystem.

HOSPITALS

***

Product DetailsProduct Details

DAILY UPDATE: Top Causes of Death, Narcan Saves Lives but Scientific Research Fraudulent as DJIA Tops 40,000

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Walgreens has released its own brand of naloxone, a medication that reverses the effects of an opioid overdose. Available online now, Walgreens Brand Naloxone HCl Nasal Spray comes with two doses for $34.99, about $10 cheaper than the name-brand version, Narcan. The over-the-counter medication will also be available in stores by the end of May in the pain aisle, according to a press release, making the life-saving nasal spray more accessible.

***

Here’s where the major benchmarks ended:

  • The S&P 500 index rose 6.17 points (0.1%) to 5,303.27, up 1.5% for the week; the Dow Jones Industrial Average gained 134.21 points (0.3%) to 40,003.59, up 1.2% for the week; the NASDAQ Composite® ($COMP) lost 12.35 points (0.1%) to 16,685.97, up 2.1% for the week.
  • The 10-year Treasury note yield (TNX) rose more than 4 basis points to 4.42%, down about 8 basis points for the week.
  • The CBOE Volatility Index® (VIX) fell 0.43 to 11.99.

Among major companies, Nvidia (NVDA) dropped 2% Friday but still posted a 2.9% advance for the week ahead of the semiconductor leader’s quarterly earnings Wednesday. Among sectors, energy shares led gainers behind a 1% jump in WTI Crude Oil (/CL) futures. The small-cap Russell 2000® Index (RUT) ended little changed but still gained 1.7% for the week.

CITE: https://www.r2library.com/Resource

Fraudulent research papers have cost scientific journal publishers millions in lost revenue. (the Wall Street Journal)

CITE: https://tinyurl.com/2h47urt5

The 10 Top Causes of Adult Death in the U.S.A.

1.  Heart disease 267.2* 2.  Cancer 142.3 3.  Unintentional injuries 64.0 4.  COVID-19 44.5 5.  Stroke 39.5 6.  Chronic lower respiratory disease 34.3 7.  Alzheimer disease 28.9 8.  Diabetes 24.1  9   Kidney disease 13.8 10. Chronic liver disease and cirrhosis 13.8 Deaths per 100,000 population.

Source: Jeffrey Bendix, Medical Economics [5/15/24]

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

SUBMITTED ESSAYS: Economics, Management and Finance from Advisors to Physicians

By Staff Reporters

SPONSOR: http://www.MARCINKOASSOCIATES.com

Finance, economics and management essays of most current interest to all physicians and healthcare professionals

READ ESSAYS: https://marcinkoassociates.com/articles-essays/

Check back periodically for practical updates. Our catalogue library of major books, texts, case models and dictionaries is suggested for additional financial, economic, business and medical practice management information and education.

COMMENTS APPRECIATED

Thank You

***

***

***

PHYSICIANS BEWARE: Traditional Financial Planning “Rules of Thumb”

DOCTORS AND MEDICAL PROFESSIONALS BEWARE?

We ARE Different!

SPONSOR: http://MarcinkoAssociates.com

By Dr. David E. Marcinko MBA CMP®

SPONSOR: http://www.CertifiedMedicalPlanner.org

CMP logo

***

  • While financial planning rules of thumbs are useful to people as general guidelines, they may be too oversimplified in many situations, leading to underestimating or overestimating an individual’s needs. This may be especially true for physicians and many medical professionals. Rules of thumb do not account for specific circumstances or factors occurring at a particular time, or that could change over time, which should be considered for making sound financial decisions.
  • Great Health Industry Resignation: https://medicalexecutivepost.com/2021/12/12/healthcare-industry-hit-with-the-great-resignation-retirement/

For example, in a tight job market, an emergency fund amounting to six months of household expenses does not consider the possibility of extended unemployment. I’ve always suggested 2-3 years for doctors. Venture capitalist lay-offs of physicians during the pandemic confirm this often criticized benchmark opinion of mine.

As another example, buying life insurance based on a multiple of income does not account for the specific needs of the surviving family, which include a mortgage, the need for college funding and an extended survivor income for a non-working spouse. Again a huge home mortgage, or several children or dependents, may be the financial bane of physician colleagues and life insurance.

CITE: https://www.r2library.com/Resource/Title/082610254

***

EXAMPLES: Old/New Rules

  • A home purchase should cost less than an amount equal to two and a half years of your annual income. I think physicians in practice for 3-5 years might go up to 3.5X annual income; ceteras paribus.
  • Save at least 10-15% of your take-home income for retirement. Seek to save 20% or more.
  • Have at least five times your gross salary in life insurance death benefit. Consider 10X this amount in term insurance if young, and/or with several children or other special circumstances.
  • Pay off your highest-interest credit cards first. Agreed.
  • The stock market has a long-term average return of 10%. Agreed, but appreciated risk adjusted rates of return..
  • You should have an emergency fund equal to six months’ worth of household expenses. Doctors should seek 2-3 years.
  • Your age represents the percentage of bonds you should have in your portfolio. Risk tolerance and assets may be more vital.
  • Your age subtracted from 100 represents the percentage of stocks you should have in your portfolio. Risk tolerance and assets may still be more vital.
  • A balanced portfolio is 60% stocks, 40% bonds. With historic low interest rates, cash may be a more flexible alternative than bonds; also avoid most bond mutual funds as they usually never mature.

There are also rules of thumb for determining how much net worth you will need to retire comfortably at a normal retirement age. Here is the calculation that Investopedia uses to determine your net worth:

Compensation in the Physician Specialties: Mostly Stable - NEJM  CareerCenter Resources

RULES 72, 78 and 115: https://medicalexecutivepost.com/2022/01/30/the-rules-of-72-78-and-115/

INVITATION: https://medicalexecutivepost.com/2021/05/08/invite-dr-marcinko-to-your-next-big-event/

***

COMMENTS ARE APPRECIATED

Thank You

Subscribe to the Medical Executive-Post

***

FINANCE: https://www.amazon.com/Comprehensive-Financial-Planning-Strategies-Advisors/dp/1482240289/ref=sr_1_1?ie=UTF8&qid=1418580820&sr=8-1&keywords=david+marcinko

***

DAILY UPDATE: Core CPI and ERISA while Markets Remain High with Walmart Up

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Here’s where the major benchmarks ended:

America’s oldest popular stock index, the Dow Jones Industrial Average, hit a brief record high yesterday morning when it traded above 40,000, reflecting renewed hope for the market’s health after Wednesday’s promising inflation report.

  • The S&P 500® index (SPX) fell 11.05 points (0.2%) to 5,297.10; the Dow Jones Industrial Average declined 38.62 points (0.1%) to 39,869.38; the NASDAQ Composite® ($COMP) shed 44.07 points (0.3%) to 16,698.32.
  • The 10-year Treasury note yield (TNX) rose more than 2 basis points to 4.381%.
  • The CBOE Volatility Index® (VIX) dropped 0.03 to 12.42.

Walmart’s strength fueled a strong day for consumer staples shares. The S&P 500 Consumer Staples ($SP500#30), which includes Walmart as well as companies like Coca-Cola (KO) and Procter & Gamble (PG), surged 1.5% to its highest level in over two years. 

Among other companies, Applied Materials (AMAT) fell 1.6% ahead of the semiconductor industry supplier’s quarterly earnings report, which is expected after Thursday’s close.

CITE: https://www.r2library.com/Resource

And, Core CPI, which tracks the price of goods and services excluding volatile food and energy prices and is closely watched as an inflation indicator, rose 3.6% from the same period last year. That’s the smallest annual increase since April 2021. On a monthly basis, core CPI rose 0.3%, marking the first time in six months that its growth slowed from the prior month. Other good signs include:

  • Grocery prices dropped 0.2% from March, the first decrease in a year.
  • Health insurance and car insurance increased more slowly in April than in March.
  • A separate report released yesterday showed consumer spending stayed steady last month.

CITE: https://tinyurl.com/2h47urt5

Finally, Joe Manchin (D-W.Va.) and a group of Republican senators are moving to overturn a retirement investment planning rule that was finalized by the Labor Department last month. The Labor Department unveiled the new rule last month that would update the definition of an investment advice fiduciary under the Employee Retirement Income Security Act. Manchin and 15 Republican senators joined in co-sponsoring a Congressional Review Act (CRA) resolution that would overturn this new rule.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

REIMBURSEMENT: Valuation of Accountable Care Organizations

By Health Capital Consultants, LLC

***


Valuation of Accountable Care Organizations: Reimbursement

The U.S. healthcare payment and delivery system is increasingly moving to a value- and quality-based system. Accountable care organizations (ACOs) are at the forefront of delivering high-quality and cost-effective care to millions of Medicare beneficiaries and privately insured patients, incentivized by substantial shared savings for those who increase quality while containing costs.

CITE: https://www.r2library.com/Resource

This third installment of a five-part series on the valuation of ACOs will discuss the reimbursement environment in which ACOs participate.(Read more…) 

COMMENTS APPRECIATED

Thank You

***

***

***

HOSPITALS: https://www.amazon.com/Financial-Management-Strategies-Healthcare-Organizations/dp/1466558733/ref=sr_1_3?ie=UTF8&qid=1380743521&sr=8-3&keywords=david+marcinko
***

DAILY UPDATE: Healthcare Monopolies, Ark Invest and the Stock Markets Mega Rally

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

More people are interested in determining their “heart age” using new tests and tech tools, but some skeptics say it’s not a healthy data point to focus on. (the Wall Street Journal)

CITE: https://www.r2library.com/Resource

The Cathie Wood-led Ark Invest just made some significant trades. The most prominent among them were the increased stakes in Palantir Technologies Inc (NYSE:PLTR) and the reduced holdings in Coinbase Global Inc (NASDAQ: COIN).

Here’s where the major benchmarks ended:

  • The S&P 500 index rose 61.47 points (1.2%) to 5,308.15; the Dow Jones Industrial Average added 349.89 points (0.9%) to 39,908.00; the NASDAQ Composite rallied 231.21 points (1.4%) to 16,742.39.
  • The 10-year Treasury note yield fell almost 10 basis points to 4.348%.
  • The CBOE Volatility Index® (VIX) dropped 0.97 to 12.45.

Chipmaker shares led the way higher Wednesday, lifting the Philadelphia Semiconductor Index (SOX) almost 3% to a 10-week high. Interest-rate-sensitive sectors like real estate and utilities were also strong. The small-cap Russell 2000® Index (RUT) advanced 1.1% to a seven-week high. The U.S. Dollar Index ($DXY) slumped to its weakest level in five weeks, reflecting expectations for lower interest rates that may reduce the appeal of U.S. fixed income assets.

Among companies, Cisco Systems (CSC) surged 1.5% ahead of its quarterly results expected after Wednesday’s close. Dow member Walmart (WMT) is expected to release results Thursday morning as the unofficial retail earnings season accelerates. 

CITE: https://tinyurl.com/2h47urt5

And The U.S. Department of Justice (DOJ) announced it has established a new task force to take on healthcare monopolies and collusion. The task force, made up of prosecutors, economists, healthcare industry experts and others, will guide the division’s enforcement strategy and policy approach in healthcare, including by facilitating policy advocacy, investigations and, where warranted, civil and criminal enforcement in healthcare markets.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

CUSTOMIZABLE e-PODIATRY CONSENT FORMS Now Available for 2024

Electronically CUSTOMIZABLE FOR EVERY FOOT / ANKLE / LEG SURGEON

***

http://www.ePodiatryConsentForms.com

CUSTOMIZABLE CMS & AGENCY FOR HEALTHCARE RESEARCH AND QUALITY STYLED PROTOCOLS, CHECKLISTS AND TEMPLATES

.… Specifically for Podiatrists ….   

e-Podiatry Consent Forms™ is an innovative new suite of software programs from the Institute of Medical Business Advisors [iMBA, Inc]. Our products solve your informed consent problems and enhance the education, discussion and documentation of the informed consent process for all podiatrists performing foot, ankle and leg reconstructive surgical procedures.

THE PROBLEM

All podiatrists are being pressured by the Centers for Medicare and Medicaid Services [CMS], the Joint Commission on Accreditation of Healthcare Organizations [JCAHO], liability carriers and private insurance payers to make their consent process more patient-friendly, informed and easily understood. And, the pressure to standardize and comply is great.

Most recently, based on the need to make healthcare even safer, the Agency for Healthcare Research and Quality (AHRQ) undertook a major study to identify patient safety issues and develop recommendations for “best practices”.

The AHRQ Evidence Report

The AHRQ report identified the challenge of addressing shortcomings such as missed, incomplete or not fully comprehended informed consent, as a significant patient safety issue and opportunity for improvement.

The authors of the AHRQ report hypothesized that better informed patients:

“are less likely to experience errors by acting as another layer of protection.”

And, the AHRQ study ranked a “more interactive informed consent process” among the top 11 practices supporting more widespread implementation; especially for surgical consent forms.

THE SOLUTION

Why Us: https://epodiatryconsentforms.com/why-us/

One answer to the modern risk-management problem of “informed consent interactivity” may be e-Podiatry Consent Forms™  We license two core interactive surgical products, and a reference library, with related concepts and products in development:

  • Forefoot, Mid-Foot and Simple Rear-Foot Version
  • Complex Rear-Foot, Ankle and Lower Leg Version
  • Comprehensive content library for extreme customization.

Each e-Podiatry Consent Forms™ CD-ROM [secure email delivery is now available] is increasingly trusted as the simple solution to standardized communications across the entire office-enterprise; from managing-risk, informing-patients and complying with modern regulatory requirements through enhanced patient-centric informed consent encounters.

Thus, by improving the consistency, details, documentation and effectiveness of the informed consent process, e-Podiatry Consent Forms™ equips all podiatric surgeons with the tools needed to augment quality standards, reduce litigation potential and improve patient outcomes and safety.

http://www.ePodiatryConsentForms.com

***

ORDER NOW: MarcinkoAdvisors@msn.com

DELIVERY: By email only

***

PODIATRY PREP: Pass All Your Board Certification Examinations in 2024

Celebrating 30 Years of Your Success!

***

Engineers at MIT want to optimize your jog. Some of the brightest minds in math and science have created a predictive model that can tell you what kind of shoe you would run best in. The model assesses a person’s height, weight, and leg length to simulate their gait in sneakers of different materials and mid-soles. It then projects the optimal shoe based on which one produces the most efficient running form (i.e., which uses as little energy as possible per stride).

And so, as 3D printing and related tech continue to drive sneaker innovation, the researchers say their model will be beneficial to designers who want to create new kinds of highly functional kicks (Adidas funded some of the research).

Why? Marketing and product sales, of course. But, some experts suggest improved shoes might increase your running away speed by 8-10% while reducing injuries.

***

pod_prep_text

Pass ALL the Certification Boards!

By: http://www.PodiatryPrep.org

The Foot and Ankle Research Consortium, Inc. (FARC) is the leading publisher of Podiatric educational software. Since 1992, we have been producing the most effective and innovative method of preparing for ALL the Podiatry Board Examinations.

CURIOUS STUDY: Hallux Valgus Met I

SCARF: scarf osteotomy

This includes: The American Board of Podiatric Surgery, The American Board Of Podiatric Orthopedics and Primary Podiatric Medicine, the American Podiatric Medical Specialties Board, ABLES and the PMLexis. (Now includes the latest information for all Board Re-Certifications).

CONTENTS: https://podiatryprep.org/compatibility-test/

Customization and private  tutoring services also available.

FAN CLUB: https://podiatryprep.org/podiatryprep-fan-club/

doctor_pass2

PURCHASE – PREPARE – PASS®

ORDER HERE: https://podiatryprep.org/order-form/

GOOD LUCK!

Thank You

BUSINESS: https://www.amazon.com/Business-Medical-Practice-Transformational-Doctors/dp/0826105750/ref=sr_1_9?ie=UTF8&qid=1448163039&sr=8-9&keywords=david+marcinko

***

CAN: Doctor-Patient Intimacy be Electronic?

e Communication Tales from the Treatment Room

dem-2

By Dr. David Edward Marcinko MBA MEd CMP®

www.CertifiedMedicalPlanner.org

Today’s electronic media makes physician-patient communication possible; yet there is another kind of intimacy. ICTs—information and communication technologies—enable 24/7 monitoring of basic information such as blood pressure, glucose levels, pulse, and respiration, etc.

Example:

In one study, an ICT not only made it easier for patients to stay in touch with their doctors, the outcomes were also significantly better.[i] Today, Hippocrates is no longer trailing patients around the house to keep track of their snacks and moods. But Hippocrates has gone digital in the form of a wearable device that records subtle changes in biological markers and communicates them instantaneously to a health provider.

While this is obviously a great advance, we suggest you pause for a moment before plugging in.

Why?

ICTs and social media tools can make a difference to one of the most important dimensions—physiological outcomes. But you can have the latest interactive technology at your disposal and still fail to be connected.

Example:

A story that a friend told me shows how.

***

One morning, her elderly father was touching up the paint on his sailboat. Nearby, another boat-owner, who happened to be an emergency medical technician, noticed her father was struggling to breathe and that his lips had turned purple. A trip to the local community hospital led to a barrage of high-tech tests and procedures, a diagnosis of emphysema, later complications with cerebral hematomas, and hospitalizations and re-hospitalizations that brought him into contact with a neurologist, a neurosurgeon, a cardiologist, and a pulmonologist.

Throughout her father’s medical ordeal, the team of specialists stayed in touch with each other and the primary care physician via various electronic media. But one person remained out of the loop—her father. One day, six months into the experience, the primary care physician phoned our friend’s mother to check on his patient. Her father recalls thinking, “Why was he calling her?”

The physician was communicating, but he was emotionally disconnected.

***

The Moral

The moral of the story: communication needs to be patient-centered in both electronic and psychological terms. That means understanding how someone likes to communicate and making sure the medium fits the message. Electronic media are just part of the equation. The other is the doctor-patient relationship. Once a relationship is established, it may be fine to use e-mail to send information about dosage.

But, delivering a new diagnosis may require the extra effort of scheduling a phone call or a face-to-face visit. Today, since you have so many Health 2.0 choices, it takes some effort to select the right way to communicate in a particular situation.

Use the Right Relationship Strategy

A colleague recently shared another story about an encounter with a specialist.

Example:

***

After an examination for a minor ailment, he was told that there might be a medicated lotion that could ameliorate his condition. The doctor thought for a moment, then swiveled around to the computer on his desk. As our colleague watched the screen, his physician typed a few words into a search engine. Up popped a list and he wrote out a script. “Try this,” his doctor concluded. “I think it will help.”

It did, almost overnight.

***

The Moral

Even though his physical problem had disappeared completely, our colleague felt there was something missing in the interaction. “It bothered me that my doctor turned to the Web for help at that moment. He found a cure, but I felt he wasn’t paying attention to me.”

The physician is supposed to be an authority who has a special relationship to the patient. “Anybody can Google,” our colleague complained. Was he being unreasonable? Maybe.

But; this story tells us something important about technology—it cuts both ways.

***

aahnofx

***

Assessment

Everyone has their own preferences when it comes to how they want to interact with each other and with technology. If these preferences are explicit and aligned, the chances for a productive partnership are high. The preferences, however, are many and complex. You can easily get lost in the tangled thicket of interpersonal styles and virtual mediums.

In the Web 2.0 environment, it helps to narrow down the endless choices to just a few options.

MORE: Is Text Messaging being Overlooked as an Engagement Tool in Healthcare?

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[i] Hanson, William M. The Edge of Medicine: The Technology That Will Change Our Lives. New York, NY: Palgrave Macmillan, 2008.

Product DetailsProduct Details

***

DAILY UPDATE: Squarespace, Ark Invest & Hospitals as the Markets Rebound

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Here’s where the major benchmarks ended:

  • The S&P 500® index (SPX) rose 25.26 points (0.5%) to 5,246.68, the highest since a record close March 28; the Dow Jones Industrial Average® ($DJI) gained 126.60 points (0.3%) to 39,558.11; the NASDAQ Composite climbed 122.94 points (0.8%) to 16,511.18.
  • The 10-year Treasury note yield (TNX) fell more than 3 basis points to 4.449%.
  • The CBOE Volatility Index® (VIX) decreased 0.18 to  13.42.

Among companies, Home Depot’s (HD) quarterly results reported earlier Tuesday kicked off the unofficial start of the retail earnings season. The home improvement retailer’s earnings topped expectations, but revenue missed forecasts, initially sending the company’s shares down sharply. 

Home Depot also reaffirmed its full-year guidance for a 1% decline in comparable-store sales and a 1% increase in total sales. The company’s shares bounced back to end with a 0.1% loss.

CITE: https://www.r2library.com/Resource

And, the Cathie Wood-led Ark Invest just made some significant trades. The most prominent among them were the increased stakes in Palantir Technologies Inc (NYSE PLTR) and the reduced holdings in Coinbase Global Inc (NASDAQ: COIN).

Moreover, the website-building platform Squarespace is to go private, which it announced it’ll be doing in an all-cash deal with Permira, a private equity firm. Squarespace, which was public for nearly three years, joins a group of other smaller tech companies like Qualtrics that have recently pulled themselves off the public market. (CNBC)

CITE: https://tinyurl.com/2h47urt5

Employers and private insurers are paying hospitals more for inpatient and outpatient services than in previous years, a study from RAND Corporation finds. The American Hospital Association dismissed the report saying it offers a “skewed and incomplete picture.”


And finally … Kaiser Permanente began its 2024 earnings season with more than $2.7 billion in net income and $935 million in operating income, just months after sharing plans to lay off workers.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

Physician Electronic-Mail Bills

MY CHART”

By AMANDA SEITZ

***

***

E-Mailing your Physician may Cost You like Your Attorneys!

***

WASHINGTON (AP) — The next time you message your doctor to ask about a pesky cough or an itchy rash, you may want to check your bank account first — you could get a bill for the question.

Hospital systems around the country are rolling out fees for some messages that patients send to physicians, who they say are spending an increasing amount of time poring over online queries, some so complex that they require the level of medical expertise normally dispensed during an office visit. Patient advocates, however, worry these new fees may deter people from reaching out to their doctor and that they add another layer of complexity to the U.S. health care system’s already opaque billing process.

“This is a barrier that denies access and will result in hesitancy or fear to communicate and potentially harm patients with lower quality of care and outcomes at a much higher cost,” said Cynthia Fisher, the founder of Patient Rights Advocate, a Massachusetts-based nonprofit that pushes for hospital price transparency.

CITE: https://www.r2library.com/Resource/Title/082610254

The explosion of telehealth over the last three years — driven by the COVID-19 outbreak and relaxed federal regulations for online care — prompted many doctors to adopt more robust telecommunication with their patients. Consultations that once happened in an office were converted to computer or smart phone visits. And health care systems invited patients to use new online portals to message their doctors with a question at any time, American Medical Association president Jack Resneck Jr. told The Associated Press.
“When people figured out this is cool and could improve care, you saw hospitals and practice groups saying to patients, welcome to your portal … you can ping your physician with questions if you want,” Resneck said. “We found ourselves as physicians getting dozens and dozens of these a day and not having time built in to do that work.”

The charges vary for each patient and hospital system, with messages costing as little as $3 for Medicare patients to as much $160 for the uninsured. In some cases, the final bill depends on how much time the doctor spends responding.

READ HERE: https://my.clevelandclinic.org/online-services/mychart/messaging#msdynttrid=bAU8cKe-602S6wFIwSYop1KQswRcT2b2F5mRJ-92OEc

***

COMMENTS APPRECIATED

Thank You

***

ORDER: https://www.amazon.com/Dictionary-Health-Information-Technology-Security/dp/0826149952/ref=sr_1_5?ie=UTF8&s=books&qid=1254413315&sr=1-5

***

ORDER: https://www.amazon.com/Dictionary-Health-Insurance-Managed-Care/dp/0826149944/ref=sr_1_4?ie=UTF8&s=books&qid=1275315485&sr=1-4

***

PODCAST: Hospital Price Transparency Website

BILLY EATS MEDICAL BILLS

By Eric Bricker MD

***

***

COMMENTS APPRECIATED

Thank You

***

***

***

PODCAST: Early Retirement and Health Insurance

By Staff Reporters

***

***

COMMENTS APPRECIATED

Thank You

***

ORDER: https://www.amazon.com/Dictionary-Health-Insurance-Managed-Care/dp/0826149944/ref=sr_1_4?ie=UTF8&s=books&qid=1275315485&sr=1-4

***

DAILY UPDATE: Moderna Down with Mixed Markets

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 20224

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

***

Here’s where the major benchmarks ended:

  • The S&P 500® index (SPX) fell 1.26 points (0.02%) to 5,221.42; the Dow Jones Industrial Average lost 81.33 points (0.2%) to 39,431.51; the NASDAQ Composite® ($COMP) gained 47.37 points (0.3%) to 16,388.24.
  • The 10-year Treasury note yield (TNX) dropped almost 2 basis points to 4.487%.
  • The CBOE Volatility Index® (VIX) surged 1.05 to 13.60.

Biotechnology and food and beverage shares were among the market’s strongest sectors Monday, while communication services stocks were among the biggest laggards. Energy shares took pressure despite a jump of 1.2% in WTI Crude Oil (/CL) futures, which ended above $79 per barrel after slumping last week to two-month lows.

CITE: https://www.r2library.com/Resource

Moderna is “bleeding money” as its forthcoming RSV vaccine doesn’t appear to deliver better results than other RSV shots already on the market. (Bloomberg)

***

It’s ChatGPT-4o’s time to shine. The “o” stands for omni, and it’s the latest iteration of OpenAI’s signature chatbot. According to the company, it’s much faster with enhanced “capabilities across text, vision, and audio.”

CITE: https://tinyurl.com/2h47urt5

23% is the average portion of the bill hospitals collected from patients before treatment in Q1 of this year, up 3% YoY. (the Wall Street Journal)

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msns.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***