BOARD CERTIFICATION EXAM STUDY GUIDES Lower Extremity Trauma
[Click on Image to Enlarge]
ME-P Free Advertising Consultation
The “Medical Executive-Post” is about connecting doctors, health care executives and modern consulting advisors. It’s about free-enterprise, business, practice, policy, personal financial planning and wealth building capitalism. We have an attitude that’s independent, outspoken, intelligent and so Next-Gen; often edgy, usually controversial. And, our consultants “got fly”, just like U. Read it! Write it! Post it! “Medical Executive-Post”. Call or email us for your FREE advertising and sales consultation TODAY [678.779.8597] E-mail: MarcinkoAdvisors1738@outlook.com
Medical & Surgical e-Consent Forms
ePodiatryConsentForms.com
iMBA Inc., OFFICES
Suite #5901 Wilbanks Drive, Norcross, Georgia, 30092 USA [1.678.779.8597]. Our location is real and we are now virtually enabled to assist new long distance clients and out-of-town colleagues.
ME-P Publishing
SEEKING INDUSTRY INFO PARTNERS?
If you want the opportunity to work with leading health care industry insiders, innovators and watchers, the “ME-P” may be right for you? We are unbiased and operate at the nexus of theoretical and applied R&D. Collaborate with us and you’ll put your brand in front of a smart & tightly focused demographic; one at the forefront of our emerging healthcare free marketplace of informed and professional “movers and shakers.” Our Ad Rate Card is available upon request [678-779-8597].
Posted on April 12, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
Paradox of Prosperity
“A paradox of prosperity is revealed and shown to be stable in the cycles of economic advancement between generations. I would put the matter this way: If one accepts, for example, that Mr. Brokaw’s ‘Greatest Generation’ were characterized by prudence, diligence, and patriotism in deed rather than word, that very generation produced its opposite in the generation that followed it. That is to say, I have found it repeated across the ages and across cultures, that the more diligent a previous generation, as a natural propensity, the more licentious the generation that follows. Invariably therefore, the generation that exhibits the more cogent properties of character for the best sort of citizenship fails to produce a generation of the same or similar characteristics.”
***
***
“Paradox of Prosperity” was applied as a term of analysis in the recent New York Times, Wall Street Journal bestseller Rescue America: Our best America is only one generation away (published October 2011), which Professor Morris co-authored with Chris Salamone. There the inter-generational breakdown is given a fuller exposition. Morris, who has been a careful reader of Thorstein Veblen, particularly Veblen’s masterpiece The Theory of the Leisure Class, says his own advancement of this inter-generational thesis was influenced by Veblen. “I think”, says Morris, “Veblen gave some insight as to what is produced in the generation which follows one such as Tom Brokaw described. The Greatest Generations – if by that we mean a generation characterized by prudence and sacrifice – nearly always produces a generation which can be characterized as a leisure class. They consume without manufacturing. They project feelings over principles. In general terms, they lack a spirit of sacrifice because they abhor the notion of “Objective Values” and so lack the will to re-create or advance the social ethos created by their parent’s generation.” In cultural terms, the generation that followed the “Greatest Generation” were the baby boomers (essentially, the children of the Greatest Generation between 1945–1965). The “Boomers” fit the classic definition of a “leisure class”, which Veblen described as being characterized by Conspicuous Consumption. To quote their description of their leisure class “they move values toward behavior, rather than behavior toward values”.
Posted on April 11, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
On Differences and Similarities
By David K. Luke; MIM CMP
The difference between internal marketing and external marketing for physicians is that internal marketing is the management strategy of improving satisfaction by making patients aware of the positive differences in the physician’s practice –versus- other modern or traditional alternatives that the doctor might externally use [yellow pages, coupons, TV, radio, internet, blogs, etc].
Now, compare marketing with advertising, which attempts to draw patients to the medical practice or clinic using more expensive channel distribution means and/or media messaging.
The “X” Factor
Internal marketing gives the patient “something extra” during the visit that tends to make them pleased, satisfied – or better yet – delighted!
In show business, Simon Cowell calls this something extra the “X” factor.
Whether it is a “Patient Bill of Rights” or just making sure that patients are treated fairly, and with respect throughout the process, turns the patient into a practice advocate instead of a patient from hell.
Improved listening/communication can come in the form of an attentive and caring human ear, enhanced bedside manner, or technology like P[C]RM (Patient {Client} Relationship Management) tools and/or eMRs, for example.
Sloppy Medical Office Procedures
Having office staff involved, by noticing improvements, can also help with the implementation of a successful internal marketing strategy. Sloppy office procedures can be cleaned up, scheduling access management can be revamped, and any administrative mix-ups can be avoided.
Negative practices such as “we enforce a minimum $50 office visit fee” should be stopped, as this casts a negative attitude on all patients, not just future deadbeats.
An effective P[C] RM strategy can increase patient satisfaction and be inexpensive to implement and maintain, especially in light of modern advertising tools for medical practices.
Financial Advisor Comparisons
A physician’s internal marketing program is comparative to an FA’s internal marketing program, in that both methods are much more cost effective and yield better results than traditional external marketing or advertising.
For an FA, the practice of encouraging referrals can be done discreetly without making the existing clients uncomfortable.
An FA practice that is “referable” is one in which there are consistent standards and procedures in place. This creates a comfort factor with existing clients and assures them that when they refer their friends and family they will also receive consistent quality treatment.
Assessment
An FA can implement procedures similar to a medical practice by training staff to point out and recognize office procedures that might be improved. Letting clients know they are appreciated and that referrals are accepted sounds like obvious advice, but is often ignored by too many Financial Advisors, and even doctors.
Editor’s Note: David K. Luke is currently enrolled in the online www.CertifiedMedicalPlanner.org chartered professional designation program.
Conclusion
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on April 11, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
MEDICAL EXECUTIVE-POST– Today’sNewsletter
***
Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants
“Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily“
A Partner of the Institute of Medical Business Advisors , Inc.
NEW YORK (Reuters) -The U.S. accounting watchdog on Wednesday said it has hit KPMG Netherlands with a $25 million civil penalty, a record for the regulator, in response to “egregious” and widespread exam cheating at the foreign affiliate of the major audit firm.
As millions of Americans approach age 66, they face the inevitable question, is it time to retire? The physician population is aging alongside the general population—more than 40% of physicians in the U.S. will be 65 years or older within the next decade. In the case of surgeons, there is little guidance on how to best ensure their competency throughout their career and at the same time maintain patient safety while preserving mature physician dignity.
It is a scenario playing out nationwide. From Oregon to Pennsylvania, hundreds of communities have in recent years either stopped adding fluoride to their water supplies or voted to prevent its addition. Supporters of such bans argue that people should be given the freedom of choice. The broad availability of over-the-counter dental products containing the mineral makes it no longer necessary to add to public water supplies, they say. The Centers for Disease Control and Prevention says that while store-bought products reduce tooth decay, the greatest protection comes when they are used in combination with water fluoridation.
More health systems are going to be opting out of Medicare Advantage (MA) plans, George Hill, a managing director at Deutsche Bank in Boston, predicted Monday at a “Wall Street Comes to Washington” webinar hosted by the Brookings Institution. “I think you’re going to see more large provider organizations threaten to opt out of networks, particularly as it relates to MA,” Hill said, adding that there are a number of reasons for this. “Prior authorizations are the problem, claims denials are a huge problem, delayed payments and rates are the problem — barriers in access to care in all varieties are the problem.”
The latest budget update from the nonpartisan Congressional Budget Office (CBO) found that the federal government has spent more on paying interest on the national debt than on the military in fiscal year 2024. The CBO’s budget report for March showed that the U.S. has spent $412 billion on military programs at the Department of Defense through the first half of FY-2024, according to preliminary figures from CBO and the Treasury Department.
Consumer price increases remained high last month, boosted by gas, rents, and car insurance, the government said Wednesday in a report that will likely give pause to the Federal Reserve as it weighs when and by how much to cut interest rates this year. Prices outside the volatile food and energy categories rose 0.4% from February to March, the same accelerated pace as in the previous month. Measured from a year earlier, these core prices were up 3.8%, unchanged from the year-over-year rise in February. The Fed closely tracks core prices because they tend to provide a good read of where inflation is headed.
Here’s where the major benchmarks ended:
The S&P 500® index (SPX) dropped 49.27 points (1.0%) to 5,160.64; the Dow Jones Industrial Average lost 422.16 points (1.1%) to 38,461.51; the NASDAQ Composite® ($COMP) fell 136.28 points (0.8%) to 16,170.36.
The 10-year Treasury note yield (TNX) soared more than 18 basis points to 4.548%.
The CBOE Volatility Index® (VIX) jumped 0.82 to 15.80.
Interest-rate-sensitive sectors like banks, real estate, and utilities led Wednesday’s decliners. The KBW Regional Bank Index (KRX) tumbled 5% to its lowest point since late November. The small-cap Russell 2000® Index (RUT) lost 2.5%. Energy shares were among the few gainers as WTI Crude Oil (/CL) futures rebounded after three-straight losing sessions.
In other markets, the U.S. dollar index (DXY) jumped 1% to a five-month high amid expectations interest rates will remain elevated.
Posted on April 10, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
Is Business Finally Embracing Medical Values?
[By Render S. Davis MHA CHE]
[By David Edward Marcinko MBA MEd]
In the evolutionary shifts in models for medical care, physicians have been asked to embrace business values of efficiency and cost effectiveness, sometimes at the expense of their professional judgment and personal values.
While some of these changes have been inevitable as our society sought to rein in out-of-control costs, it is not unreasonable for physicians to call on payers, regulators and other business parties to the health care delivery system to raise their ethical bar.
Tit-for-Tat
Harvard University physician-ethicist Linda Emmanuel noted that “health professionals are now accountable to business values (such as efficiency and cost effectiveness), so business persons should be accountable to professional values including kindness and compassion.”
***
[Medicine versus Business]
***
Assessment
Within the framework of ethical principles, John La Puma, M.D., wrote in Managed Care Ethics, that “business’s ethical obligations are integrity and honesty.
Medicine’s are those plus altruism, beneficence, non-maleficence, respect, and fairness.”
About the Author
Render Davis was a Certified Healthcare Executive, now retired from Crawford Long Hospital at Emory University, in Atlanta, GA He served as Assistant Administrator for General Services, Policy Development, and Regulatory Affairs from 1977-95. He is a founding board member of the Health Care Ethics Consortium of Georgia and served on the consortium’s Executive Committee, Advisory Board, Futility Task Force, Strategic Planning Committee, and chaired the Annual Conference Planning Committee, for many years.
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on April 10, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
Boeing had yet another rough day, at one point dropping 2.5% to its lowest mark in five months after reports that the FAA is investigating a whistleblower’s claims about safety issues with the 787 Dreamliner.
***
***
And, US stocks on Tuesday ended with small moves, weighed down by the financial sector ahead of key earnings reports later this week. Market participants also exhibited caution a day before the latest consumer inflation data. Wall Street’s three major averages opened in the green but then spent most of the day languishing in negative territory.
Finally, the tech-heavy NASDAQ Composite (COMP:IND) eventually closed 0.32% higher at 16,306.64 points, while the benchmark S&P 500 (SP500) added 0.15% to settle at 5,209.94 points. The blue-chip Dow (DJI) fell marginally by 0.02% to conclude at 38,883.67 points.
The S&P 500® index (SPX) gained 7.52 points (0.1%) to 5,209.91; the Dow Jones Industrial Average® ($DJI) lost 9.13 points (0.02%) to 38,883.67; the NASDAQ Composite® ($COMP) rose 52.68 points (0.3%) to 16,306.64.
The 10-year Treasury note yield (TNX) fell more than 6 basis points to 4.358%.
The CBOE Volatility Index® (VIX) fell 0.21 to 14.98.
Financial and industrial shares led Tuesday’s decliners. Oil services stocks were also soft as WTI Crude Oil (/CL) futures dropped for a third consecutive trading session. The Philadelphia Oil Service Index (OSX) lost 0.7% and ended at its lowest point since April 1.
In other markets, Gold (GC) futures neared $2,400 per ounce and hit a record high for the eighth consecutive trading session. Gold’s rally has been driven by factors including reports of purchases by China’s central bank as well as expectations for lower interest rates and escalating conflict in the Middle East. Bitcoin (BTC) tumbled about 3.5% and fell to less than $70,000, giving up much of Monday’s gain.
Posted on April 10, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
Medical Ethics – Ever on Guard
***
ByAaron Carroll MD, MS
***
I’m a doctor. My father is a doctor. My colleagues are doctors, the people I train are doctors, lots and lots of my friends are doctors.
***
But, that doesn’t meant that doctors sometimes aren’t blind to certain issues like their own financial conflicts of interest. Sometimes we have to poke doctors with a stick. That’s how we show our love.
***
Conflicts of interest are the topic of this Healthcare Triage video.
Dr. Carroll has published some of the seminal work on various types of health care reform, and continues to be a sought after speaker on cost, quality and access-and the Affordable Care Act and its implications for our future. Considered one of the leading pediatric informaticists in the U.S. he has received millions of dollars in grants to explore the use of information technology in health care. Dr. Carroll was the Primary Investigator on a grant from the Agency for Healthcare Research and Quality to study the true impact of malpractice claims on the practice of medicine.
Conclusion
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on April 10, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Physicians Received $12 Billion from Drug & Device Makers in Less Than 10 Years
A review of the federal Open Payments database found that the pharmaceutical and medical device industry paid physicians $12.1 billion over nearly a decade. Almost two thirds of eligible physicians — 826,313 doctors — received a payment from a drug or device maker from 2013 to 2022, according to a study published online in JAMA on March 28th. Overall, the median payment was $48 per physician.
Orthopedists received the largest amount of payments in aggregate, $1.3 billion, followed by neurologists and psychiatrists at $1.2 billion, and cardiologists at $1.29 billion. To find out what any physician was paid, click here.
Posted on April 9, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
Versus Di-Versification
BUSINESS MANAGEMENT: The term “diworsification” was coined by legendary investor Peter Lynch in his book, One up on Wall Street, to describe the over-expansion of a company into new growth projects and businesses they do not fully understand and which do not align with the company’s core competencies.
PORTFOLIO MANAGEMENT: The term diworsification has since grown to also refer to over-diversifying an investment portfolio in such a way that it reduces the overall risk-return characteristics.
Posted on April 9, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Like use, investors were a little checked out yesterday, focusing on the eclipse or maybe the fact that earnings season starts later this week, and stocks were relatively flat. Diamondback Energy hit an all-time high following several other energy companies that did so last week as oil prices surge.
Here’s where the major benchmarks ended:
The S&P 500® index (SPX) lost 1.95 points (0.04%) to 5,202.39; the Dow Jones Industrial Average® ($DJI) eased 11.24 points (0.03%) to 38,892.80; the NASDAQ Composite® ($COMP) gained 5.44 points (0.03%) to 16,253.96.
The 10-year Treasury note yield rose more than 4 basis points to 4.422%.
The CBOE Volatility Index® (VIX) fell 0.84 to 15.19.
Bank shares were among Monday’s strongest performers, sending the KBW Regional Banking Index (KRX) up 1.5%. Consumer discretionary companies were also strong. WTI Crude Oil (/CL) futures fell sharply earlier in the session following reports Israel had removed some troops from Gaza but bounced back to end down 0.5% at around $86.47 per barrel.
Posted on April 9, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Vitaliy Katsenelson, CFA ***
***
Something weird happened to me on Twitter a few months ago. A “follower” started lashing out at me about a stock we own. When people attack me for my views it doesn’t bother me (I wrote several chapters in Soul in the Game on this topic). I don’t let personal attacks get to me, unless people start attaching bricks to their 280 characters.
This person’s lambasting of me was different. He was upset about the decline of a stock I had never publicly discussed in any of my newsletters or talks. This person was not a client. I didn’t know who he was; I had never met him. I was really confused why a stock my clients and I personally owned was so important to him. It’s like someone being upset about the color my wife chose to paint our kitchen.
Once gently confronted, he apologized, said he was a big fan, and explained that he had read my 13F (a form we have to file with the SEC 45 days after the quarter end, where we have to report our holdings in US stocks). He saw that the stock was one of our top holdings, and he bought it. Because I owned it, he made it a disproportionately large position.
I was truly upset about this incident. One of my principles in life is to have a net positive impact on the people I touch. If every single stock I discussed only went straight up, I wouldn’t have to worry about it. But this is not how life works.
Posted on April 8, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
SAFE SOLAR ECLIPSE DAY
***
***
NVIDIA is accelerating the pace of healthcare innovation! Last week they unveiled a suite of AI microservices for developers, launched cutting-edge healthcare AI tools, and deepened their collaborations with giants like Johnson & Johnson. Plus, they’re ramping up investment in clinical trials and drug design.
Do you ever struggle with finding the best sources of information about healthcare AI? Check out my new video, where I share my favorite newsletters, websites, sub-reddits, and a list of must-follow experts. With this toolkit, you won’t miss anything important. Also, I hope you enjoyed a restful and Happy Spring Break – should you celebrate it!
Last week, several Fed officials said they were in no rush to slash interest rates in 2024, which investors have been banking on this year. Meanwhile, oil prices have risen to five-month highs due to concerns about supply shocks in key areas around the world.
And, Wall Street is preparing for a crammed week, with crucial inflation data dropping on Wednesday and big banks (JPMorgan, Wells Fargo, Citigroup) inaugurating earnings season on Friday. The pressure is on companies to post beefy profits to back up their strong stock performance in Q1.
On August 14, 2023, the Centers for Medicare and Medicaid Services (CMS) announced updates to their Accountable Care Organization Realizing Equity, Access, and Community Health (ACO REACH) model.
In response to feedback from stakeholders, starting in performance year (PY) 2024, the agency expects to increase the predictability for the model and further advance health equity. Only in its first PY, ACO REACH is a revision and replacement of the Global and Professional Direct Contracting (GPDC) model and the Geographic Direct Contracting (Geo Model) model, a subset of the GPDC model. This Health Capital Topics article will discuss the updates to the ACO REACH model and its implications for existing accountable care organizations (ACOs). (Read more…)
Posted on April 7, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
It’s not often a guy on a computer is the hero of the story. Andres Freund, a Microsoft developer, found a malicious backdoor in popular open-source software last week. Programmers scrambled to fix the problem but warned that if they hadn’t, it could have led to hundreds of millions of compromised devices and a catastrophic cybersecurity breach.
Freund told the New York Times that he first noticed an unusual error message while doing routine maintenance on the Linux operating system—a vital software used by banks, governments, and corporations around the globe. At first, he wrote it off, but a few weeks later, he noticed an application used to log into computers remotely was using a lot more power in the system than it was supposed to.
In a recent survey by Edelman Financial Engines, 57% of respondents said they’d feel wealthy if they had $1 million in the bank. But for many people, like doctors, that may not be enough.
Among those with $500,000 and $3 million in assets, 53% said it would take over $3 million in the bank for them to feel wealthy, and 33% said it would take over $5 million. Given that these are amounts some people will never even come close to amassing in their lifetimes, it may be hard to wrap your head around these answers.
Posted on April 7, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
Since 2013 – Americans believe they now need $1.46 million to retire in style
***
***
The new magic number for retirement, found in a study by Northwestern Mutual, is 15% higher than what people thought they needed last year—and 53% higher than the amount people in 2020 pictured themselves needing to feel comfortable leaving the workforce to sit on a beach in Florida.
In fact, it’s also more than most people have socked away: On average, US adults have $88,400 saved for retirement.
Written by doctors and healthcare professionals, this textbook should be mandatory reading for all medical school students—highly recommended for both young and veteran physicians—and an eliminating factor for any financial advisor who has not read it. The book uses jargon like ‘innovative,’ ‘transformational,’ and ‘disruptive’—all rightly so! It is the type of definitive financial lifestyle planning book we often seek, but seldom find. —LeRoy Howard MA CMPTM,Candidate and Financial Advisor, Fayetteville, North Carolina I taught diagnostic radiology for over a decade. The physician-focused niche information, balanced perspectives, and insider industry transparency in this book may help save your financial life. —Dr. William P. Scherer MS, Barry University, Ft. Lauderdale, Florida This book was crafted in response to the frustration felt by doctors who dealt with top financial, brokerage, and accounting firms. These non-fiduciary behemoths often prescribed costly wholesale solutions that were applicable to all, but customized for few, despite ever-changing needs. It is a must-read to learn why brokerage sales pitches or Internet resources will never replace the knowledge and deep advice of a physician-focused financial advisor, medical consultant, or collegial Certified Medical Planner™ financial professional. —Parin Khotari MBA,Whitman School of Management, Syracuse University, New York In today’s healthcare environment, in order for providers to survive, they need to understand their current and future market trends, finances, operations, and impact of federal and state regulations. As a healthcare consulting professional for over 30 years supporting both the private and public sector, I recommend that providers understand and utilize the wealth of knowledge that is being conveyed in these chapters. Without this guidance providers will have a hard time navigating the supporting system which may impact their future revenue stream. I strongly endorse the contents of this book.—Carol S. Miller BSN MBA PMP,President, Miller Consulting Group, ACT IAC Executive Committee Vice-Chair at-Large, HIMSS NCA Board Member This is an excellent book on financial planning for physicians and health professionals. It is all inclusive yet very easy to read with much valuable information. And, I have been expanding my business knowledge with all of Dr. Marcinko’s prior books. I highly recommend this one, too. It is a fine educational tool for all doctors.—Dr. David B. Lumsden MD MS MA,Orthopedic Surgeon, Baltimore, Maryland There is no other comprehensive book like it to help doctors, nurses, and other medical providers accumulate and preserve the wealth that their years of education and hard work have earned them. —Dr. Jason Dyken MD MBA,Dyken Wealth Strategies, Gulf Shores, Alabama I plan to give a copy of this book written ‘by doctors and for doctors’ to all my prospects, physician, and nurse clients. It may be the definitive text on this important topic. —Alexander Naruska CPA,Orlando, Florida
Health professionals are small business owners who need to apply their self-discipline tactics in establishing and operating successful practices. Talented trainees are leaving the medical profession because they fail to balance the cost of attendance against a realistic business and financial plan. Principles like budgeting, saving, and living below one’s means, in order to make future investments for future growth, asset protection, and retirement possible are often lacking. This textbook guides the medical professional in his/her financial planning life journey from start to finish. It ranks a place in all medical school libraries and on each of our bookshelves. —Dr. Thomas M. DeLauro DPM,Professor and Chairman – Division of Medical Sciences, New York College of Podiatric Medicine
Physicians are notoriously excellent at diagnosing and treating medical conditions. However, they are also notoriously deficient in managing the business aspects of their medical practices. Most will earn $20-30 million in their medical lifetime, but few know how to create wealth for themselves and their families. This book will help fill the void in physicians’ financial education. I have two recommendations: 1) every physician, young and old, should read this book; and 2) read it a second time! —Dr. Neil Baum MD,Clinical Associate Professor of Urology, Tulane Medical School, New Orleans, Louisiana
I worked with a Certified Medical Planner™ on several occasions in the past, and will do so again in the future. This book codified the vast body of knowledge that helped in all facets of my financial life and professional medical practice. —Dr. James E. Williams DABPS, Foot and Ankle Surgeon, Conyers, Georgia
This is a constantly changing field for rules, regulations, taxes, insurance, compliance, and investments. This book assists readers, and their financial advisors, in keeping up with what’s going on in the healthcare field that all doctors need to know. —Patricia Raskob CFP® EA ATA, Raskob Kambourian Financial Advisors, Tucson, Arizona I particularly enjoyed reading the specific examples in this book which pointed out the perils of risk … something with which I am too familiar and have learned (the hard way) to avoid like the Black Death. It is a pleasure to come across this kind of wisdom, in print, that other colleagues may learn before it’s too late— many, many years down the road. —Dr. Robert S. Park MD, Robert Park and Associates Insurance, Seattle, Washington
Although this book targets physicians, I was pleased to see that it also addressed the financial planning and employment benefit needs of nurses; physical, respiratory, and occupational therapists; CRNAs, hospitalists, and other members of the health care team….highly readable, practical, and understandable. —Nurse Cecelia T. Perez RN, Hospital Operating Room Manager, Ellicott City, Maryland
Personal financial success in the PP-ACA era will be more difficult to achieve than ever before. It requires the next generation of doctors to rethink frugality, delay gratification, and redefine the very definition of success and work–life balance. And, they will surely need the subject matter medical specificity and new-wave professional guidance offered in this book. This book is a ‘must-read’ for all health care professionals, and their financial advisors, who wish to take an active role in creating a new subset of informed and pioneering professionals known as Certified Medical Planners™. —Dr. Mark D. Dollard FACFAS, Private Practice, Tyson Corner, Virginia As healthcare professionals, it is our Hippocratic duty to avoid preventable harm by paying attention. On the other hand, some of us are guilty of being reckless with our own financial health—delaying serious consideration of investments, taxation, retirement income, estate planning, and inheritances until the worry keeps one awake at night. So, if you have avoided planning for the future for far too long, perhaps it is time to take that first step toward preparedness. This in-depth textbook is an excellent starting point—not only because of its readability, but because of his team’s expertise and thoroughness in addressing the intricacies of modern investments—and from the point of view of not only gifted financial experts, but as healthcare providers, as well … a rare combination. —Dr. Darrell K. Pruitt DDS, Private Practice Dentist, Fort Worth, Texas This text should be on the bookshelf of all contemporary physicians. The book is physician-focused with unique topics applicable to all medical professionals. But, it also offers helpful insights into the new tax and estate laws, fiduciary accountability for advisors and insurance agents, with investing, asset protection and risk management, and retirement planning strategies with updates for the brave new world of global payments of the Patient Protection and Affordable Care Act. Starting out by encouraging readers to examine their personal ‘money blueprint’ beliefs and habits, the book is divided into four sections offering holistic life cycle financial information and economic education directed to new, mid-career, and mature physicians.
This structure permits one to dip into the book based on personal need to find relief, rather than to overwhelm. Given the complexity of modern domestic healthcare, and the daunting challenges faced by physicians who try to stay abreast of clinical medicine and the ever-evolving laws of personal finance, this textbook could not have come at a better time. —Dr. Philippa Kennealy MD MPH, The Entrepreneurial MD, Los Angeles, California Physicians have economic concerns unmatched by any other profession, arriving ten years late to the start of their earning years. This textbook goes to the core of how to level the playing field quickly, and efficaciously, by a new breed of dedicated Certified Medical Planners™. With physician-focused financial advice, each chapter is a building block to your financial fortress. —Thomas McKeon, MBA, Pharmaceutical Representative, Philadelphia, Pennsylvania An excellent resource … this textbook is written in a manner that provides physician practice owners with a comprehensive guide to financial planning and related topics for their professional practice in a way that is easily comprehended. The style in which it breaks down the intricacies of the current physician practice landscape makes it a ‘must-read’ for those physicians (and their advisors) practicing in the volatile era of healthcare reform. —Robert James Cimasi, MHA ASA FRICS MCBA CVA CM&AA CMP™, CEO-Health Capital Consultants, LLC, St. Louis, Missouri Rarely can one find a full compendium of information within a single source or text, but this book communicates the new financial realities we are forced to confront; it is full of opportunities for minimizing tax liability and maximizing income potential. We’re recommending it to all our medical practice management clients across the entire healthcare spectrum. —Alan Guinn, The Guinn Consultancy Group, Inc., Cookeville, Tennessee Dr. David Edward Marcinko MBA CMP™ and his team take a seemingly endless stream of disparate concepts and integrate them into a simple, straightforward, and understandable path to success. And, he codifies them all into a step-by-step algorithm to more efficient investing, risk management, taxation, and enhanced retirement planning for doctors and nurses. His text is a vital read—and must execute—book for all healthcare professionals and physician-focused financial advisors. —Dr. O. Kent Mercado, JD, Private Practitioner and Attorney, Naperville, Illinois
Kudos. The editors and contributing authors have compiled the most comprehensive reference book for the medical community that has ever been attempted. As you review the chapters of interest and hone in on the most important concerns you may have, realize that the best minds have been harvested for you to plan well… Live well. —Martha J. Schilling; AAMS® CRPC® ETSC CSA, Shilling Group Advisors, LLC, Philadelphia, Pennsylvania I recommend this book to any physician or medical professional that desires an honest no-sales approach to understanding the financial planning and investing world. It is worthwhile to any financial advisor interested in this space, as well. —David K. Luke, MIM MS-PFP CMP™, Net Worth Advisory Group, Sandy, Utah Although not a substitute for a formal business education, this book will help physicians navigate effectively through the hurdles of day-to-day financial decisions with the help of an accountant, financial and legal advisor. I highly recommend it and commend Dr. Marcinko and the Institute of Medical Business Advisors, Inc. on a job well done. —Ken Yeung MBA CMP™, Tseung Kwan O Hospital, Hong Kong I’ve seen many ghost-written handbooks, paperbacks, and vanity-published manuals on this topic throughout my career in mental healthcare. Most were poorly written, opinionated, and cheaply produced self-aggrandizing marketing drivel for those agents selling commission-based financial products and expensive advisory services. So, I was pleasantly surprised with this comprehensive peer-reviewed academic textbook, complete with citations, case examples, and real-life integrated strategies by and for medical professionals. Although a bit late for my career, I recommend it highly to all my younger colleagues … It’s credibility and specificity stand alone. —Dr. Clarice Montgomery PhD MA,Retired Clinical Psychologist In an industry known for one-size-fits-all templates and massively customized books, products, advice, and services, the extreme healthcare specificity of this text is both refreshing and comprehensive. —Dr. James Joseph Bartley, Columbus, Georgia
My brother was my office administrator and accountant. We both feel this is the most comprehensive textbook available on financial planning for healthcare providers. —Dr. Anthony Robert Naruska DC,Winter Park, Florida
Posted on April 6, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Here’s where the major benchmarks ended:
Markets: Stocks pulled it out for a Friday win after the government dropped encouraging economic data. But all three major indexes were still down for the week, with the Dow enduring its worst of 2024.
Stock spotlight:Tesla took a wild ride, plunging after Reuters reported it had scrapped plans to produce its long-awaited Model 2 affordable EV only to regain some ground after Elon Musk denied it. The company then jumped after hours because Musk said it’ll debut a robotaxi on August 8.
The S&P 500 index gained 57.13 points (1.1%) to 5,204.34, down 1.0% for the week; the Dow Jones Industrial Average added 307.06 points (0.8%) to 38,904.04, down 2.3% for the week; the NASDAQ Composite® ($COMP) rose 199.44 points (1.2%) to 16,248.52, down 0.8% for the week.
The 10-year Treasury note yield (TNX) rose more than 8 basis points to 4.392%.
The CBOE Volatility Index® (VIX) fell 0.32 to 16.03.
Meta Platforms (META) and Netflix (NFLX), two members of the “Magnificent Seven” mega-cap group, both jumped around 3% Friday, helping lift the S&P 500 Communication Services Index ($SP500#50) 1.6% to lead top-performing sectors. Meta shares closed at a record above $527, up 49% for the year.
Posted on April 6, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
THE AMA A.U.I. REPORT
***
By Staff Reporters
Doctors are excited—yet cautious—about the role augmented intelligence (AUI) could play in the future of healthcare. That’s the takeaway from an American Medical Association (AMA) survey released last month.
About two-thirds (65%) of 1,000+ physicians that the AMA surveyed in August 2023 agreed that there was at least some advantage to using AUI-powered tools, particularly when it comes to diagnostic ability (72%), work efficiency (69%), and clinical outcomes (61%). More than half (56%) of doctors said AUI tools could best help address administrative burdens.
Posted on April 6, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Intel revealed that its semiconductor-making unit lost $7 billion last year. The news sent the company’s stock down.
And, Amazon is laying off hundreds of employees from its cloud computing division, including the team overseeing its cashierless tech (and not just the Just Walk Out feature it’s pulling from stores), as well as people sales and marketing roles.
Posted on April 5, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Ulta and other major beauty companies that thrived during the past few years of economic instability provided good fodder for the “lipstick index”—a duct-tape economic measure that assumes people still buy small indulgences (like lipstick) during tough times, keeping the beauty industry recession-proof.
However…it’s not. Ulta’s full-year sales growth target is just 4% to 5%, which falls below Wall Street’s estimates, and Estée Lauder announced in February it was laying off 3% to 5% of its workforce after some difficult months.
And, other consumer goods powerhouses are bracing for a slowdown, too. The parent company of Calvin Klein and Tommy Hilfiger said this week that it’s preparing for a 6% to 7% revenue drop this year.
The S&P 500 index dropped 64.28 points (1.2%) to 5,147.21; the Dow Jones Industrial Average® ($DJI) tumbled 530.16 points (1.4%) to 38,596.98; the NASDAQ Composite® ($COMP) sank 228.38 points (1.4%) to 16,049.08.
The 10-year Treasury note yield (TNX) fell more than 5 basis points to 4.303.%.
The CBOE Volatility Index® (VIX) surged 2.07 to 16.39.
Semiconductors were among Thursday’s weakest performers as a drop of more than 8% in Advanced Micro Devices (AMD) helped send the Philadelphia Semiconductor Index (SOX) down 3% to a two-week low. Retail shares were also soft. WTI Crude Oil futures rose for the sixth consecutive day and topped $87 per barrel, marking a gain of 4.3% so far this week. Volatility based on the VIX ended at its highest level since early November. Brent Crude Oil (/BZ) futures, the global benchmark, topped $90 for the first time since October.
Private equity and venture capital investments typically involve ownership of shares in a company and represent title to a portion of the company’s future earnings. However, private equity is an equity interest in a company or venture whose stock is not yet traded on a stock exchange.
Venture capital is typically a special case of private equity in which the investment is in a company or venture that has little financial history or is embarking on a high risk/high potential reward business strategy.
Like real estate, private equity and venture capital investments generally share a general lack of liquidity and a lack of comparability across different individual investments. The lack of liquidity comes from the fact that private equity and venture capital investments are typically not tradable on a stock exchange until the company has an IPO.
The lack of comparability is due to the fact that most private equity and venture capital investments are the result of direct negotiation between the investor/venture capitalist and the existing owners of the company /venture.
With widely divergent terms and provisions across different investments, it is difficult to make general claims regarding the characteristics of private equity and venture capital investments.
Posted on April 5, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Health Capital Consultants, LLC
On March 5th, 2024, the Department of Justice’s (DOJ’s) Antitrust Division, the Federal Trade Commission (FTC), and the Department of Health and Human Services (HHS), announced the launch of a multi-agency inquiry – in the form of a request for information (RFI) and public workshop – focusing on the increasing control of private equity (PE) and other corporations over the healthcare industry.
This Health Capital Topics article discusses the agencies recent actions and how it appears to be in line with the government’s recent moves to crack down on anti-competitive actions in healthcare. (Read more…)
The Institute of Medical Business Advisors Inc identified several reasons based on observations working with medical professional and physician clients over the years.
A late start
By the time doctors finish medical school and residency they’re typically in their middle or late thirties. Many have families to feed, and substantial student loans to pay off. It will be years before they can even start accumulating wealth. Consider that physicians typically enter careers at later ages, often with larger debts from training. Some specialties may not lead a case until 10 years of practice, and many specialties have limited longevity. Peak earning years may also be shorter for health care providers than other professionals. Financial survival skills are paramount for converting the limited earnings time period to personal financial security.
Challenging socio-political environment
It is increasingly challenging to practice medicine. With the Medicare Trust Fund slated to go bust in 2019, the Center for Medicare and Medicare Service (CMS) is increasingly resorting to cutting physician reimbursements and implementing capitation and bundled value based medical payments models. The medical reimbursement effects of the PP-ACA are not yet fully discerned; but appear to continue the decline in compensation. And to illustrate this potential governmental control, in what other industry can participants debate the simple question, “who is the customer?”
Lifestyle expectations
Society expects a doctor to live like a doctor, dress like a doctor, and drive like a doctor. Meeting social expectations can be quite expensive.
Time and energy
A doctor can’t be just a doctor any more. S/he also has to deal with ever increasing regulatory mandates, paperwork requirements by state and federal agencies and capricious insurance companies. It is estimated that for every hour spent on patient care, and additional half-hour is spent on paperwork. To-date, the use of electronic medical records has exacerbated; not ameliorated this problem. The demand on their time is mind-boggling. A typical doctor works a ten- to twelve-hour day. After work and family, they simply don’t have time and energy left to do comprehensive financial planning.
Financially naïve
Doctors are smart. They’re highly trained in their area of expertise. But, that doesn’t translate into understanding about finance or economics. Because they are smart, it’s easy for them to think they can easily master and execute concepts of personal financial planning, as well. Often, they don’t.
Lack of trust and delegation
Many doctors don’t trust financial advisors working for major Wall Street banks. They have the good instinct to realize that their interests are not aligned. Not knowing there are independent advisors out there who observe a strict fiduciary standard, they tend to do everything by themselves.
In fact, Paul Larson CFP®, President-CEO of the firm LARSON Financial Group LLC, noted a disquieting trend among physician client in his firm [personal communication]. Almost 90% of them fail to take care of their own family finances in a comprehensive manner; while only 10% are succeeding. The strategies in this chapter and book are common to their success.
Too Trusting
Another aspect of naivety, many physicians do not realize that the financial advisory industry lacks the same discipline and regulation that the average physician operates in. A primary care doctor would never even attempt a complicated surgery on a patient, but is trained to refer such patients to a specialist in the field with the proper training and experience. Financial Advisors often come from a sales background and are trained to keep a client in house even if the advisor is lacking in expertise. Also, many physicians are not trained to discern a qualified financial advisor from a sales person dressed up like a financial advisor. It is illegal to call yourself a physician in the United States unless you have the credentials to back it up; yet, anyone in the US can legally call themselves a financial advisor or a financial planner.
Posted on April 4, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Ulta Beauty plunged after its CEO revealed that, despite the resilience of the beauty category, sales have slowed.
And, Walt Disney’s current rulers will continue to oversee the kingdom. The company’s board, helmed by CEO Bob Iger,defeated activist investors and Nelson Peltz who had hoped to replace current board members and steer the company in a new direction.
Here’s where the major benchmarks ended:
The S&P 500 index rose 5.68 points (0.1%) to 5,211.49; the Dow Jones Industrial Average lost 43.10 points (0.1%) to 39,127.14; the NASDAQ Composite® ($COMP) added 37.01 points (0.2%) to 16,277.46.
The 10-year Treasury note yield fell more than 1 basis point to 4.351%.
The CBOE Volatility Index® (VIX) declined 0.28 to 14.33.
Energy shares remained one of the market’s strongest performers behind strength in WTI Crude Oil (/CL) futures, which rose a fifth consecutive day and ended above $85 per barrel, the highest since October. The Philadelphia Oil Service Index (OSX) jumped1.6%, extending its year-to-date gain to almost 14%.
Posted on April 4, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Bertalan Meskó, MDPhD
***
***
What are you going to do 10-20 years from now? We toyed with the idea and came up with a list of healthcare jobs we think will be born in the coming decades. In case you want to become an organ designer or an end-of-life therapist. OR telesurgery VR planner.
And before you say I’m looking too far into the future, let me remind you that researchers are experimenting with a computer made of DNA-coated microbeads, with wireless charging of electronic implants, an Osaka hospital uses smart glasses to connect remote teams, while the FDA cleared an A.I. software automatically flagging cases of pneumothorax.
I hope you will find the newsletter useful!
Best regards, Bertalan Meskó, MD PhD The Medical Futurist
Posted on April 3, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
DEFINITION: A safety net hospital is a type of medical center in the United States that by legal obligation or mission provides healthcare for individuals regardless of their insurance status or ability to pay. This legal mandate forces safety net hospitals to serve all populations. Such hospitals typically serve a proportionately higher number of uninsured, Medicaid, Medicare, Children’s Health Insurance Program, low-income, and other vulnerable individuals than their “non-safety net hospital” counterpart.
But, some Safety net hospitals will soon learn how the government plans to reimburse them for nearly $10 billion resulting from underpayments from the federal drug discount program. The question is whether it will come at the expense of other hospitals. The Centers for Medicare and Medicaid Services [CMS] is poised to reveal a repayment plan to facilities in the 340B program, after the Supreme Court found the agency made illegal program cuts from 2018 to September 2022.
Posted on April 3, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
Medicare Part C papers, glasses and stethoscope.
***
Humana and other managed-care stocks were down sharply in trading Tuesday after the Centers for Medicare and Medicaid Services announced an average 3.7% increase in revenue for Medicare Advantage plans in 2025. That amount is the same as the proposed increase the government had announced in January, but it came as a shock to investors who were hoping for a slight bump.
Humana (HUM) shares fell sharply in early Tuesday trading, while rivals UnitedHealth UNH and CVS Health (CVS) traded firmly in the red, as the health insurance industry received yet another blow to its 2024 profit forecasts. All three major health insurance groups have trailed the broader market this year, with Humana down nearly 25%, amid concern that profit margins will be hit by a surge in medical costs tied to a rise in elective procedures. Those procedures had been delayed by the Covid pandemic.
The S&P 500 index fell 37.96 points (0.7%) to 5,205.81; the Dow Jones Industrial Average lost 396.61 points (1.0%) to 39,170.24; the NASDAQ Composite slipped 156.38 points (1.0%) to 16,240.45.
The 10-year Treasury note yield was up almost 3 basis points to 4.357%.
The CBOE Volatility Index® (VIX) rose 0.96 to 14.61.
Retailer, biotechnology, and regional bank shares were among the weakest performers Tuesday, leading a broad market slump in which declining stocks outnumber advancers by a greater than three-to-one ratio. The small-cap Russell 2000® Index (RUT) lost 1.8% and settled at a two-week low.
Energy companies, by contrast, extended recent strength behind an ongoing climb in WTI Crude Oil (/CL) futures, which surpassed $85 per barrel for the first time since late October. The Philadelphia Oil Service Index (OSX) advanced 2.1% and ended at a 5-½-month high. Oil prices have surged this year due to OPEC production cuts and concern over supply disruptions stemming from the Middle East conflict.
Posted on April 3, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
PATIENT COMPLICATION RATES
By Staff Reporters
***
***
Hospitals under private equity (PE) ownership reported higher rates of patient complications when compared to other facilities, according to a recent JAMA study—raising questions about how the business model might affect staffing and subsequent quality of care.
The surveyed Medicare beneficiaries saw a 25.4% increase in “hospital-acquired conditions,” which the Centers for Medicare and Medicaid Services defines as falls, infections, and other adverse events, when they received treatment at a PE-acquired hospital compared to those run under other forms of ownership.
On the whole, the study found that Medicare enrollees at hospitals under PE control were not only younger and less likely to additionally qualify for Medicaid but also more likely to experience complications.
Posted on April 2, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
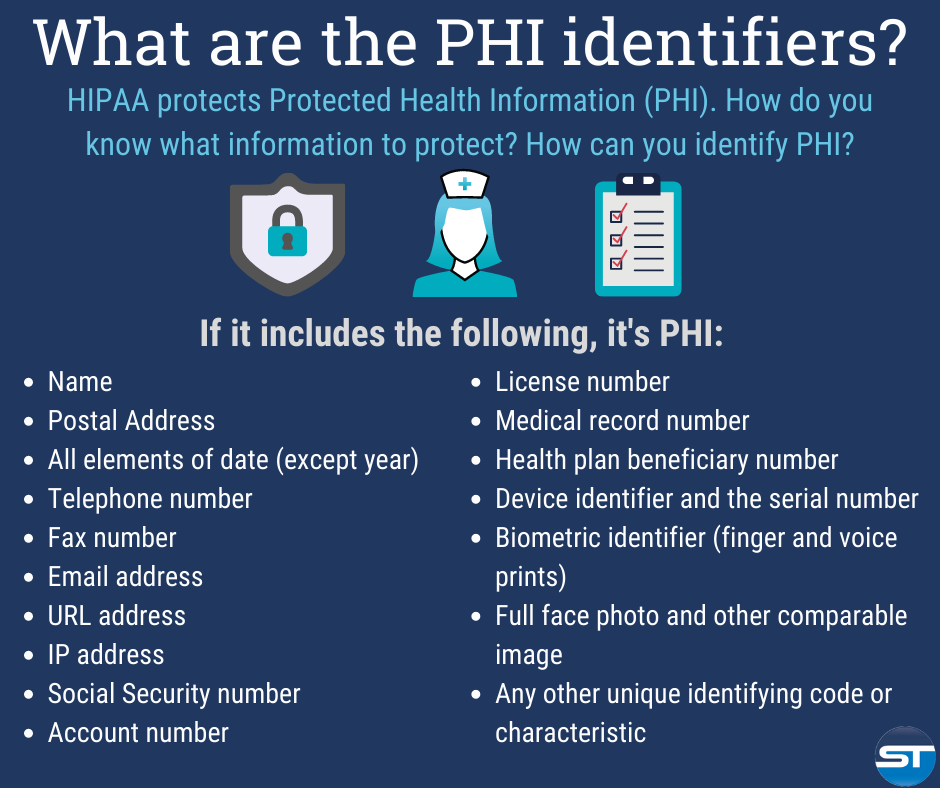
The Designated Medical Record Set [DMRS]: Contains medical and billing records and any other records that a physician, hospital, clinic and/or medical practice utilizes for making decisions about a patient; a hospital, emerging healthcare organization, or other healthcare organization. It serves to define which set of information comprises “protected health information” and which set does not; or contains medical or mixed billing records, and any other information that a physician and/or medical practice utilizes for making decisions about a patient.
It is up to the hospital or healthcare organization to define which set of information comprises “protected health information” and which does not though logically this should not differ from locale to locale. The patient has the right to know who in the lengthy data chain has seen their Protected Health Information. This sets up an audit challenge for the medical organization, especially if the accountability is programmed, and other examiners view the document without cause.
Posted on April 2, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Quote: “This is a very unusual situation. The stock is pretty much divorced from fundamentals.”—Jay Ritter, finance professor and IPO expert at the University of Florida, on the surging value of the newly public Trump Media. Truth Social,its only active product, has been shedding both users and cash. (CNN)
Shares of Truth Social owner Trump Media & Technology Group plunged Monday after the company disclosed that it lost more than $58 million and generated very little revenue in 2023. Former President Donald Trump is the company’s majority shareholder, and his net worth tumbled by more than $1 billion Monday as a result.
Stocks started Q2 off soft yesterday, as investors continued to fret about inflation. Stock spotlight: Trump Media, the newly public company that owns Truth Social, plunged yesterday after revealing that it lost $58 million last year, generated just $4.1 million in revenue, and had 10 times fewer users than Threads.
The S&P 500 index fell 10.58 points (0.2%) to 5,243.77; the Dow Jones Industrial Average® ($DJI) shed 240.52 points (0.6%) to 39,566.85; the NASDAQ Composite® ($COMP) added 17.37 points (0.1%) to 16,396.83.
The 10-year Treasury note yield jumped 13 basis points to 4.323%.
The CBOE Volatility Index® (VIX) rose 0.64 to 13.65.
Banks were among the market’s weakest performers Monday, likely reflecting concern that elevated interest rates could pinch margins. The KBW Regional Bank Index (KRX) sank 2% after ending at a two-month high last week. The small-cap Russell 2000® Index (RUT) was also soft, dropping 1% after closing at a two-year high last week.
Communication services and semiconductor shares turned in strong performances, as did energy, lifted by WTI Crude Oil (/CL) futures’ extending a rally to its highest level since late October. WTI Crude Oil is up almost 18% so far this year amid concern over supply disruptions stemming from the Russia-Ukraine war and Middle East conflict.
In other markets, the U.S. dollar index ($DXY) strengthened for the fourth straight day and reached its highest point since mid-November behind expectations the Fed will keep interest rates high.
Posted on April 2, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
What’s Your Back-up Plan – Doctor?
As per a recent study, 32% of data is lost by human errors. However hardware, software, hacks and smack-downs are responsible for remaining 68% data loss.
Data protection gains major importance in data loss. It can be achieved by implementing data management successfully.
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on April 2, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Federal health officials said they would offer emergency funding to physicians, physical therapists, and other professionals that provide outpatient healthcare, following a cyberattack that crippled the nation’s largest processor of medical claims and left many organizations in financial distress. The Centers for Medicare and Medicaid Services also announced that it would make advance payments available to suppliers that bill through Medicare Part B, which serves a wide array of healthcare organizations.
***
***
Officials had previously announced a similar program to make emergency payments available for hospitals that had been ensnared by the February 21st hack of Change Healthcare, a unit of UnitedHealth Group, and have struggled to get paid for more than two weeks. The emergency funds represent upfront payments made to healthcare providers and suppliers based on their expected future claims.
Posted on April 1, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
APRIL FOOL’S DAY
April Fools’ Day customs date back to at least Renaissance Europe, but it’s likely the tradition originated long before then. Some historians have linked April Fools’ Day to the ancient Roman festival of “Hilaria,” where at the end of March, people would come together to commemorate the resurrection of the god Attis. It was a celebration of renewal in which revelers would dress up in disguises and imitate others.
It’s also possible that the medieval celebration of the Feast of Fools, where a mock bishop or pope was elected and church customs were parodied, could have inspired the day.
***
***
Stocks had their best Q1 in five years. The S&P 500 ended Thursday—the last trading day of the quarter—up by more than 10%, marking its best start to a year since 2019.
The AI craze, record corporate profits, and optimism around cooling inflation are all contributing to the stock boom. The economy got more good news yesterday when theStocks had their best Q1 in five years reported that several key gauges, including GDP and consumer spending, grew in Q4 of last year.
And, that’s not all: Home sales bounced back after a January slump, jobless claims fell, and advertisers raised their full-year forecast. Consumer sentiment is now at its highest level since 2021.
Posted on April 1, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Health Capital Consultants, LLC
***
***
On March 9th, 2024, President Biden signed into law a $460 billion spending package to continue funding the federal government for the remainder of the 2024 fiscal year. Contained within the spending package was legislation to cut in half the 2024 Medicare physician payment update of approximately -3.4%.
This Health Capital Topics article discusses the payment update, other healthcare provisions contained in the bipartisan spending bills, and responses from stakeholders. (Read more…)
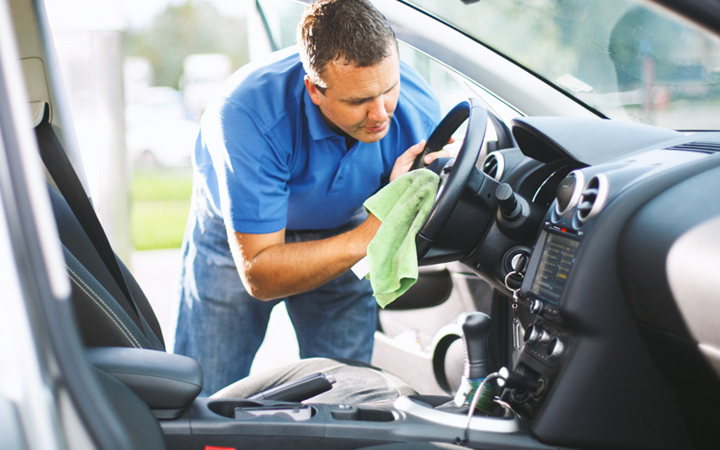
It’s never a source of pride stepping out of a dirty car or truck, especially for image conscious doctors. But, keeping your vehicle looking like new, for the doctor’s parking lot, is tough work. Sure, you may take it through the drive-thru car wash every now and then, but that isn’t the deep cleaning that your car deserves.
All in the Details
Detailing, on the other hand, is promised to give your beloved vehicle that ‘new-car’ feeling all over again. It isn’t easy work, but the results are amazing. While you could detail your car at home, is it really worth it? Let’s take a look at why letting the pros detail your vehicle is the way to go – or – not!
Working at the Car Wash
When you wash your vehicle at a drive-thru car wash, you may be doing more harm than good. If the car wash has brushes or pieces of cloth that scrub your vehicle as it goes through, these components can easily scratch your car’s finish. All of the bits of dirt from cars before can be trapped in the cloth and brushes, and as they scrub your vehicle, they act as sandpaper, permanently marring your paint.
One step better is hand washing your car at home, but even then, you must be careful to not just become a humanized version of the car wash. Using two buckets is a good start, with one bucket being a rinse bucket to remove the dirt from your sponge, and the other containing the soap.
SOAP Suds – Not SOAP Notes
Also, be careful of the type of soaps and car care products being used. The interior and exterior cleaners found at the local parts store are often of decent quality, but they aren’t always the best, and they must be used properly. Even then, for a normal car owner, detailing a car can become an all-day task, sometimes with less than perfect results.
Don’t forget to use a clay bar or brick followed by your favorite Carnuba wax, too.
The Pros
So, why should you let the pros handle your detailing needs? They should know exactly what specialty products are right for your vehicle to get the perfect results every time. And, they know the techniques that will yield showroom-finish results while you don’t have to even touch your car.
And, while you won’t want to clean out all the dried soda, coffee stains, or leftover cheeseburger wrappers from under your seat, they will gladly do it for you – for a price.
Imagine
Just picture getting into a blindingly shiny, clean vehicle with an interior that looks equally as pristine. No more purchasing all kinds of car care products that don’t deliver results. No more spending hours in the driveway getting soaked and frustrated. No more wasted time. Pros know what it takes to detail your vehicle to concourse standards.
But then, it is just a job for them. It is a labor of love for me. Am I neurotic or compulsive?
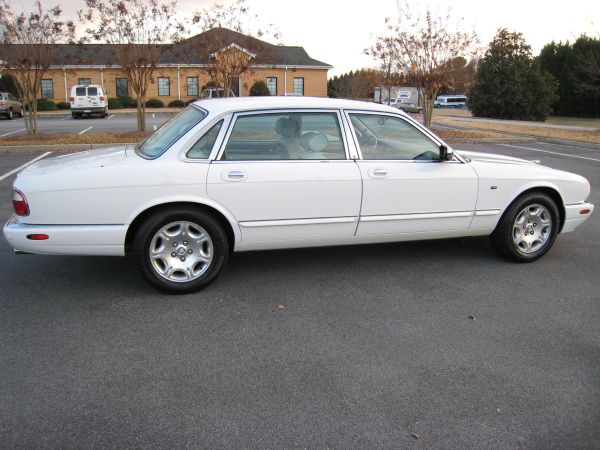
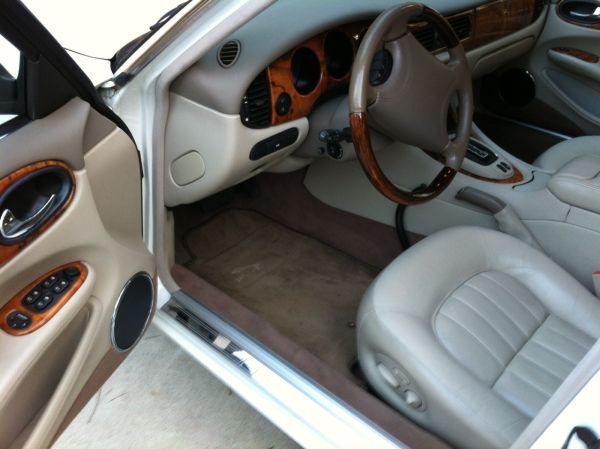
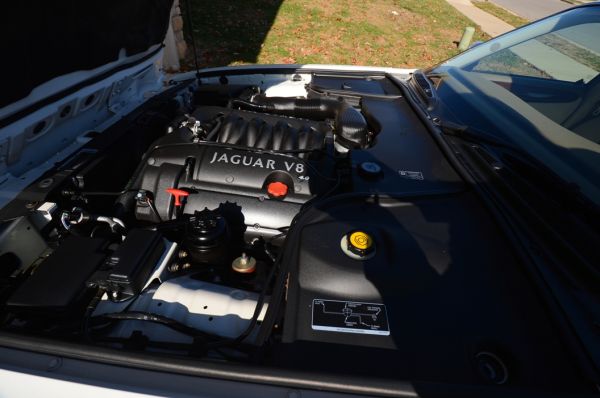
My near showroom and mint conditioned 2000 Jaguar XJ-V8-L is a full-size luxury sedan, offers sporting drive characteristics, mixed with a classic style and interior comfort. It was available in multiple trims which all came very well equipped with upscale amenities.
And, this extended wheelbase version offers much more rear seat leg room for long and winding Georgia road trips. The standard steel engine [not nikasil] in this XJ is a 4.0L V8 which produces 290 hp. The upper and lower timing chain tensioners are original, second generation metal, not plastic.
There is also a supercharged version of this vehicle which bumps output to an impressive 370 hp. Even with all of its power and weight, my XJ-8-L is still rated at over 20 mpg on the highway. Ammenities and upgrades include a mobile phone, Magellan GPS, LoJack theft recovery system, CD and MP-3 players, with internal and external cable antenna for satellite radio.
What a Cat? She is my third favorite female after my intelligent and beautiful wife, and smart and lovely daughter.
Conclusion
Are you a DIYer, like me? Nothing says you care more than doing it yourself.
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on March 31, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
HAPPY EASTER SUNDAY 2024
This ME-P was originally posted in 2014 and updated annually since then.
The median U.S. gas price is $3.49 per gallon, unchanged from last week and about 29 cents lower than the national average. The top 10% of stations in the country average $6.09 per gallon, while the bottom 10% average $2.92 per gallon. The states with the lowest average prices: Mississippi ($3.02), Louisiana ($3.06) and Texas ($3.06).
***
Conclusion
And so, your thoughts and comments on this ME-P are appreciated. Please review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on March 31, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
HAPPY EASTER
***
***
Tesla had a rough quarter
The company’s stock was the worst performing in the S&P 500 in Q1, dropping 29%, amid fierce competition from Chinese electric carmakers, slowdowns from Red Sea shipping routes, arson at its German factory, Nordic labor battles, and controversies surrounding CEO Elon Musk.
Now, investors are warily watching to see what delivery numbers Tesla reports. But one group did make lots of money off the company as it lost over $230 billion in value last quarter: short sellers.
Donald Trump’s namesake social media company burst out of the gate on its first day of trading Tuesday, opening at $70.90 and soaring as high as $79.38 as Trump fans and opportunistic traders bought up shares. But the price faded late in the session and has bounced along at lower levels ever since, ending Thursday down $4.26 at $61.96 on the NASDAQ. The stock exchange was closed Friday in observance of Good Friday.
Posted on March 29, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
DIVIDEND REINVESTMENT PLANS
By Staff Reporters
***
DEFINITION
DRIPs are merely an automated strategy in which a company’s dividends are reinvested into additional shares of that company. Instead of being paid dividends in cash, you get additional shares of ownership in the company.
There are three ways to get involved in DRIPs: directly through the company, through your broker, or through a transfer agent.
Company-run DRIPs are generally only available through large, blue-chip dividend stocks.That’s because smaller companies don’t want to take on the overhead costs of tracking all their shareholders and going through the paperwork headache of calculating how much each one gets in dividends and additional fractional shares. The company benefits from gaining an additional source of capital, but most of all in creating a more stable base of shareholders, ones who are less likely to panic and sell during a market decline. This can help decrease the volatility of a company’s shares.
Finally, most large discount brokers, such as Scottrade, TD Ameritrade, and E*Trade, also offer DRIPs, though with different requirements and limitations.
While dividend reinvestment is powerful, there are a couple reasons why you might not want to reinvest your dividends.
DRIPs Drawback 1: You may need the dividend income The most obvious reason is that you need the income. If you’re in the “distribution” phase of your investing life, dividends are a perfect source of passive income. Income from qualified dividends is taxed at the long-term capital gains rate (currently 15% for investors who are in the 25% to 35% tax bracket for ordinary income, 0% for taxpayers in a lower bracket and 20% for those in the highest bracket). So if you’re going to be looking to your portfolio for income every month anyway, it makes sense to have that cash deposited in your account.
DRIPs Drawback 2: You may need to reallocate your positions You might also choose to stop reinvesting your dividends for allocation reasons. Reinvesting your dividends, through DRIP plans or otherwise, will cause your stock positions to grow over time, and if you’ve owned a particular issue for a long time, it may already be a large enough percentage of your portfolio. Higher-yielding positions will grow faster, which can throw your allocations out of whack pretty quickly. So once a stock position is as big as you want it to get (for now) feel free to turn off dividend reinvestment for that position, and either enjoy the extra income or save up the cash to invest in other stocks.
DRIPs Drawback 3: You may not want to buy that stock at that time Finally, you may also have stock-specific reasons not to reinvest dividends—if a stock is temporarily overvalued, or you simply don’t want to buy any more of it at current prices.
But bottom line, reinvesting dividends through a broker or by signing up for DRIP plans directly through the dividend-paying companies, is a surprisingly powerful tool to passively improve your investment returns.
***
NOTE: Former Microsoft CEO Steve Ballmer is on pace to earn $1 billion in dividends annually from his massive 4% stake in the software company.
Steve Ballmer is on pace to collect annual dividend payments of $1 billion from Microsoft.
He is the former CEO of Microsoft and is the largest individual shareholder of the software giant.
Ballmer’s Microsoft stake has surged to a value of $128 billion this year following Microsoft’s 55% stock rally.
Posted on March 29, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
The stock market will be closed Friday, March 29th, for Good Friday. While Good Friday is a stock market holiday, it is not a federal holiday. As a result, the February Personal Consumption and Expenditures (PCE) Price Index will be released this Friday morning.
Yesterday, on the final trading session of March and the first quarter, the returns for major stock indexes are impressive, with the Dow Jones Industrial Average up 5% this quarter or 2,000 points and the S&P 500 and the tech-heavy NASDAQ up 11% apiece. Stock superlatives for 2024’s opening stretch are numerous, including each of the three indexes setting respective all-time highs and the benchmark S&P heading toward its best first-quarter return since 2019 and its second consecutive quarter of double-digit percentage gains since 2011-12.
The S&P 500 index added 5.86 points (0.1%) to 5,254.35, up 0.4% for the week; the Dow Jones Industrial Average climbed 47.29 points (0.1%) to 39,807.37, up 0.8% for the week; the NASDAQ Composite lost 20.06 points (0.1%) to 16,379.46, down 0.3% for the week.
The 10-year Treasury note yield rose one basis point to just under 4.21%.
The CBOE Volatility Index® (VIX) rose 0.22 to 13.00.
For the month, the S&P 500 index gained 3.1%, the Dow Jones Industrial Average rose 2.1%, and the NASDAQ Composite added 1.8%. For the quarter, the three indexes rose 10.3%, 5.6%, and 9.2%, respectively.
TERMS & DEFINITIONS FOR PHYSICIANSAND ALL INVESTORS:
PRUDENT BUYER: The efficient purchaser of market balance between value and cost.
PRUDENT MAN RULE: An 1830 court case stating that a person in a fiduciary capacity (a trustee, executor, custodian, etc) must conduct him/herself faithfully and exercise sound judgment when investing monies under care. “He is to observe how men of prudence, discretion and intelligence manage their own affairs, not in regard to speculation, but in regard to the permanent distribution of their funds, considering the probable income as well as the probable safety of the capital to be invested.” Allows for mutual funds and variable annuities.
PRUDENT INVESTOR RULE: A fiduciary is required to conduct him/herself faithfully and exercise sound judgment when investing monies and take measured and reasonable investment risks in return for potential future rewards. Allows for mutual funds, stocks, bonds, variable annuities asset allocation & Modern Portfolio Theory.
EDITOR’SNOTE: We interviewed noted authority Ben Aikin AIF® on this topic more than a decade ago. He was ahead of his time regarding fiduciary accountability and we appreciate his insights.
Posted on March 28, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Related Influential Thought-Leaders
Dr. Brad Klontz CSAC CFP®
Dr. Ted Klontz PsyD
Dr. Eugene Schmuckler MBA MEd CTS
Dr. Kenneth Shubin-Stein FACP CFA
Dr. David Edward Marcinko MEd MBA CMP™
***
***
James O. Prochaska PhD, Professor of Psychology and Director of the Cancer Prevention Research Center at the University of Rhode Island, developed the Trans-Theoretic Model of Behavior Change [TTM] which has been evolving since in 1977. Nominated as one of the five most influential authors in Psychology, by the Institute for Scientific Information and the American Psychological Society, Dr. Prochaska is author of more than 300 papers on behavior change for health promotion and disease prevention.
TTM Stages of Change
In his Trans-Theoretical Model, behavior change is a “process involving progress through a series of these stages:
Pre-Contemplation (Not Ready) – “People are not intending to take action in the foreseeable future, and can be unaware that their behavior is problematic”
Contemplation (Getting Ready) – “People are beginning to recognize that their behavior is problematic, and start to look at the pros and cons of their continued actions”
Preparation (Ready) – “People are intending to take action in the immediate future, and may begin taking small steps toward behavior change”
Action – “People have made specific overt modifications in changing their problem behavior or in acquiring new healthy behaviors”
Maintenance – “People have been able to sustain action for a while and are working to prevent relapse”
Termination – “Individuals have zero temptation and they are sure they will not return to their old unhealthy habit as a way of coping”
Relapse
In addition, researchers conceptualized “relapse” (recycling) which is not a stage in itself but rather the “return from Action or Maintenance to an earlier stage.” In medical care, these stages of behavior change have applicability to anti-hypertension and lipid lowering medication use, as well as depression prevention, weight control and smoking cessation.
***
***
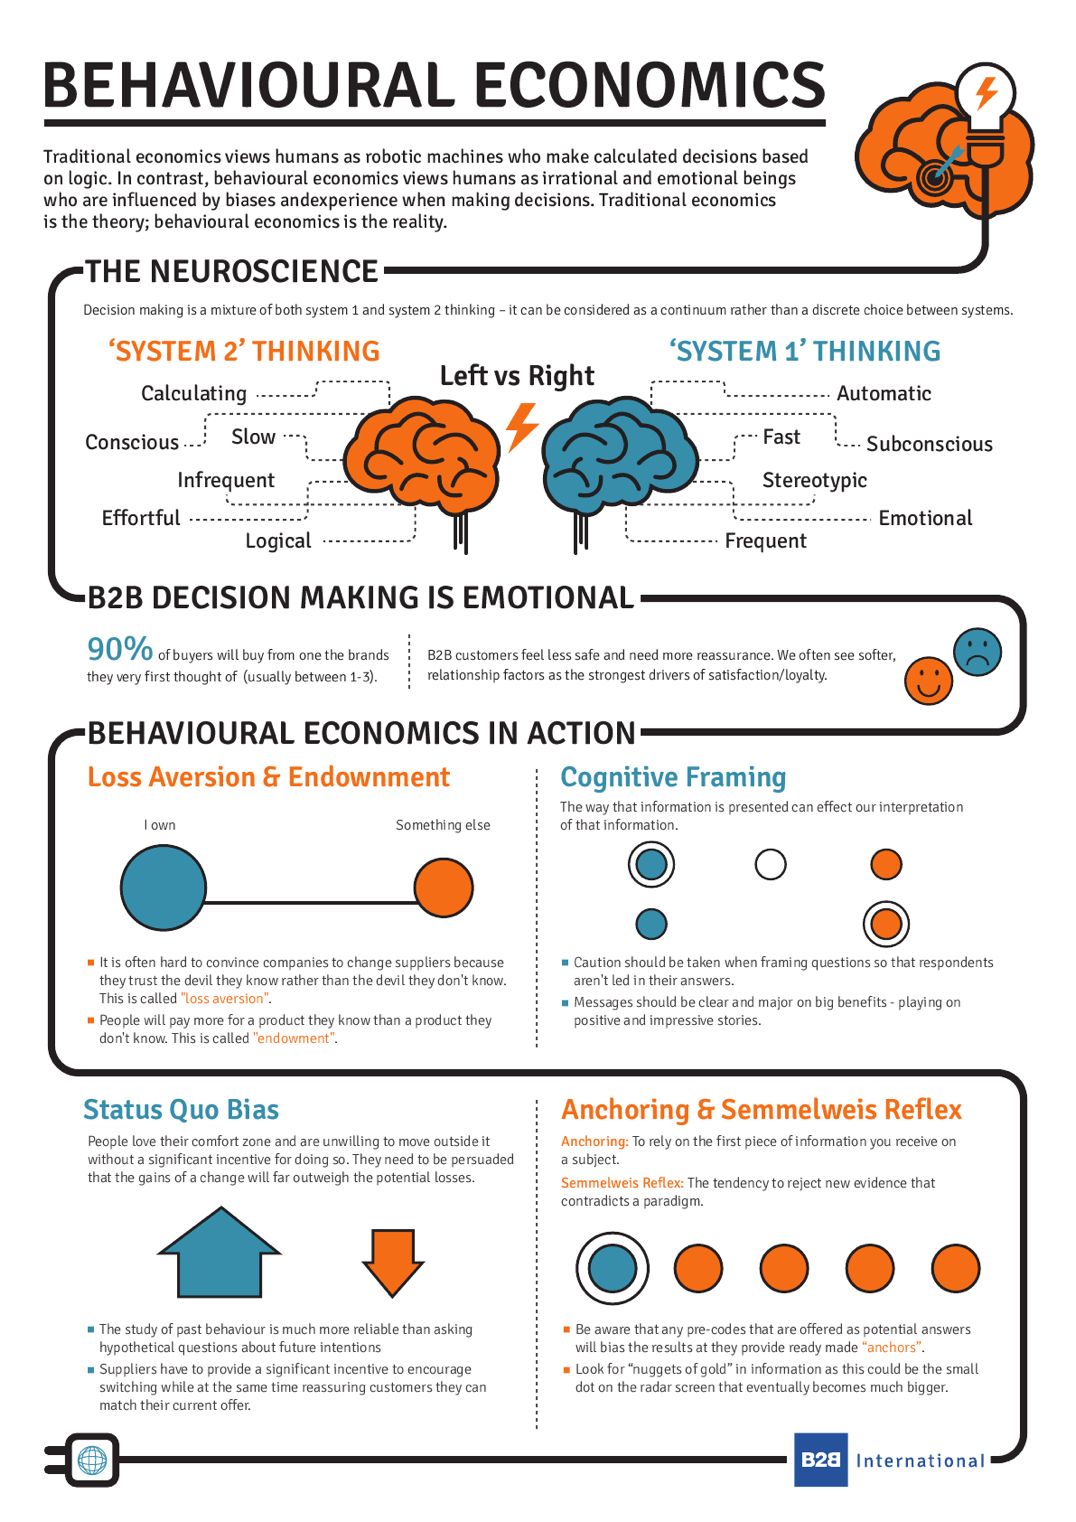
Uniting Psychology and Financial Behavior
More recently, validating the emerging alliance between psychology (human behavior) and finance (economics) are two Americans who won the Royal Swedish Academy of Science’s 2002 Nobel Memorial Prize in Economic Science. Their research was nothing short of an explanation for the idiosyncrasies incumbent in human financial decision-making outcomes.
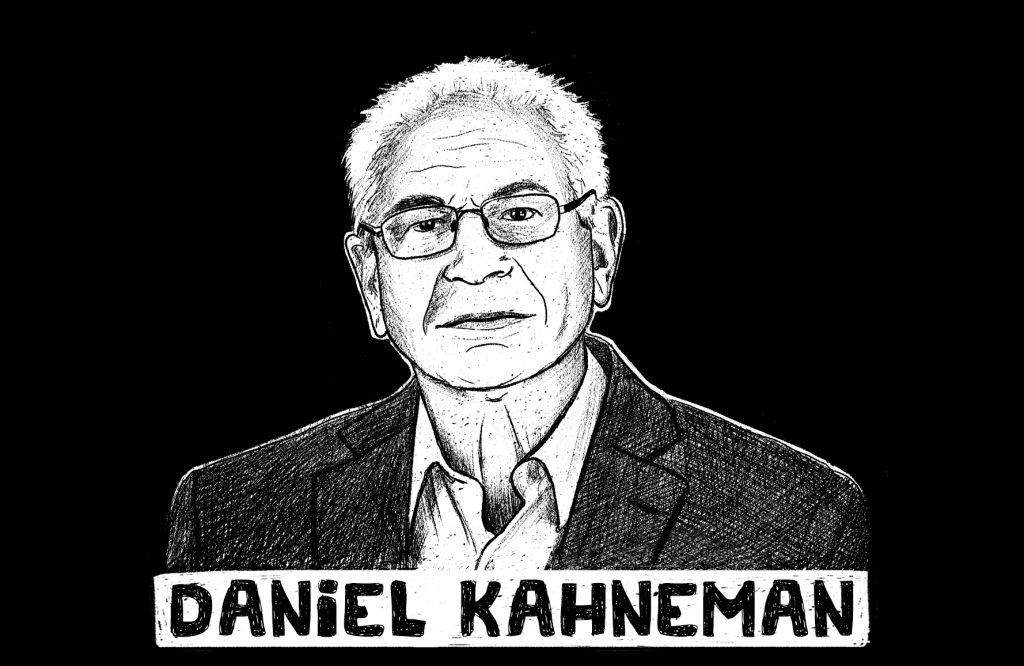
Enter Kahneman and Smith
Daniel Kahneman, PhD, professor of psychology at Princeton University, and Vernon L. Smith, PhD, professor of economics at George Mason University in Fairfax, Va., shared the prize for work that provided insight on everything from stock market bubbles, to regulating utilities, and countless other economic activities. In several cases, the winners tried to explain apparent financial paradoxes.
For example, Professor Kahneman made the economically puzzling discovery that most of his subjects would make a 20-minute trip to buy a calculator for $10 instead of $15, but would not make the same trip to buy a jacket for $120 instead of $125, saving the same $5.
in vitro and in-vivo Economics
Initially, in the 1960’s, Smith set out to demonstrate how economic theory worked in the laboratory (in vitro), while Kahneman was more interested in the ways economic theory mis-predicted people in real-life (in-vivo). He tested the limits of standard economic choice theory in predicting the actions of real people, and his work formalized laboratory techniques for studying economic decision making, with a focus on trading and bargaining.
Later, Smith and Kahneman together were among the first economists to make experimental data a cornerstone of academic output. Their studies included people playing games of cooperation and trust, and simulating different types of markets in a laboratory setting. Their theories assumed that individuals make decisions systematically, based on preferences and available information, in a way that changes little over time, or in different contexts.
University of Chicago
By the late 1970’s, Richard H. Thaler, PhD, an economist at the University of Chicago also began to perform behavioral experiments further suggesting irrational wrinkles in standard financial theory and behavior, enhancing the still embryonic but increasingly popular theories of Kahneman and Smith.
Other economists’ laboratory experiments used ideas about competitive interactions pioneered by game theorists like John Forbes Nash Jr., PhD, who shared the Nobel in 1994, as points of reference.
Assessment
But, Kahneman and Smith often concentrated on cases where people’s actions departed from the systematic, rational strategies that Nash envisioned. Psychologically, this was all a precursor to the informal concept of life or holistic financial planning. Kahneman was awarded the Medal of Freedom, by President Barack Obama, on November 20, 2013.
Have you visited our other topic channels? Established to facilitate idea exchange and link our community together, the value of these topics is dependent upon your input. Please take a minute to visit. And, to prevent that annoying spam, we ask that you register. It is fast, free and secure.
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on March 28, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
NOBEL PRIZE WINNER AND FATHER OF BEHAVIORAL ECONOMICS
By Staff Reporters
DEFINITION: According to Wikipedia, behavioral economics is the study of the psychological, cognitive, emotional, cultural and social factors involved in the decisions of individuals or institutions, and how these decisions deviate from those implied by classical economic theory.
Behavioral economics is primarily concerned with the bounds of rationality of economic agents. Behavioral models typically integrate insights from psychology, neuroscience and microeconomic theory. The study of behavioral economics includes how market decisions are made and the mechanisms that drive public opinion.
Behavioral economics began as a distinct field of study in the 1970s and ’80s, but can be traced back to 18th-century economists, such as Adam Smith, who deliberated how the economic behavior of individuals could be influenced by their desires.
The status of behavioral economics as a subfield of economics is a fairly recent development; the breakthroughs that laid the foundation for it were published through the last three decades of the 20th century. Behavioral economics is still growing as a field, being used increasingly in research and in teaching.
***
***
Daniel Kahneman PhD, the father of behavioral economics, died yesterday at age 90 years old. He’s best known for applying psychology to economics and uncovering biases and mental shortcuts that make people act irrationally, as he chronicled in his best-selling book Thinking, Fast and Slow.
Kahneman, along with his long-time collaborator and friend Amos Tversky PhD, developed “prospect theory,” or loss-aversion theory, which earned him the Nobel Prize in Economics in 2002 (which he shared with fellow economist Vernon Smith). The idea is that people value losses and gains differently, so we feel more bad about losing $100 than we feel good about making the same amount. He applied this theory to investors, who had previously been considered rational decision-makers. It shows up elsewhere, too—for example, golfers putt better when they’re facing the loss of a stroke than when they might gain one.
Two other biases he identified include:
The “peak-end rule” that people remember an experience primarily based on how they felt at its most intense moment and the final part of it. It’s why you consider a whole vacation good if the last day was good—or the opposite.
The conjunction fallacy where people erroneously think the probability of two things being true is more likely than just one thing, which the famous “Linda the Bank Teller” problem illustrates.
Posted on March 28, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
***
Independent pharmacies have struggled in recent years to stay open—and new financial constraints may mean a record number of pharmacy closures in 2024. And, nearly a third of independent pharmacies are at risk of going out of business due in part to a new rule from the Centers for Medicare and Medicaid Services (CMS) that results in lower prescription reimbursements, according to the National Community Pharmacists Association (NCPA), a trade group that represents more than 19,400 US pharmacies.
“This is an emergency,” NCPA CEO B. Douglas Hoey said in a statement. “If Congress fails to act again, thousands of local pharmacies could be closed within months and millions of patients could be stranded without a pharmacy.” The CMS rule, which went into effect on January 1st, requires payers and pharmacy benefit managers (PBMs) to apply what’s called direct and indirect remuneration (DIR) fees at the time a patient picks up a prescription.
The S&P 500 index added 44.91 points (0.9%) to 5,248.49; the Dow Jones Industrial Average climbed 477.75 points (1.2%) to 39,760.08; the NASDAQ Composite added 83.82 points (0.5%) to 16,399.52.
The 10-year Treasury note yield fell four basis points to just under 4.2%.
The CBOE Volatility Index® (VIX) dropped 0.48 to 12.76.
In addition to utility stocks, real estate, industrials, and materials were the strongest sectors. Information technology and communications were the weakest but found late-day strength to finish higher.
Managerial and medical cost accounting is not governed by generally accepted accounting principles (GAAP) as promoted by the Financial Accounting Standards Board (FASB) for CPAs. Rather, a healthcare organization costing expert may be a Certified Cost Accountant (CCA) or Certified Managerial Accountant (CMA) designated by the Cost Accounting Standards Board (CASB), an independent board within the Office of Management and Budget’s (OMB) Office of Federal Procurement Policy (OFPP).
The Cost Accounting Standards Board
CASB consists of five members, including the OFPP Administrator who serves as chairman and four members with experience in government contract cost accounting (two from the federal government, one from industry, and one from the accounting profession). The Board has the exclusive authority to make, promulgate, and amend cost accounting standards and interpretations designed to achieve uniformity and consistency in the cost accounting practices governing the measurement, assignment, and allocation of costs to contracts with the United States.
Codified at 48 CFR
CASB’s regulations are codified at 48 CFR, Chapter 99. The standards are mandatory for use by all executive agencies and by contractors and subcontractors in estimating, accumulating, and reporting costs in connection with pricing and administration of, and settlement of disputes concerning, all negotiated prime contract and subcontract procurement with the United States in excess of $500,000. The rules and regulations of the CASB appear in the federal acquisition regulations.
North American Industry Classification System (NAICS) codes are used to categorize data for the federal government. In acquisition they are particularly critical for size standards. The NAICS codes are revised every five years by the Census Bureau. As of October 1, 2007, the federal acquisition community began using the 2007 version of the NAICS codes at www.census.gov/epcd/www/naics.html
Cost Accounting Standards
Healthcare organizations and consultants are obligated to comply with the following cost accounting standards (CAS) promulgated by federal agencies:
CAS 501 requires consistency in estimating, accumulating, and reporting costs.
CAS 502 requires consistency in allocating costs incurred for the same purpose.
CAS 505 requires proper treatment of unallowable costs.
CAS 506 requires consistency in the periods used for cost accounting.
The requirements of these standards are different from those of traditional financial accounting, which are concerned with providing static historical information to creditors, shareholders, and those outside the public or private healthcare organization.
Assessment
Functionally, most healthcare organizations also contain cost centers, which have no revenue budgets or mission to earn revenues for the organization. Examples include human resources, administration, housekeeping, nursing, and the like. These are known as responsibility centers with budgeting constraints but no earnings. Furthermore, shadow cost centers include certain non-cash or cash expenses, such as amortization, depreciation and utilities, and rent. These non-centralized shadow centers are cost allocated for budgeting purposes and must be treated as costs http://www.CertifiedMedicalPlanner.org
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
Posted on March 27, 2024 by Dr. David Edward Marcinko MBA MEd CMP™
By Staff Reporters
***
A stalking horse bid is an initial bid on the assets of a bankrupt company. The bankrupt company will choose an entity from a pool of bidders who will make the first bid on the firm’s remaining assets. The stalking horse sets the low-end bidding bar so that other bidders can’t underbid the purchase price.
The term “stalking horse” originates from a hunter trying to be concealed behind either a real or fake horse.
A stalking horse bid is an initial bid on the assets of a bankrupt company, setting the low-end bidding bar so that other bidders can’t underbid the purchase price.
Other buyers can submit competing offers following the stalking horse bid.
A stalking horse bidder is afforded various incentives, such as expense reimbursements and breakup fees.
***
On December 17th, 2023, after defaulting on a $617 million loan, Ebix, Inc of Atlanta Georgia, declared Chapter 11 bankruptcy. Then, Ebix Reaches “Stalking Horse” Sale Agreement for Life Insurance and Annuity Business with Zinnia to Ensure Successful Recapitalization Efforts in 2024.



 Support our online development, and advance our onground research initiatives in free market economics, as we seek to showcase the brightest Next-Gen minds.
THE ME-P DISCLAIMER: Posts, comments and opinions do not necessarily represent iMBA, Inc., but become our property after submission. Copyright © 2006 to-date. iMBA, Inc allows colleges, universities, medical and financial professionals and related clinics, hospitals and non-profit healthcare organizations to distribute our proprietary essays, photos, videos, audios and other documents; etc. However, please review copyright and usage information for each individual asset before submission to us, and/or placement on your publication or web site. Attestation references, citations and/or back-links are required. All other assets are property of the individual copyright holder.