PODCAST: The “Medical Trend”?

By Eric Bricker MD

***

***

COMMENTS APPRECIATED

Thank You

***

MORE: https://medicalexecutivepost.com/2022/01/25/global-medical-trends-healthcare-cost-increases/

***

***

Become a CERTIFIED MEDICAL PLANNER™

Course Description and Information

 www.CertifiedMedicalPlanner.org

 Now accepting applications!

 “Live” On-Line Matriculation Leading to a Chartered Professional Designation

CMP logo

Become a Certified Medical Planner™

AND

Help Doctor Clients Succeed

***

***

How [DOCTORS] Construct Investment Portfolios That Protect Them

***

“ASK AN ADVISOR“

***

Vitaliy N. Katsenelson, CFA - YouTube

By Vitaliy N. Katsenelson, CFA

***

Question: How do you construct investment portfolios and determine position sizes (weights) of individual stocks?

I wanted to discuss this topic for a long time, so here is a very in-depth answer.
CITE: https://www.r2library.com/Resource/Title/082610254

Answer
For a while in the value investing community the number of positions you held was akin to bragging on your manhood– the fewer positions you owned the more macho an investor you were. I remember meeting two investors at a value conference. At the time they had both had “walk on water” streaks of returns. One had a seven-stock portfolio, the other held three stocks. Sadly, the financial crisis humbled both – the three-stock guy suffered irreparable losses and went out of business (losing most of his clients’ money). The other, after living through a few incredibly difficult years and an investor exodus, is running a more diversified portfolio today.

Under-diversification: Is dangerous, because a few mistakes or a visit from Bad Luck may prove to be fatal to the portfolio.

On the other extreme, you have a mutual fund industry where it is common to see portfolios with hundreds of stocks (I am generalizing). There are many reasons for that. Mutual funds have an army of analysts who need to be kept busy; their voices need to be heard; and thus their stock picks need to find their way into the portfolio (there are a lot of internal politics in this portfolio). These portfolios are run against benchmarks; thus their construction starts to resemble Noah’s Ark, bringing on board a few animals (stocks) from each industry. Also, the size of the fund may limit its ability to buy large positions in small companies.

There are several problems with this approach. First, and this is the important one, it breeds indifference: If a 0.5% position doubles or gets halved, it will have little impact on the portfolio. The second problem is that it is difficult to maintain research on all these positions. Yes, a mutual fund will have an army of analysts following each industry, but the portfolio manager is the one making the final buy and sell decisions. Third, the 75th idea is probably not as good as the 30th, especially in an overvalued market where good ideas are scarce.

Then you have index funds. On the surface they are over-diversified, but they don’t suffer from the over-diversification headaches of managed funds. In fact, index funds are both over-diversified and under-diversified. Let’s take the S&P 500 – the most popular of the bunch. It owns the 500 largest companies in the US. You’d think it was a diversified portfolio, right? Well, kind of. The top eight companies account for more than 25% of the index. Also, the construction of the index favors stocks that are usually more expensive or that have recently appreciated (it is market-cap-weighted); thus you are “diversified” across a lot of overvalued stocks.

If you own hundreds of securities that are exposed to the same idiosyncratic risk, then are you really diversified?

Our portfolio construction process is built from a first-principles perspective. If a Martian visited Earth and decided to try his hand at value investing, knowing nothing about common (usually academic) conventions, how would he construct a portfolio?

We want to have a portfolio where we own not too many stocks, so that every decision we make matters – we have both skin and soul in the game in each decision. But we don’t want to own so few that a small number of stocks slipping on a banana will send us into financial ruin.

In our portfolio construction, we are trying to maximize both our IQ and our EQ (emotional quotient). Too few stocks will decapitate our EQ – we won’t be able to sleep well at night, as the relatively large impact of a low-probability risk could have a devastating impact on the portfolio. I wrote about the importance of good sleep before (link here). It’s something we take seriously at IMA.

Holding too many stocks will result in both a low EQ and low IQ. It is very difficult to follow and understand the drivers of the business of hundreds of stocks, therefore a low IQ about individual positions will eventually lead to lower portfolio EQ. When things turn bad, a constant in investing, you won’t intimately know your portfolio – you’ll be surrounded by a lot of (tiny-position) strangers.

Portfolio construction is a very intimate process. It is unique to one’s EQ and IQ. Our typical portfolios have 20–30 stocks. Our “focused” portfolios have 12–15 stocks (they are designed for clients where we represent only a small part of their total wealth). There is nothing magical about these numbers – they are just the Goldilocks levels for us, for our team and our clients. They allow room for bad luck, but at the same time every decision we make matters.

Now let’s discuss position sizing. We determine position sizing through a well-defined quantitative process. The goals of this process are to achieve the following: Shift the portfolio towards higher-quality companies with higher returns. Take emotion out of the portfolio construction process. And finally, insure healthy diversification.

Our research process is very qualitative: We read annual reports, talk to competitors and ex-employees, build financial models, and debate stocks among ourselves and our research network. In our valuation analysis we try to kill the business – come up with worst-case fair value (where a company slips on multiple bananas) and reasonable fair value. We also assign a quality rating to each company in the portfolio. Quality is absolute for us – we don’t allow low-quality companies in, no matter how attractive the valuation is (though that doesn’t mean we don’t occasionally misjudge a company’s quality).

The same company, at different stock prices, will merit a higher or lower position size. In other words, if company A is worth (fair value) $100, at $60 it will be a 3% position and at $40 it will be a 5% position. Company B, of a lower quality than A but also worth $100, will be a 2% position at $60 and a 4% position at $40 (I just made up these numbers for illustration purposes). In other words, if there are two companies that have similar expected returns, but one is of higher quality than the other, our system will automatically allocate a larger percentage of the portfolio to the higher-quality company. If you repeat this exercise on a large number of stocks, you cannot but help to shift your portfolio to higher-quality, higher-return stocks. It’s a system of meritocracy where we marry quality and return.

Let’s talk about diversification. We don’t go out of our way to diversify the portfolio. At least, not in a traditional sense. We are not going to allocate 7% to mining stocks because that is the allocation in the index or they are negatively correlated to soft drink companies. (We don’t own either and are not sure if the above statement is even true, but you get the point.) We try to assemble a portfolio of high-quality companies that are attractively priced, whose businesses march to different drummers and are not impacted by the same risks.  Just as bank robbers rob banks because that is where the money is, value investors gravitate towards sectors where the value is. To keep our excitement (our emotions) in check, and to make sure we are not overexposed to a single industry, we set hard limits of industry exposure. These limits range from 10%–20%. We also set limits of country exposure, ranging from 7%–30% (ex-US).

CONCLUSION

In portfolio construction, our goal is not to limit the volatility of the portfolio but to reduce true risk – the permanent loss of capital. We are constantly thinking about the types of risks we are taking. Do we have too much exposure to a weaker or stronger dollar? To higher or lower interest rates? Do we have too much exposure to federal government spending? I know, risk is a four-letter word that has lost its meaning. But not to us. Low interest rates may have time-shifted risk into the future, but they haven’t cured it.

***

COMMENTS APPRECIATED

Thank You

Subscribe to the Medical Executive-Post

***

***

PODCAST: Optum – The $101 Billion Division of United Health Group Explained

By Eric Bricker MD

***

PODCAST: https://www.youtube.com/watch?v=dHAr0s33Gns

RELATED: https://www.youtube.com/watch?v=-21-h5lZBEU

***

***

***

COMMENTS APPRECIATED

Thank You

***

How Much Do You Earn Dr. Dad … or Dr. Mom?

Join Our Mailing List

Your Children and Your Money

Rick Kahler MS CFPBy Rick Kahler CFP

As a doctor – Do your kids know how much money you make? If not, and they asked, would you feel comfortable telling them?

My hunch is that the most common answer to both these questions is “No.” Talking about money is such a strong taboo that it often keeps us from sharing information about our earnings and net worth even with members of our immediate families.

Yet being honest with children about what we earn and how we spend it is a perfect opportunity to teach them important life lessons about money.

Here are a few suggestions to foster those conversations:

  1. Take advantage of teachable moments. As with many other big questions, like where babies come from or whether cats go to heaven (personally, I doubt it, but that may say more about my prejudices than my theology), the ideal time to answer money questions is when the kids ask.
  2. Provide context for numbers. To a child who gets an allowance of five bucks a week, either $10,000 or $100,000 a year can seem huge. One way to put those numbers into context is with comparisons: “I earn about the same amount as your teachers do,” or, “Most doctors probably earn about twice as much as our family does.”
  3. Talk about expenses as well as income. This is huge. It’s another important way of providing context. Plus it helps open kids’ eyes to the realities of earning and spending. When my kids, at about age 10 and 14, first asked about my income, they were impressed with how high the number was. Then we looked at the family expenses: house payment, health insurance, food, college savings, and everything else. They were even more impressed. Seeing what things cost and where the money goes is a good start to educating kids about spending, saving, and creating healthy money habits.
  4. Share appropriately for kids’ ages and understanding. Seven-year-olds and 13-year-olds aren’t ready for the same information. Don’t underestimate your kids’ comprehension, however; if you encourage them to ask questions and are willing to explain and clarify, they may understand more than you expect.
  5. Tell the truth. If you have financial difficulties that stem from your own money mistakes or other bad choices, being honest with your kids can be a powerful teaching opportunity. If you don’t earn a lot but are managing to take care of the family, that’s something to be proud of. If your kids may inherit substantial amounts, it’s wise to start teaching them early how to deal with wealth. Whether you have a net worth in the millions or are barely getting by from month to month, clean honesty about the family finances is a good policy.
  6. Remember that you’re the adult. Over-sharing about financial challenges can frighten your kids. It’s more useful to be matter-of-fact about problems and focus on what you’re doing to solve them.
  7. Keep in mind that when parents don’t talk about money, kids will make up their own stories. Typically this will be either that you earn and have more than you do, or that the family is on the brink of bankruptcy and homelessness.
  8. Look at your own shame and secrecy about money. If parents never talk about money, kids may never ask money questions. Either the topic is simply not on their radar, or they have internalized the unspoken message that it is off limits. In either case, parents can change the family culture by becoming more open about their finances. Those teachable moments for kids begin to happen when money is no longer a secret.

***

Doctor salary

***

More:

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™ Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

More on Concierge, Retail, Cash Pay and Boutique Medicine; etc [SAM’S CLUB]

Sam’s Club Launches Innovative Pilot to Help Make Healthcare More Affordable


cropped-dem

By Dr. David E. Marcinko MBA CMP

I devoted a full chapter of my book; “The Business of Medical Practice” to concierge and boutique medicine, retail medicine, direct, cash and private pay medicine; etc. We included terms and definitions, process and methodologies, marketing and advertising, and examples, etc. In fact, who knew I was so prescient and the landscape would finally begin evolving.

For example, we recently learned about Sam’s Club offering targeted “bundles” of health care services collaborating with Humana. https://lnkd.in/ejHGGzk

And, earlier, we learned of Amazon’s new virtual / primary care clinic model. And of course, in the past couple of weeks, Walmart’s (Sam’s affiliate) opening their freestanding clinics, along with new behavioral health services, as well.

 ******

Assessment: Your thoughts are appreciated.

THANK YOU

Product DetailsProduct Details

***

The DOT.com Bubble HAS Burst!

What is NEXT?

U.S. equities closed lower as losses in the Technology, Consumer Services and Financials sectors propelled shares lower. At the close, the Dow Jones Industrial Average fell 2.73%, while the S&P 500 index lost 2.91%, and the NASDAQ Composite index fell 3.52%.

***

By Vitaliy N. Katsenelson CFA

***

What a Day – TODAY!

READ: https://tinyurl.com/2r8zaftk

COMMENTS APPRECIATED

Thank You

***

***

Passive Investing, Like Buying Used Cars, Is a Wise Strategy

More on Passive Investing

By Rick Kahler MS CFP®

***

Need a car? Buy used. It’s what I always do. My sweet spot is a low-mileage vehicle two or three years old, which I routinely can find for 25% to 35% less than the original cost. I recommend this strategy to my clients, staff, and friends.

If everyone followed this advice, you’d think the approach would eventually fail dismally. After all, someone has to buy new cars. No worries, though; there are millions of people who will continue to buy new cars. Financial planners have recommended this strategy for decades, and nothing has changed in the supply of great deals on low-mileage cars.

The same applies to investors who invest “passively” in index mutual funds. Passive investors embrace a philosophy that extremely few investors can beat the average return of the stock market. Research by Dalbar, Inc. shows that over a 20-year-period, 97% of fund managers who tried to beat the market actually ended up doing worse than the market average. They suggest that, instead of paying a manager to try and beat the market, you pocket that money yourself and beat them by investing in low cost index mutual funds that simply earn average market returns.

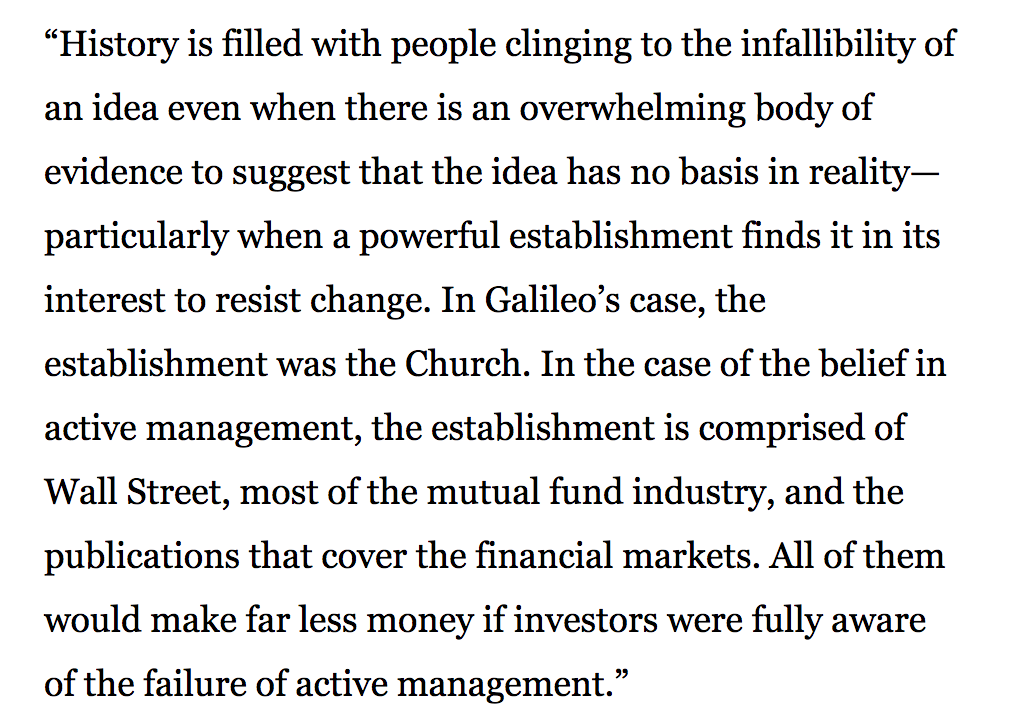
As you might guess, those pushing the high-fee mutual funds that are actively trying to beat the market returns are the big Wall Street firms that need your money to keep their companies thriving. Not surprisingly, these firms regularly attempt to dissuade investors from passive investing.

***

active mamt

***

An article at ETF.com by Larry Swedroe, the director of research for The BAM Alliance, lists a few of these attempts. Representatives for two large brokerage firms call passive investing “worse than Marxism” and those that do it “parasites.” Another, however, gives a more reasoned warning that is worth exploring. Tim O’Neill, global co-head of Goldman Sach’s investment management division, says “if passive investing gets too big, the market won’t function.”

Up to a point, this idea has some validity. Swedroe says, “Active managers play an important societal role. Specifically, their actions determine security prices, which in turn determine how capital is allocated. And it is the competition for information that keeps markets highly efficient, both in terms of information and capital allocation.”

Passive investors get a free ride at the expense of active investors. As Swedroe notes, they receive all the benefits from the role that active managers play without having to pay their costs. Passive investors need active investors to continue to believe they can beat the markets, just as used car buyers need new car buyers to supply them with used cars.

Just how likely is it that all the people who invest with active investors will figure out that paying active managers is not in their best interests and will shift to passive investing? About the same chance everyone will stop buying new cars.

Consider this. A study by Vanguard, one of the largest passive fund managers, found that $10 trillion, or 20% of the global market equity, is invested in index funds. More importantly, this 20% accounted for only 5% of all the trading. It’s the trading that drives market prices and makes markets efficient and liquid. Swedroe says “we are nowhere near” the chance that passive investing will become so dominant that the efficiency of the markets would be threatened.

Just as there is no immediate threat of the used car supply drying up because no one is buying new cars, there is also little chance that the majority of investors will give up the delusional dream of beating the market. That means wise used-car buyers and wise passive investors can keep on following their wise wealth-building strategies.

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Book Marcinko: https://medicalexecutivepost.com/dr-david-marcinkos-bookings/

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, IT, business and policy management ecosystem.

DOCTORS:

“Insurance & Risk Management Strategies for Doctors” https://tinyurl.com/ydx9kd93

“Fiduciary Financial Planning for Physicians” https://tinyurl.com/y7f5pnox

“Business of Medical Practice 2.0” https://tinyurl.com/yb3x6wr8

HOSPITALS:

“Financial Management Strategies for Hospitals” https://tinyurl.com/yagu567d

“Operational Strategies for Clinics and Hospitals” https://tinyurl.com/y9avbrq5

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™


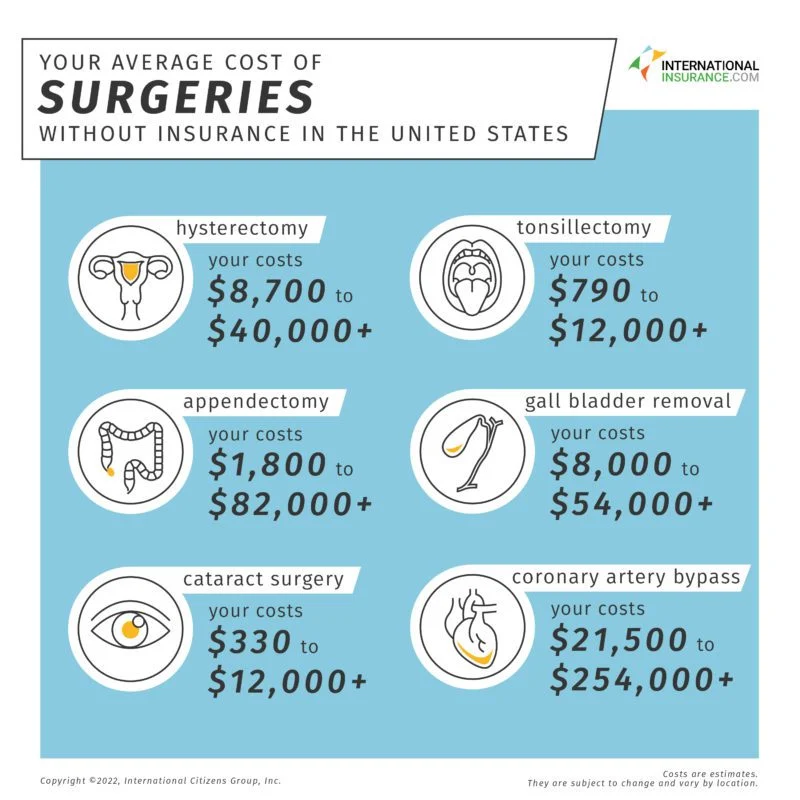
SURVEY: Surgical Cost Spending

By MCOL

***

***

EHIR was started nearly a decade ago out of a need for objective support in identifying and assessing emerging solutions to sift through the noise and stay ahead of the curve amid a rapidly changing competitive landscape. EHIR provides a streamlined and efficient innovation intake and evaluation process along with valuable insights to the world’s leading employers.

CITE: https://www.r2library.com/Resource/Title/082610254

Employer Health Innovation Roundtable, LLC

4 KEY Findings

 •  The survey found that 59% indicated lowering costs was a very high, or high, priority – up from 52% prior to the pandemic.
 •  Over half of the employers surveyed indicated that surgical costs were a significant issue, with surgery accounting for 34% of their total healthcare spend. About 75% noted that by controlling surgery costs, they can largely reduce their total spend.

***

*  Even though 69% of employers have a COE (Center of Excellence), the majority of them have been implemented within the past two years, and not with an eye to specifically reducing surgical costs.
 *  Only 9% of respondents rely on carrier-sponsored COEs, which suggests that they are seeking out third-party vendors for this benefit, as either the sole COE provider or as a partner with the employer’s health plan carrier.

Source: EHIR and Carrum Health via PRNewswire, May 4, 2022

***

COMMENTS APPRECIATED

Thank You

***

***

***

COVID, Inflation and Value Investing

Millennial Investing

***

By Vitaliy Katsenelson, CFA

***

***

COVID, Inflation, and Value Investing: Millennial Investing
I was recently interviewed by Millennial Investors podcast. They sent me questions ahead of time that they wanted to ask me “on the air”. I found some of the questions very interesting and wanted to explore deeper. Thus, I ended up writing answers to them (I think through writing). You can listen to the podcast here. 

By the way, I often get asked how I find time to write. Do I even do investment research? Considering how much content I’ve been spewing out lately, I can understand these questions. In short – I write two hours a day, early in the morning (usually from 5–7am), every single day. I don’t have time-draining hobbies like golf. I rarely watch sports. I have a great team at IMA, and I delegate a lot. I spend the bulk of my day on research because I love doing it. 

This is not the first time I was asked these questions. If you’d like to adapt some of my daily hacks in your life, read this essay.

How has Covid-19 changed the game of value investing?

Value investing has not changed. Its fundamental principles, which I describe in “The Six Commandments of Value Investing,” (one-click sign up here to receive it in your inbox) have not changed one iota. The principles are alive and well. What has changed is the environment – the economy. 

I learned this from my father and Stoic philosophers: You want to break up complex problems into smaller parts and study each part individually. That way you can engage in more-nuanced thinking. 

Let’s start with what has not changed. Our desire for in-person human interaction has not changed. At the beginning of the pandemic, we (including yours truly) were concerned about that. We were questioning whether we were going to ever be able to shake hands and hug again. However, the pandemic has not changed millions of years of human evolution – we still crave human warmth and personal interaction. We need to keep this in mind as we think about the post-pandemic world. 

What we learned in 2021 is that coronavirus mutations make predicting the end of the pandemic an impossible exercise. From today’s perch it is safe to assume that Covid-19 will become endemic, and we’ll learn how to live with it. I am optimistic on science. 

Let’s take travel, for example. Our leisure travel is not going to change much – we are explorers at heart, and as we discovered during the pandemic, we crave a change in scenery. However, I can see business travel resetting to a lower base post-pandemic, as some business trips get resolved by simple Zoom calls. Business travel is about 12% of total airline tickets, but those revenues come with much higher profit margins for airlines. 

Work from home. I am still struggling with this one. The norms of the 20th-century workplace have been shaken up by the pandemic. Add the availability of new digital tools and I don’t need to be a Nostradamus to see that the office environment will be different. 

By how much? 

The work from home genie is out of the bottle. It will be difficult to squeeze it back in. My theory right now is that customer support, on-the-phone types of jobs may disproportionately get decentralized. The whole idea of a call center is idiotic – you push a lot of people into a large warehouse-like office space, where they sit six feet apart from each other and spend eight hours a day on the phone talking to customers without really interacting with each other. Current technology allows all this work to be done remotely.

On another hand, I can see that if you have a company where creative ideas are sparked by people bumping into each other in hallways, then work from home is less ideal. But again, I don’t think about it in binary terms, but more like it’s a spectrum. Even for my company. Before the pandemic, half of our folks worked outside of the IMA main office in Denver. Most of our future hires will be local, as I believe it is important for our culture. However, we provide a certain number of days a year of remote work as a benefit to our in-office employees. 

From an investment perspective, we are making nuanced bets on global travel normalizing. We don’t own airlines – never liked those businesses, never will. Most of their profitability comes from travel miles – they became mostly flying banks. 

Office buildings I also put into a too-difficult-to-call pile. There was already plenty overcapacity in office real estate before the pandemic, and office buildings were priced for perfection. The pandemic did not make them more valuable. Maybe some of that overcapacity will get resolved through conversion of office buildings into apartments. By the way, this is the beauty of having a portfolio of 20–30 stocks: I don’t need to own anything I am not absolutely head over heels in love with.

What is the importance of developing a process to challenge your own beliefs?

My favorite quote from Seneca is “Time discovers truth.” My goal is to discover the truth before time does. I try to divorce our stock ownership from our feelings. 

Let me give you this example. If you watch chess grandmasters study their past games, they look for mistakes they have made, moves they should have made, so in the future they won’t make the same mistake twice. I have also noticed they say “white” and “black,” not “I” and “the opponent.” This little trick removes them from the game so that they can look for the best move for each side. They say “This is the best move for white”; “This is the best move for black.”

You hear over and over again from people like Warren Buffett and other value investors that we should buy great companies at reasonable prices, and I’d like to dig deeper on that idea and its two key parts, great companies and reasonable prices. Could you tell us what it takes for a company to qualify as a “great” company?

This question touches on Buffett’s transformation away from Ben Graham’s “statistical” approach, i.e., buying crappy companies that look numerically cheap at a significant discount to their fair value, to buying companies that have a significant competitive advantage, a high return on capital, and a growth runway for their earnings. 

The first type of companies often will not be high-quality businesses and will most likely not be growing earnings much. Let’s say the company is earning $1. Its earnings power will not change much in the future – it is a $5 stock trading at 5 times earnings. If its fair value is $10, trading at 10 times earnings, And if this reversion to fair value happens in one year, you’ll make 100%. If it takes 5 years then your return will be 20% a year (I am ignoring compounding here). So time is not on your side. If it takes 10 years to close the fair value gap, your return halves. Therefore you need a bigger discount to compensate for that. Maybe, instead of buying that stock at a 50% discount, you need to buy a company that is not growing at a 70% discount, at $3 instead of $5. This was pre-Charlie Munger, “Ben Graham Buffett.” 

Then Charlie showed him there was value in growth. If you find a company that has a moat around its business, has a high return on capital, and can grow earnings for a long time, its statistical value may not stare you in the face. But time is on your side, and there is a lot of value in this growth. If a company earns $1 today and you are highly confident it will earn $2 in five years, then over five years, if it trades at 10 times earnings, a no-growth company may be a superior investment if the valuation gap closes in less than 5 years, while one with growing earnings is a superior investment past year 5. 

Both stocks fall into the value investing framework of buying businesses at a discount to their fair value, looking for a margin of safety. With the second one, though, you have to look into the future and discount it back. With the first one, because the lack of growth in the future is not much different from the present, you don’t have to look far.

There is a place for both types of stocks in the portfolio – there are quality companies that can still grow and there are companies whose growth days are behind them. In our process we equalize them by always looking four to five years out. 

What qualifies as a “reasonable price”? 

We are looking for a discount to fair value where fair value always lies four to five years out. In our discounted cash flow models, we look a decade out. Our required rate of return and discount to fair value will vary by a company’s quality. There are more things that can go wrong with lower-quality companies than with the better ones. High-quality companies are more future-proof and thus require lower discount rates. We are incredibly process-driven. We have a matrix by which we rate all companies on their quality and guestimate their fair value five years out, and this is how we arrive at the price we want to pay today. 

Why do you believe that buying great companies sometimes isn’t a great investing strategy?

Because that is first-level thinking, which only looks at what stares you in the face – things that are obvious even to untrained eyes and thus to everyone. First-level thinking ignores second-order effects. If everyone knows a company is great, then its stock price gets bid up and the great company stops being a great investment. With second-level thinking you need to ask an additional question, which in this case is, what is the expected return? Being a great company is not enough; it has to be undervalued to be a good stock. 

We are looking for great companies that are temporarily (key word) misunderstood and thus the market has fallen out of love with them. Over the last decade, when interest rates only declined, first-level thinking was rewarded. It almost did not matter how much you paid for a stock. If it was a great company, its valuations got more and more inflated. 

You’re a big advocate of having a balanced investment approach that is able to weather all storms. What investments have you found that you expect will be able to hold their buying power if inflation persists through 2022 and 2023?


There are many different ways to answer this question. In fact, every time I give an answer to this question I arrive at a new answer. You want to own companies that have fixed costs. You want assets that have a very long life. I am thinking about pipeline companies, for instance. They require little upkeep expense, and their contracts allow for CPI increases (no decreases); thus higher inflation will add to their revenue while their costs will mostly remain the same. 

We own tobacco companies, too. I lived in Russia in the early ’90s when inflation was raging. I smoked. I was young and had little money. I remember one day I discovered that cigarette prices had doubled. I had sticker shock for about a day. I gave up going to movies but somehow scraped up the money for cigarettes. 

Whatever answer I give you here will be incomplete. It’s a complex problem, and so each stock requires individual analysis. In all honesty, you have to approach it on a case-by-case basis. 

With higher inflation, you’d expect bond yields to rise, since bond investors will demand a higher return to keep pace with inflation. However, CPI inflation is currently over 6%, and the 10-year Treasury is sitting at 1.5%. Why haven’t we seen Treasury yields rise more, and what does it mean for investors if a spread this wide persists?

I am guessing here. My best guess is that so far investors have bought into the Fed’s rhetoric that inflation is transitory due to the economy’s rough reopening and supply chain problems. I wrote a long article on this topic. To sum up, part of the inflation is transitory but not all of it. 

I am somewhat puzzled by the labor market today. I’ve read a few dozen very logical explanations for the labor shortage, from early retirement of baby boomers to the pandemic triggering a search for the meaning of life and thus people quitting dead jobs and all becoming Uber drivers or starting their own businesses. Labor is the largest expense on the corporate income statement, and if it continues to be scarce then inflation will persist. 

I read that employees are now demanding to work from home because they don’t want to commute. The labor shortages are shifting the balance of power to employees for the first time in decades. This will backfire in the long run, as employers will be looking at how to replace employees with capital, in other words, with automation. If you run a fast-food restaurant and your labor costs are up 20–30% or you simply cannot hire anyone, you’ll be looking for a burger flipping machine. 

If we continue to run enormous fiscal deficits, then the US dollar will crack. The pandemic has accelerated a lot of trends that were in place. We were on our way to losing our reserve currency status. Let me clarify: That is going to be a very slow, very incremental process. It will be slow because currency pricing is not an absolute but a relative endeavor, and the alternatives out there are not great. But two decades ago the US dollar was a no-brainer decision and today it is not. So we’ll see countries slowly diversifying away from it. A weaker US dollar means higher, non transitory inflation. 

You wrote The Little Book of Sideways Markets, in which you point out that history shows that a sideways market typically occurs after a secular bull market. With the role that the Federal Reserve plays in the financial markets, do you still anticipate that valuations will normalize in the coming years?

I say yes, in part because declining interest rates have pushed all assets into stratospheric valuations. Rising bond yields and valuations pushed heavenward are incompatible. Yes, I expect valuations to do what they’ve done every time in history: to mean revert. In big part this will depend on interest rates, but if rates stay low because the economy stutters, then valuations will decline – this is what happened in Japan following their early-1990s bubble. Interest rates went to zero or negative, but valuations declined. 

The stock market today is very much driven by the Federal Reserve’s monetary policy. Is there a point at which they are able to take the gas off the pedal and allow markets to normalize?

I am really puzzled by this. We simply cannot afford higher interest rates. Going into the pandemic our debt-to-GDP was increasing steadily despite the growing economy. In fact, you could argue that most of our growth has come from the accumulation of debt (the wonders of being the world’s reserve currency). Our debt has roughly equaled our GDP, and all of our economic growth in some years equaled the growth in government debt.

During the pandemic we added 40% to our debt in less than two years. We have higher debt-to-GDP than we had during WWII. After the war we reduced our debt. Also, we were a different economy then – we were rebuilding both the US and Europe. As a society we had a high tolerance for pain. 

Just like debt increases stimulate growth, deleveraging reduces growth. Also, I don’t think politicians or the public care about high debt levels. So far debt has only brought prosperity. However, higher interest rates would blow a huge hole in government budgets. If the 10-year Treasury rises a few percentage points, interest rates will increase by the amount we spend on national defense. One thing I am certain about is that our defense spending will not decline, so higher interest rates will lead to money printing and thus inflation. 

I am also puzzled by the impact of higher interest rates on the housing market. Housing will simply become unaffordable if interest rates go up a few percentage points. Loan-to-income requirements will price a huge number of people out of the market, and housing prices will have to decline. This Higher rates will also reduce the number of transactions in the real estate market, because people will be locked into their 2.5% mortgages, and if they sell they’d have to get 4-5-6% mortgages. There are a lot of second-order effects that we are not seeing today that will be obvious in hindsight. Housing prices drive demand in adjacent sectors such as home improvement. And think of the impact of higher rates on any large purchase, for example a car. 

We’re seeing the continuing rise of China has a big player in the global economy, and I know you like to invest internationally. As a value investor, how do you think about China’s rise as a global powerhouse and how it might affect the financial markets?

During the Cold War there were two gravitational centers, and as a country you had to choose one – you were either with the Soviets or with the West. Something similar will likely transpire here, too. I have to be careful using the Cold War analogy, because the Cold War was driven by ideology – it was communism vs. capitalism. Now the tension is driven by economic competition and our unwillingness to pass the mantle of global leader to another country. 

We are drawing red lines in technology. Data is becoming the new oil. China is using data to control people, and we want to make sure they don’t have control over our data. Therefore, the West wants to make sure that our technology is China-free. The US, Europe, and India will likely be pursuing a path where Chinese technology and Chinese intellectual property are largely disallowed. We have already seen this happening with Huawei being banned from the US and Western Europe. Other countries, including Russia, will have to make a choice. Russia will go with China.

Also, we are concerned that most chip production is centered in Taiwan, which at some point may be grabbed by China. The technological ecosystem would then have to undergo a significant transformation. This has already started to happen as we begin to bring chip production back to the US and Europe. 

The pandemic made us realize that globalization had made us reliant on the kindness of strangers, and we found we could not even get facemasks or ventilators. 

Globalization was deflationary; deglobalization will be inflationary.

This increased tension between countries has led to your investing in the defense industry. Could you tell us how you think about this industry? 

Despite the rise of international tensions, the global defense industry has been one of sectors that still had reasonable (sometimes unreasonably good) valuations. We have invested in half a dozen US and European defense companies. The US defense budget is unlikely to decline in the near future. There is a common misperception that Republicans love defense and Democrats hate it. Those may be party taglines, but history shows that defense spending has been driven by macro factors – it did not matter who was the occupant of the White House. 

There are a lot of things to like about defense businesses. They are an extension of the US or European governments. Most of them are friendly monopolies or duopolies. They have strong balance sheets, good returns on capital, and predictable and growing (maybe even accelerating) demand. They are noncyclical. They have inflation escalators built into their contracts. I don’t have to worry about technological disruptions. They are also a good macro hedge.

We added to our European defense stocks recently for several reasons. Europe has underinvested in defense, relying on the US Yet we have shown time and again that we may not be as dependable as we once were. 

***

COMMENTS APPRECIATED

Thank You

Subscribe to the Medical Executive-Post

***

***

PODCAST: In-Patient Psychiatric Care

By Eric Bricker MD

***

***

RELATED: https://medicalexecutivepost.com/2013/02/13/a-review-of-mental-healthcare-provider-types/

***

COMMENTS APPRECIATED

Thank You

***

ORDER: https://www.barnesandnoble.com/w/risk-management-liability-insurance-and-asset-protection-strategies-for-doctors-and-advisors-david-edward-marcinko/1137103900?ean=9781498725989

***

***

BUSINESS MANAGEMENT STUDY: Physician Vertical Integration

***

BY HEALTH CAPITAL CONSULTANTS, LLC.

DEFINITION: Vertical integration is an arrangement in which the supply chain of a company is integrated and owned by that company. Usually each member of the supply chain produces a different product or service, and the products combine to satisfy a common need.

CITE: https://www.r2library.com/Resource/Title/0826102549

***

Study: Vertical Integration Not Financially Beneficial for Physicians


A study released in the December 2021 issue of Health Affairs examined the correlation between hospital/health system ownership of physician practices and physician compensation. While a number of studies have analyzed the “rapidly growing trend” of vertical integration from the hospital/health system perspective, this is the first study to evaluate vertical integration from the physician practice perspective.

This Health Capital Topics article will discuss the study’s findings and potential implications. (Read more…) 

***

***

COMMENTS APPRECIATED

Thank You

Subscribe to the Medical Executive-Post

***

***

The RETURN of Paper Dental Records?

By Darrell Pruitt DDS

***

***

More reasons to stick with paper if you haven’t yet become paperless, Doc 

“Paying Ransomware Paints Bigger Bullseye on Target’s Back – Ransomware attackers often strike targets twice, regardless of whether the ransom was paid. Paying ransomware attackers doesn’t pay off and often paints a bigger target on a victim’s back. Eighty percent of ransomware victims that paid their attackers were hit a second time by the malware scourge.” – Threatpost, June 8, 2022.

A dentist can avoid the second ransomware attack by returning to paper … What? Yeah. I said it.

“New ransomware numbers come from a Cybereason’s April ransomware survey of 1,456 cybersecurity professionals. According to the gated report (registration required), victims that were successfully extorted were not only targeted a second time, but frequently data encrypted by criminals later became unusable during the decryption process because of corruption issues.”

OR – one can retire!

***

***

COMMENTS APPRECIATED

Thank You

***

***

***

SURVEY: Tele-Health Weekly Visits

By MCOL

***

***

% Providing Video Telehealth Visits to 5+ Patients Per Week

 •  Primary Care Physician: 74%
 •  Behavioral Health Provider: 88%
 •  Registered Nurse: 62%
 •  Medical Assistant: 80%

Source: RAND, “Experiences of Health Centers in Implementing Telehealth Visits for Underserved Patients During the COVID-19 Pandemic,” May 2022

***

COMMENTS APPRECIATED

Thank You

***

***

***

Understanding Hospital Financial Net Working Capital

Lower is Better

[By Staff Reporters]

Join Our Mailing List 

Net working capital is the difference between current assets and current liabilities. The lower the net working capital, the more economically efficient the medical care provided. Some important definitions and ratios for hospitals include those immediately below:

  • Days Sales Outstanding: AR/(net sales/365)

Year-end receivables net of allowances for doubtful accounts, plus financial receivables divided by net sales per day. A decrease in days sales outstanding (DSO) represents an improvement in cash flows while an increase represents deterioration. The hospital industry average is 30 days.

  • Days Payable Outstanding: AP/(total expenses [less depreciation and amortization] / 365)

Year-end payables divided by expenses per day. An increase in days payable outstanding (DPO) is an improvement, while a decrease is not. Payables exclude accrued expenses. Hospital industry average is 20 days.

  • Days Inventory Outstanding: Inventory/(net sales/365)

Year-end inventories divided by sales per day. A decrease in days inventory outstanding (DIO) is an improvement, while an increase may be a sales deterioration. Hospital industry average is 4 days.

  • Days Working Capital: (AR + inventory – AP)/net sales/365)

Year-end net working capital (service receivables plus inventory, minus AP) divided by sales per day. The lower the better. Hospital industry average is 14 days.

Assessment

For more health economics and finance terms and definitions, please review the following:

Product DetailsProduct DetailsProduct Details

Product Details  Product Details

    Product Details

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Link: http://feeds.feedburner.com/HealthcareFinancialsthePostForcxos

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

DICTIONARIES: http://www.springerpub.com/Search/marcinko
PHYSICIANS: www.MedicalBusinessAdvisors.com
PRACTICES: www.BusinessofMedicalPractice.com
HOSPITALS: http://www.crcpress.com/product/isbn/9781466558731
CLINICS: http://www.crcpress.com/product/isbn/9781439879900
BLOG: www.MedicalExecutivePost.com
FINANCE: Financial Planning for Physicians and Advisors
INSURANCE: Risk Management and Insurance Strategies for Physicians and Advisors

Product DetailsProduct Details

Product Details

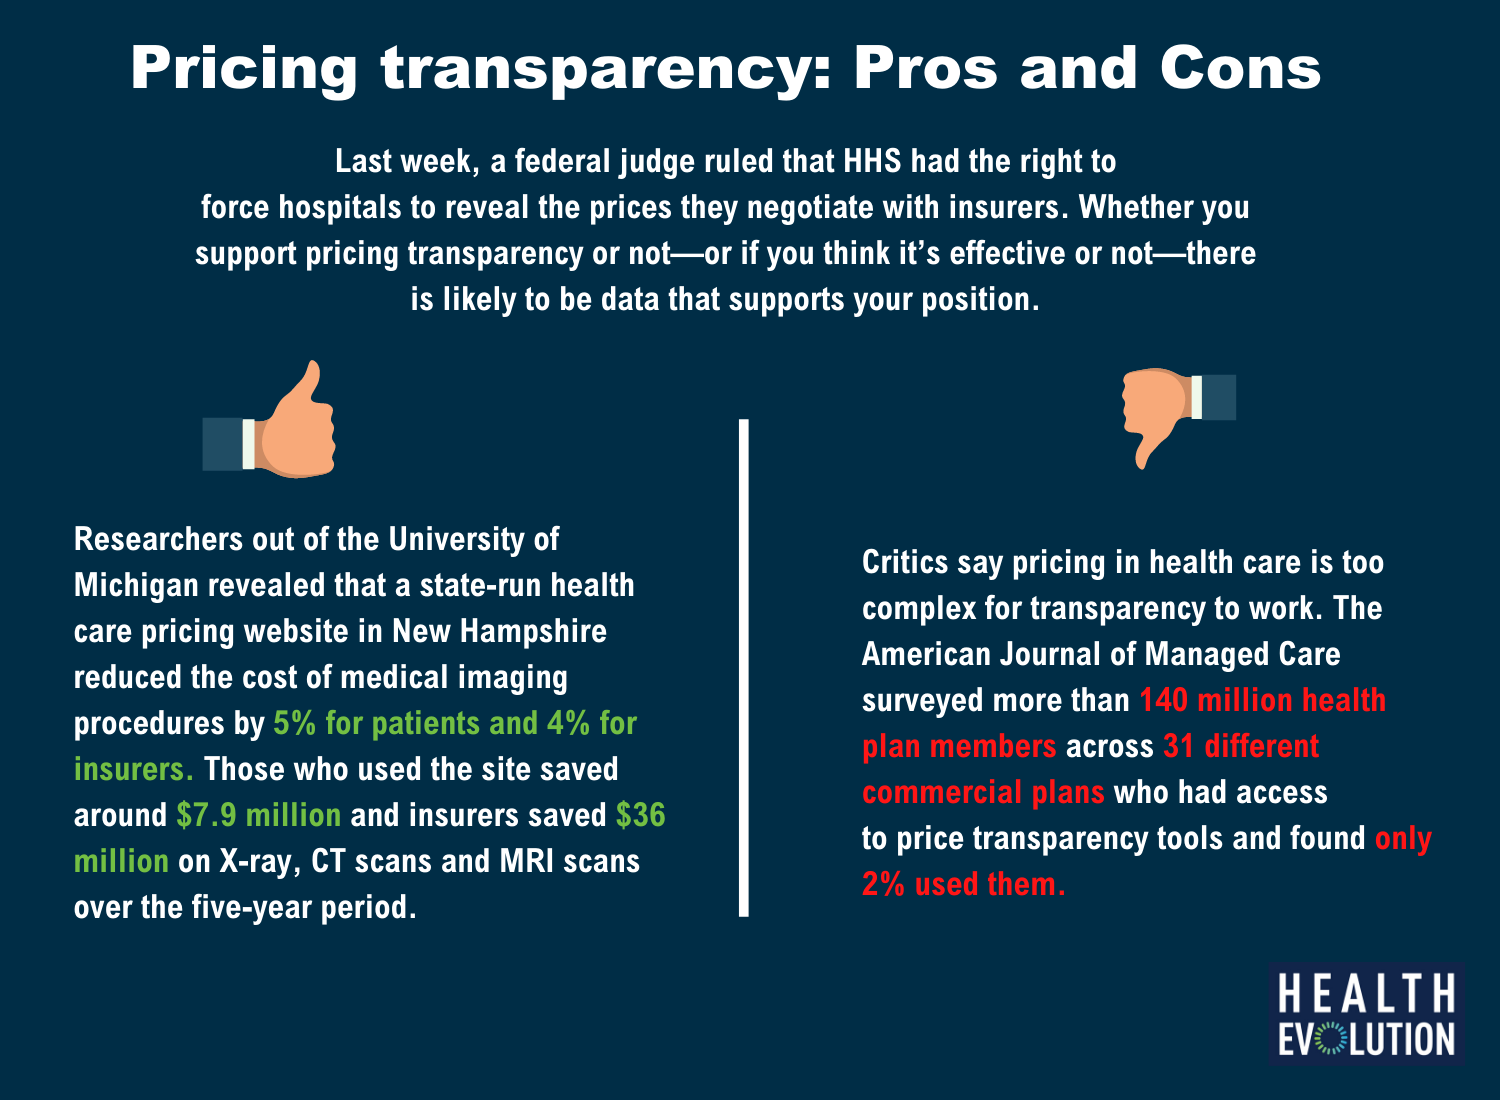
SURVEY: Resources Offered by Health Insurance Plan Transparency Tool

By MCOL

***

***

Percentage of Resources

 •  Finding in-network providers: 72%
 •  Telehealth: 55%
 •  Ability to select PCP online: 53%
 •  Help navigating benefits and healthcare options: 50%
 •  Cost estimates for healthcare services: 50%
 •  Status of deductible: 49%
 •  Reviews of doctors and facilities: 46%
 •  Online appointment scheduling: 41%
 •  Financial incentives/rewards for choosing cost-effective care: 25%

Source: Health Sparq, “2022 Annual Consumer Sentiment Benchmark Report,” January 2022

CITE: https://www.r2library.com/Resource/Title/082610254

***

COMMENTS APPRECIATED

Thank You

***

***

***

UPDATE: ARK Innovation, Dr. Burry, the Yield/Equity Push-Pull and Monkeypox

By Staff Reporters

***

***

Cathie Wood’s ARK Innovation fund composed of high-growth tech stocks is up 17% since hitting rock bottom on May 11th compared to the S&P’s 4.4% gain over the same period.

Americans are burning through their savings and might virtually exhaust them within months. Colleague Michael Burry MD warned the US economy could suffer once consumers empty out their savings accounts. “The Big Short” investor expects rising debt and reduced savings to hit growth and company profits.

The push and pull between bond yields and equities continue with stock gains kept in check by a drop in Treasuries that pushed a swath of rates above 3%.

The CDC raised its alert level for Monkeypox to level 2 recommending that travelers wear masks, among other health measures.

***

COMMENTS APPRECIATED

Thank You

***

***

Organizational Economics and Physician Practices

N.B.E.R.

By James B. Rebitzer & Mark E. Votruba

Economists seeking to improve the efficiency of health care delivery frequently emphasize two issues: the fragmented structure of physician practices and poorly designed physician incentives. This decade old paper analyzes these issues from the perspective of organizational economics.

We begin with a brief overview of the structure of physician practices and observe that the long anticipated triumph of integrated care delivery has largely gone unrealized. We then analyze the special problems that fragmentation poses for the design of physician incentives. Organizational economics suggests some promising incentive strategies for this setting, but implementing these strategies is complicated by norms of autonomy in the medical profession and by other factors that inhibit effective integration between hospitals and physicians. Compounding these problems are patterns of medical specialization that complicate coordination among physicians.

We conclude by considering the policy implications of our analysis – paying particular attention to proposed Accountable Care Organizations.

***

READ HERE: https://www.nber.org/papers/w17535

ASSESSMENT: What has changed this past decade; if anything? Your thoughts are appreciated.

***

***

CONTACT: Ann Miller RN MHA

INVITATIONS: https://medicalexecutivepost.com/dr-david-marcinkos-bookings/

MarcinkoAdvisors@msn.com

Ph: 770-448-0769

Second Opinions: https://medicalexecutivepost.com/schedule-a-consultation/

THANK YOU

***

PODCASTS: Health Economics and the AMA

By Professor Jon

***

***

PODCAST: https://www.youtube.com/watch?v=fwYYae_U1OI

PODCAST: https://medicalexecutivepost.com/2022/05/30/ama-to-teach-medical-students-about-health-economics/

***

***

***

***

COMMENTS APPRECIATED

Thank You

***

Risk Aversion and Investment Alternatives

Join Our Mailing List

Understanding Financial Tolerance in the New Era

[By Dr. David E. Marcinko MBA and Staff Reporters]

Some physicians and financial planners prefer to use a specific approach in determining these difficult-to-determine areas, in lieu of one of several psychological tests that are currently available.

Examples of this specific approach follow.

Investment Temperament

Which statement best describes your investment temperament? Please indicate by ranking the items below from 1 to 4, with 1 being the most descriptive and 4 being the least descriptive. Also, please indicate the extent of your risk aversion by indicating what percentage of your assets you would feel comfortable investing in each category (for example, 50% in the first category, 25% in the second, etc.).

***

Numerical   Percentage  
ranking   allocation  
* I prefer only the safest of investments.
* I am interested only in “blue-chip” investments.
* An occasional risk is worth the effort for above-average potential reward.
* I’m willing to put everything on the line if the potential reward is large enough.

Listed below are various forms of investments. Please indicate your familiarity with each.

  Familiarity
Description High   Low
Certificates of deposit 5 4 3 2 1
Treasury bills 5 4 3 2 1
Other short-term fixed income 5 4 3 2 1
Stocks 5 4 3 2 1
U.S. government bonds 5 4 3 2 1
Corporate bonds 5 4 3 2 1
Municipal bonds 5 4 3 2 1
Mutual funds 5 4 3 2 1
Real estate—direct ownership 5 4 3 2 1
Real estate—limited partnerships 5 4 3 2 1
Oil and gas 5 4 3 2 1
Collectibles 5 4 3 2 1
Precious metals 5 4 3 2 1
Insurance products 5 4 3 2 1

Assessment

Any other thoughts on behavioral finance topics, like this?

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Link: http://feeds.feedburner.com/HealthcareFinancialsthePostForcxos

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

DICTIONARIES: http://www.springerpub.com/Search/marcinko
PHYSICIANS: www.MedicalBusinessAdvisors.com
PRACTICES: www.BusinessofMedicalPractice.com
HOSPITALS: http://www.crcpress.com/product/isbn/9781466558731
CLINICS: http://www.crcpress.com/product/isbn/9781439879900
BLOG: www.MedicalExecutivePost.com
FINANCE: Financial Planning for Physicians and Advisors
INSURANCE: Risk Management and Insurance Strategies for Physicians and Advisors

Product Details  Product Details

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

ACO Home-Visit Initiatives

ACCOUNTABLE CARE ORGANIZATIONS

By MCOL and Charlene Ice

***

ACOs That Offer 6 Primary Care Services

  • home-based primary care: 37%
  • care coordination: 24%
  • care transitions support: 13%
  • addressing social needs: 13%
  • acute hospital-level services: 11%
  • palliative care services: 2%

Notes: From an article entitled, “Characteristics of Home-Based Care Provided by Accountable Care Organizations,” by Robert E. Mechanic, MBA, Jennifer Perloff, PhD, Amy R. Stuck, PhD, RN, Christopher Crowley, PhD. In a 2019 ACO survey, 40 out of 151 responding ACOs reported formal home-visit initiatives serving high-need, high-cost patients.

Source: The American Journal of Managed Care, May 12, 2022
Source URL: https://www.ajmc.com/view/characteristics-of-home-based-care…

***

COMMENTS APPRECIATED

Thank You

***

***

***

Prioritizing Mental Health Care In America

By NIHCM Infographics

***

Data Insights

***

***

By the end of 2021, Americans found themselves in one of the worst nationwide mental health crises in years. Nearly 1 in 5 U.S. adults experience a mental illness each year, or more than 50 million people. Unfortunately, less than half of the people in need ever receive the mental health care they require. Due to physician burnout, a workforce shortage, and poor funding, this country has long struggled with handling the growing mental health crisis and providing equitable access to behavioral health care.

The mental health system in America may be largely broken, but conditions are ideal for transforming the system with scientific advances, improved coverage, and political consensus on the importance of mental health. Goals once thought to be long out of reach may soon be possible.

CITE: https://www.r2library.com/Resource/Title/082610254

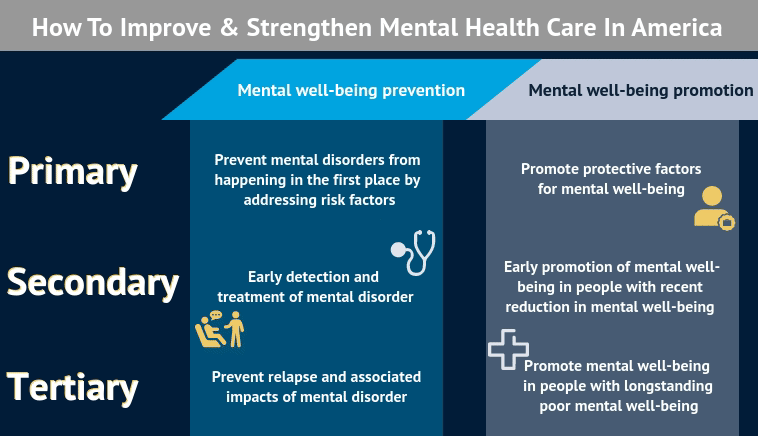
This NIHCM infographic highlights the many challenges contributing to America’s mental health crisis as well as steps to improve and strengthen mental health care and the behavioral health industry and promote individual resiliency.

NIHCM: https://tinyurl.com/3whz69vk

ME-P: https://medicalexecutivepost.com/2022/06/02/medical-workplace-violence-prevention-guidelines/

***

***

****

Capitalism Blame Does Nothing to Offer Solutions

Join Our Mailing List

Blaming it on capitalism does nothing to offer any real solutions

Rick Kahler MS CFP

By Rick Kahler MSFS CFP®

http://www.KahlerFinancial.com

Recently, a respected colleague noted that the “capitalistic goal of accumulation, consumption, and collecting” is responsible for a collective mindset in Americans that “I consume, therefore I am” and “more is better.” He passionately feels the “more is better capitalistic mentality” assures a predictable future of dwindling resources. He is not alone in his views.

Certainly, identifying our self-worth by what we accumulate or spend does not produce emotional, physical, or financial well-being.

Those who embrace a money script of “I consume, therefore I am” are likely to eventually encounter financial and emotional pain. Either they will run out of money to spend, lack products to buy, or discover the futility of trying to use money and possessions as a substitute for genuine self-worth.

More is Better?

What I found curious was my colleague’s attribution of the money script “more is better” as the product of capitalism. That money script has been around a lot longer than capitalism, which according to Investopedia originated during the Middle Ages when a variety of factors, including a labor shortage caused by the Black Plague, caused the collapse of the manorial system. More is better” was part of the human condition much earlier.

For example, in the Hebrew Scriptures, Ecclesiastes 5:10 says, “Whoever loves money never has money enough; whoever loves wealth is never satisfied with his income.”

Greed

Greed, whether for money or food or anything else, is not produced by an economic model. Whether people live under a capitalistic, socialistic, or communist system—or in a Stone Age tribal group—greed is alive and well in all of them. Every human being experiences it in some way and on some level. It has been considered one of the seven deadly sins since the early days of the Christian church.

Definition

“Capitalism” is defined by Merriam-Webster as “an economic system characterized by private or corporate ownership of capital goods, by investments that are determined by private decision, and by prices, production, and the distribution of goods that are determined mainly by competition in a free market.”

There is nothing in that definition about greed or any goals of “accumulation, consumption, and collecting.”

Core to capitalism is a method of distributing limited resources in the most efficient manner possible, where the dynamics of the free market and competition drive down prices and improve quality. I find no other economic system that delivers this outcome. In fact, systems controlled by central planning have a track record of producing the opposite: economies where shortages prevail and those in charge prosper on the backs of the masses.

Research

Research shows capitalism has lifted more people out of poverty than any other economic system. Since 1945 the number of those living below the poverty line has decreased 57%, from 35% to 15%, while income inequality has risen just 15%. Any American earning over $30,600 is in the top 1% of income earners globally. Even the bottom 1% of Americans are in the top 33% of income earners globally.

Certainly there are business owners and wealthy people who are greedy, selfish, and materialistic, because such people are found in every walk of life. These traits are not tied to any particular economic system. They are signs of people who are trying to satisfy spiritual and emotional needs with material things that can never meet those needs.

***

buy-sell-merge

***

Assessment

Because one of the qualities that helps people create financial security is frugality, I actually agree with my colleague that excess consumption is often destructive and can be a genuine problem. Blaming it on capitalism, however, does nothing to offer any real solutions.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

The SAFE-HAVEN Demand

By Staff Reporters

***

***

Stocks are riskier than bonds. But the reward for investing in stocks over the long haul is greater. Still, bonds can outperform stocks over short periods. Safe Haven Demand shows the difference between Treasury bond and stock returns over the past 20 trading days.

Bonds do better when investors are scared. The Fear & Greed Index uses increasing safe haven demand as a signal for Fear.

CITE: https://www.r2library.com/Resource/Title/082610254

***

COMMENTS APPRECIATED

Thank You

***

***

Whatever Happened to the Invisible Hand of Capitalism?

Join Our Mailing List

The Invisible Hand of Capitalism?

vitaly

By Vitaliy Katsenelson CFA

Just as the well-meaning economist of the Soviet Union didn’t know the correct price of sugar, nor do the good-intentioned economists of our global central banks know where interest rates should be.

***

246_1

***

Assessment

Even more important, they can’t predict the consequences of their actions.

Here’s why?

http://contrarianedge.com/2016/03/16/whatever-happened-to-the-invisible-hand-of-capitalism/

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

SURVEY: On Nurse Caregivers and Unions

By MCOL

***

***

Nurses Survey: The 4 Takeaways

 •  87% of patients or their caregivers feel some level of stigma associated with their or the person in their care’s current health condition.
 •  44% reported feeling embarrassed to talk about their current health condition.
 •  43% felt their health condition isn’t something that’s regularly talked about and is rarely represented in the media.
 •  99% patients and their caregivers say that stigma can negatively impact or slow perceived healing of a patient with a current health condition.

Source: Convatec Group Plc via PRNewswire, May 18, 2022

UNIONS: https://www.msn.com/en-us/health/medical/unions-tempt-nurses-to-change-their-principles/ar-AAY2cUg?li=BBnb7Kz

***

COMMENTS APPRECIATED

Thank You

***

***

***

PODCAST: Ten Largest Medical Device Companies

By Eric Bricker MD

***

***

COMMENTS APPRECIATED

Thank You

***

***

***

Transformational Business Skills for Doctor Entrepreneurs

THE BUSINESS OF MEDICAL PRACTICE [Health 2.0]

Textbook Review

***

SECOND OPINIONS: https://medicalexecutivepost.com/schedule-a-consultation/

INVITE DR. MARCINKO: https://medicalexecutivepost.com/dr-david-marcinkos-bookings/

SPONSOR: http://www.CertifiedMedicalPlanner.org

***

About Medical Workplace Violence

Join Our Mailing List

UPDATE

At least three people are dead and multiple people are injured following a shooting at the Natalie Building at St. Francis Hospital in Tulsa, Oklahoma.

Link: https://www.msn.com/en-us/news/crime/at-least-3-dead-multiple-people-injured-in-shooting-at-oklahoma-medical-office/ar-AAXYITO?li=BBnb7Kz

More than Physical Assault

[By Staff Reporters and Dr. David E. Marcinko MBA]

Business Med PracticeWorkplace violence is more than physical assault.

According to trauma specialist Eugene Schmuckler; PhD, MBA, CTS opining and writing in www.BusinessofMedicalPractice.com; workplace violence is any act in which a person is abused, threatened, intimidated, harassed, or assaulted in his or her employment. Swearing, verbal abuse, playing “pranks,” spreading rumors, arguments, property damage, vandalism, sabotage, pushing, theft, physical assaults, psychological trauma, anger-related incidents, rape, arson, and murder are all examples of workplace violence.

The RNANS

The Registered Nurses Association of Nova Scotia [RNANS], a leading study group, defines violence as “any behavior that results in injury whether real or perceived by an individual, including, but not limited to, verbal abuse, threats of physical harm, and sexual harassment.” As such, medical workplace violence includes:

· threatening behavior — such as shaking fists, destroying property, or throwing objects;

· verbal or written threats — any expression of intent to inflict harm;

· harassment — any behavior that demeans, embarrasses, humiliates, annoys, alarms, or verbally abuses a person and that is known or would be expected to be unwelcome. This includes words, gestures, intimidation, bullying, or other inappropriate activities;

· verbal abuse — swearing, insults, or condescending language;

· muggings — aggravated assaults, usually conducted by surprise and with intent to rob; or

· physical attacks — hitting, shoving, pushing, or kicking.

Cause and Affect

Workplace violence can be brought about by a number of different actions in the workplace. It may also be the result of non-work related situations such as domestic violence or “road rage.” Workplace violence can be inflicted by an abusive employee, a manager, supervisor, co-worker, customer, family member, patient, physician, nurse, or even a stranger.

The UI-IPRC 

The University of Iowa – Injury Prevention Research Center [UI-IPRC] classifies most workplace violence into one of four categories.

· Type I Criminal Intent — Results while a criminal activity (e.g., robbery) is being committed and the perpetrator had no legitimate relationship to the workplace.

· Type II Customer/Client — The perpetrator is a customer or client at the workplace (e.g., healthcare patient) and becomes violent while being assisted by the worker.

· Type III Worker on Worker — Employees or past employees of the workplace are the perpetrators.

· Type IV Personal Relationship — The perpetrator usually has a personal relationship with an employee (e.g., domestic violence in the workplace).

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Link: http://feeds.feedburner.com/HealthcareFinancialsthePostForcxos

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

DICTIONARIES: http://www.springerpub.com/Search/marcinko
PHYSICIANS: www.MedicalBusinessAdvisors.com
PRACTICES: www.BusinessofMedicalPractice.com
HOSPITALS: http://www.crcpress.com/product/isbn/9781466558731
CLINICS: http://www.crcpress.com/product/isbn/9781439879900
ADVISORS: www.CertifiedMedicalPlanner.org
PODIATRISTS: www.PodiatryPrep.com
BLOG: www.MedicalExecutivePost.com
FINANCE: Financial Planning for Physicians and Advisors
INSURANCE: Risk Management and Insurance Strategies for Physicians and Advisors

Product Details 

PODCAST: The “Economy” – How it Affects Everyone

By Rich Helppie

THE COMMON BRIDGE

The Second of a Two-Part Episode with Beata Kirr

***

***

PODCAST LINK: https://tinyurl.com/zrxdxzya

***

COMMENTS APPRECIATED

Thank You

***

PODCAST: Health Insurance Carrier Stock Market Performance

By Eric Bricker MD

***

***

CITE: https://www.r2library.com/Resource/Title/082610254

***

COMMENTS APPRECIATED

Thank You

***

***

***

SURVEY: Affordable ACA Family Coverage

By MCOL

***

Families USA: Uninsured Rate by Quarter •  Q4 2020: 10.3%
 •  Q1 2021: 9.5%
 •  Q2 2021: 9.7%
 •  Q3 2021: 8.9%

Source: Families USA, “ACA’s Promise of Affordable Health Coverage for Families Across America Is at Risk as Pandemic-Era Policies Expire,” March 2022

***

COMMENTS APPRECIATED

Thank You

***

***

On New Issues and Securities Stabilization

Join Our Mailing List

A Primer for Physician Investors and Medical Professionals

By: Dr. David Edward Marcinko; MBA, CMP™

[Editor-in-Chief] http://www.CertifiedMedicalPlanner.org

[PART 3 OF 8]

NEU Dr. Marcinko

NOTE: This is an eight part ME-P series based on a weekend lecture I gave more than a decade ago to an interested group of graduate, business and medical school students. The material is a bit dated and some facts and specifics may have changed since then. But, the overall thought-leadership information of the essay remains interesting and informative. We trust you will enjoy it.

Introduction

Some securities issues move very well, like traditional blue chips stocks (ie., Wallgreen). Some are dogs, like smaller dot.com companies (iixl.com). Then, there are issues that are former darling, but are now ice cold; like PPMCs (i.e., Phycor) and internet stocks (i.e., Dr. Koop).  How far can an underwriting manager go in nudging along an issue that’s not selling well? SEC rules do permit a certain amount of help by the manager, even if this takes on the appearance of price-fixing. This help is called stabilizing the issue.

Simply put, if shortly after a new offering begins, supply exceeds demand, there will be downward pressure on the price. But, the law requires that all purchasers of the new issue pay the official offering price on the prospectus. If public holders of the stock become willing to bail out and accept a low selling price, the investor looking to buy will find he is able to buy stock of the issuer cheaper in the open market than buying it new from the syndicate members.

To prevent such a decline in the price of a security during a public offering, SEC rules permit the manager to offer to buy shares in \ the open market at a bid price at, or just below, the official offering price of the new issue. This is referred to as stabilizing and his bid price is called the stabilizing bid. There is always the risk, in a firm commitment underwriting, that the underwriters will have difficulty selling the new issue. What they can’t sell, they’re “stuck” with. That’s where the term “sticky issue” comes from.

As a physician executive, or potential investor in a new issue, be aware that the best way to get an issue to sell is to increase the compensation to the sales force (i.e., stock broker or Registered Rep).

Another choice is through stabilization. Stabilizing is a permitted form of market manipulation which tends to protect underwriters against loss. It allows the underwriting syndicate (usually through the efforts of the syndicate manager) to stabilize (peg or fix) the secondary market trading price in a new issue at the published public offering price. It works something like this.

When a new issue is selling slowly, some of the investors who initially purchased, may be dissatisfied with the performance of the stock (if it is selling slowly and the underwriters have plenty to sell at the public offering price, this is anything but a hot issue and the security price will not have risen).

This dissatisfaction with performance leads to these investors desiring to sell the securities they have just purchased. If the underwriters are unable to sell at the public offering price, certainly an individual investor will have to take less when bailing out. As market makers begin to trade the stock in the secondary market, they would only be able to compete with the underwriters by offering the stock at a lower price than the public offering  price. This would make it difficult (if not impossible) for the underwriters to distribute the remaining new shares.

In order to prevent this from happening, the managing underwriter (who is usually the one to assume the role of stabilizing underwriter), agrees to purchase back any of the new shares at or just slightly below the public offering price. That is a higher price than any market maker could, in all practicality, bid for the shares. When the shares are repurchased by the stabilizing underwriter, it is as if the initial trade were annulled and never took place so that these new shares are now placed back into the distribution and are sold as new shares at the public offering price. SEC rules do, however, require disclosure of this practice.

Therefore, no syndicate manager may engage in stabilizing unless the following phrase appears in bold print on the inside front cover page of the prospectus:

IN CONNECTION WITH THIS OFFERING, THE UNDERWRITERS MAY OVER ALLOT OR EFFECT TRANSACTIONS WHICH STABILIZE OR MAINTAIN THE MARKET PRICE OF (XYZ COMPANY) AT A LEVEL ABOVE THAT WHICH MIGHT OTHERWISE PREVAIL IN THE OPEN MARKET. SUCH TRANSACTIONS MAY BE EFFECTED ON (NYSE) STABILIZING, IF COMMENCED, MAY BE DISCONTINUED AT ANY TIME.

Of course, it would be manipulation and, therefore, a violation of law, if this “price-pegging” activity continued after the entire new issue was sold out. This activity costs the syndicate manager money which is recouped by levying a syndicate penalty bid against those members of the syndicate whose clients turn shares in on a stabilizing bid.

One way to avoid stabilization is to over allot  to each of the syndicate members. This is the same concept as “over booking” that’s done by the airlines. Most airlines typically sell 5% to 10% more seats than the airplane has knowing that there will be last minute cancellations and no shows. This tends to ensure that the plan will fly full. In the same manner, managing under-writers frequently over allot an additional 10% to each of their syndicate members so that last minute cancellations should still leave the syndicate with sell orders for 100% of the issue. If there are no “drop outs”, one of two things may happen.

  1. The issuer will issue the additional shares (which results in it raising more money).
  2. The issuer will not issue the additional shares and the syndicate will have to go short. Any losses suffered by the syndicate through taking of this short position are shared proportionately by the syndicate members.

Now, what if market conditions and the fervor surrounding a new issue like e-commerce company Ariba,  in 1999, remain so that the issue doesn’t cool down during the cooling off period? Such hot issues are a mixed blessing to be sure.

On the one hand, the issue is a sure sell-out. On the other hand, just how many healthcare investors are going to be told by brokers that additional shares can not be obtained.

Furthermore, the SEC and the NASD/FINRA are vigorous [or should be] in their scrutiny of  proper distribution channels for hot issues. Just what is a “proper” distribution?  It can be summed up in one sentence. Member firms have an obligation to make a “bona fide” public distribution of all the shares at the public offering price. The key to this rule lies within the definition of bona fide public distribution.

While the underwriting procedures for corporate bonds are almost identical to corporate stock, there are significant differences in the underwriting of municipal securities. Municipal securities are exempt from the registration filing requirements or the Securities Act of 1933. A state or local government, in the issuance of municipal securities, is not required to register the offering with the SEC, so there is no filing of a registration statement and there is no prospectus which would otherwise have to be given to investors.

###

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

###

Municipal Underwriting

There are two main methods of financing when it comes to municipal securities. One method is known as negotiated. In the case of a negotiated sale, the municipality looking to borrow money would approach an investment bank and negotiate the terms of the offering directly with the firm. This is really not very different from the above equity discussions.

The other type of municipal underwriting is known as competitive bidding. Under the terms of competitive bidding, an issuer announces that it wishes to borrow money and is looking for syndicates to submit competitive bids. The issue will then be sold to the syndicate which submits the best bid, resulting in the municipality having the lowest net interest cost (lowest expense to the issuer).

If the issue is to be done by a competitive bid, the municipality will use a Notice of Sale to announce that fact. The notice of sale will generally include most or all of the following information.

  • Date, time, and place. This does not mean when the bonds will be sold to the public, but when the issue will be awarded (sold) to the syndicate issuing the bid.
  • Description of the issue and the manner in which the bid is to be made (sealed bid or oral). Type of bond (general obligation, revenue, etc.)
  • Semi-annual interest payment dates and the denominations in which the bonds will be printed.
  • Amount of good faith deposit required, if any.
  • Name of the law firm providing the legal opinion and where to acquire a bid form.
  • The basis upon which the bid will  e awarded, generally the lowest net interest cost.

Since municipal securities are not registered with the SEC, the municipality must hire a law firm in order to make sure that they are issuing the securities in compliance with all state, local and federal laws. This is known as the bond attorney, or independent bond counsel. Some functions are included below:

    1. Establishes the exemption from federal income tax by verifying  requirements for the exemption.
    2. Determines proper authority for the bond issuance.
    3. Identifies and monitors proper issuance procedures.
    4. Examines the physical bond  ertificates to make sure that they are proper
    5. Issues the debt and a legal opinion, since municipal bonds are the only securities that require an opinion.
    6. Does not prepare the official statement.

When medical investors purchase new issue municipal securities from syndicate or selling group members, there is no prospectus to be delivered to investors, but there is a document which is provided to purchasers very similar in nature to a prospectus. It is known as an Official Statement. The Official Statement contains all of the information an investor needs to make a prudent decision regarding a proposed municipal bond purchase.

The formation of a municipal underwriting syndicate is very similar to that for a corporate  issue. When there is a negotiated underwriting, an Agreement Among Underwriters (AAU) is used. When the issue is competitive bid, the agreement is known as a Syndicate Letter. In the syndicate letter, the managing underwriter details all of the underwriting agreements among members of the syndicate. Eastern (undivided) and Western (divided) accounts are also used, but there are  several different types of orders in a municipal underwriting. The traditional types of orders, in priority order, are:

Pre-Sale Order: Made before the syndicate actually offers the bonds. They have first priority over any other order turned in.

Syndicate (group net) Order: Made once the offering is under way at the public offering price. The purchase is credited to each syndicate member in proportion to its allotment. An institutional buyer will frequently purchase” group net”, since many of the firms in the syndicate may consider this buyer to be their client and he wishes to please all of them.

Designated Order: Sales to medical investors (usually healthcare institutions) at the public offering price where the investor designates which member or members of the syndicate are to be given credit.

Member Orders: Purchased  by members of  the syndicate at the take-down price (spread). The syndicate member keeps the full take-down if the bonds are sold to investors, or earns the take-down less the concession if the sale is made to a member of the selling group. Should the offering be over-subscribed, and the demand for the new bonds exceeds the supply, the first orders to be filled are the pre-sale orders. Those are followed by the syndicate (sometimes called group net) orders, the designated orders, and the last orders filled are the member’s.

Finally, be aware that the term bond scale, is a listing of coupon rates, maturity dates, and yield or price at which the syndicate is re-offering the bonds to the public. The scale is usually found in the center of a tombstone ad and on the front cover of the official statement.

One of the reasons why the word “scale” is used is, that like the scale on a piano, it normally goes up. A regular or positive scale is one in which the yield to maturity is lowest on the near term maturities and highest on the long term maturities. This is also known as a positive yield curve, since the longer the maturity, the higher the yield. In times of very tight money, such as in 1980-81, one might find a bond offering with a negative scale.

A negative (sometimes called inverted) scale is just the opposite of a positive one, with, yields on the short term maturities are higher than those on the long term maturities.

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Link: http://feeds.feedburner.com/HealthcareFinancialsthePostForcxos

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

LEXICONS: http://www.springerpub.com/Search/marcinko

PHYSICIANS: www.MedicalBusinessAdvisors.com

PRACTICES: www.BusinessofMedicalPractice.com

HOSPITALS: http://www.crcpress.com/product/isbn/9781466558731

CLINICS: http://www.crcpress.com/product/isbn/9781439879900

ADVISORS: www.CertifiedMedicalPlanner.org

BLOG: www.MedicalExecutivePost.com

Product DetailsProduct DetailsProduct Details

Product Details  Product Details

Product DetailsProduct Details

Product Details

The TOP 100 Economics Blogs of 2022

INTELLIGENT ECONOMIST

Last Updated: February 3rd, 2022

By Prateek Agarwal

Welcome, and thank you for joining us for the 5th annual Top Economics Blogs list! We are happy, once again, to introduce you to a freshly updated list of economics blogs for 2022. As always, our winners list provides blogs for many different audiences, ranging from the budding economic enthusiast to the seasoned academic. The list also covers a variety of economics topics, whether it be traditional economic theory or the application of economics to current events and issues. In this meticulously curated list, we’ve condensed the most unique elements of each blog into short descriptions, so that you can see which ones catch your eye.

CITE: https://www.r2library.com/Resource/Title/0826102549

For 2022, a few newcomers have emerged, while many mainstays from previous years are present as well. Like previous years, we’ve done our best to capture the blogs which stand out for their quality rather than their popularity. As such, the list is an eclectic group that represents a wide range of tastes and perspectives.

***

What is an economist? Definition and examples - Market Business News

Regardless of your school of thought or political affiliation, you can find valuable new content in this list of engaging, high-quality economics blogs.

LINK: https://www.intelligenteconomist.com/economics-blogs/

Product Details

YOUR COMMENTS ARE APPRECIATED.

***

Thank You

***
About Healthcare Marketing Plan Revisions?

By MM+M

***
***

Cause of Healthcare Marketing Plan Revisions

A recent survey asked “Have you revised, relaunched or otherwise altered an existing healthcare marketing campaign for any reason?” The survey shows:

 •  Pandemic-related disruption: 70.0%
 •  New competitive entrant: 36.7%
 •  Access issues: 36.7%
 •  Under-performance: 36.7%
 •  New brand leadership: 33.3%
 •  New indication/label change: 30.0%
 •  Drug shortage: 13.3%
 •  Other external market shift: 6.7%

Source: MM+M, “Healthcare Marketers Trend Report 2022: The Reset,” March 8, 2022

***
COMMENTS APPRECIATED

Thank You

Subscribe to the Medical Executive-Post

***
***

***
How to Buy Securities On Margin

Join Our Mailing List

How It Works and What Physicians’ Must Watch Out For

 Dr. David Edward Marcinko MBA CMP

“Buying on margin” is borrowing money from your stock-broker to buy a stock and using your investment as collateral. Physician-investors generally use margin to increase their purchasing power so that they can own more stock without fully paying for it. But, margin exposes all investors to the potential for higher losses.

This ME-P discusses the basics of buying on margin, some of the pitfalls inherent in margin buying, whether this financial tool is for you and how you can best use it.

How Does Margin Work?

Let’s say you buy a stock for $50 and the price of the stock rises to $75. If you bought the stock in a cash account and paid for it in full, you’ll earn a 50 percent return on your investment. But, if you bought the stock on margin – paying $25 in cash and borrowing $25 from your broker – you’ll earn a 100 percent return on the money you invested. Of course, you’ll still owe your brokerage $25 plus interest.

The downside to using margin is that if the stock price decreases, substantial losses can mount quickly. For example, let’s say the stock you bought for $50 falls to $25. If you fully paid for the stock, you’ll lose 50% of your money. But if you bought on margin, you’ll lose 100%, and you still must come up with the interest you owe on the loan.

Caution: In volatile markets, investors who put up an initial margin payment for a stock may, from time to time, be required to provide additional cash if the price of the stock falls. Investors have been shocked to learn that a broker has the right to sell the securities that were bought on margin – without any notification, and at a potentially substantial loss to the investor.

Caution: If your broker sells your stock after the price has plummeted, then you’ve lost out on the chance to recoup your losses if the market bounces back.

The Risks

Margin accounts can be very risky and they are not for everyone. Before opening a margin account, be aware that:

  • You can lose more money than you have invested;
  • You may have to deposit additional cash or securities in your account on short notice to cover market losses;
  • You may be forced to sell some or all of your securities when falling stock prices reduce the value of your securities; and
  • Your brokerage firm may sell some or all of your securities without consulting you to pay off the loan it made to you.

You can protect yourself by knowing how a margin account works and what happens if the price of the stock purchased on margin declines.

Tip: Your broker charges you interest for borrowing money; take into account how that will affect the total return on your investments.

Tip: Ask your broker whether it makes sense for you to trade on margin in light of your financial resources, investment objectives, and tolerance for risk.

Read Your Margin Agreement

To open a margin account, you must sign a margin agreement. The agreement may either be part of your account agreement or separate. The margin agreement states that you must abide by the rules of the Federal Reserve Board, the New York Stock Exchange, the National Association of Securities Dealers, Inc., and the firm where you have set up your margin account.

Caution: Carefully review the agreement before signing.

As with most loans, the margin agreement explains the terms and conditions of the margin account. The agreement describes how the interest on the loan is calculated, how you are responsible for repaying the loan, and how the securities you purchase serve as collateral for the loan. Carefully review the agreement to determine what notice, if any, your firm must give you before selling your securities to collect the money you have borrowed.

***

margin risk

***
Know the Margin Rules

The Federal Reserve Board and many self-regulatory organizations (SROs), such as the NYSE and NASD, have rules that govern margin trading. Brokerage firms can establish their own requirements as long as they are at least as restrictive as the Federal Reserve Board and SRO rules.

Here are some of the key rules you should know:

Before You Trade – Minimum Margin. Before trading on margin, the NYSE and NASD, for example, require you to deposit with your brokerage firm a minimum of $2,000 or 100 percent of the purchase price, whichever is less. This is known as the “minimum margin.” Some firms may require you to deposit more than $2,000.

Amount You Can Borrow – Initial Margin. According to Regulation T of the Federal Reserve Board, you may borrow up to 50 percent of the purchase price of securities that can be purchased on margin. This is known as the “initial margin.” Some firms require you to deposit more than 50 percent of the purchase price.

Tip: Not all securities can be purchased on margin.

Amount You Need After You Trade – Maintenance Margin. After you buy stock on margin, the NYSE and NASD require you to keep a minimum amount of equity in your margin account. The equity in your account is the value of your securities less how much you owe to your brokerage firm. The rules require you to have at least 25 percent of the total market value of the securities in your margin account at all times. The 25 percent is called the “maintenance requirement.” In fact, many brokerage firms have higher maintenance requirements, typically between 30 to 40 percent and sometimes higher, depending on the type of stock purchased.

Example: You purchase $16,000 worth of securities by borrowing $8,000 from your firm and paying $8,000 in cash or securities. If the market value of the securities drops to $12,000, the equity in your account will fall to $4,000 ($12,000 – $8,000 = $4,000). If your firm has a 25 percent maintenance requirement, you must have $3,000 in equity in your account (25 percent of $12,000 = $3,000). In this case, you do have enough equity because the $4,000 in equity in your account is greater than the $3,000 maintenance requirement.

But, if your firm has a maintenance requirement of 40%, you would not have enough equity. The firm would require you to have $4,800 in equity (40% of $12,000 = $4,800). Your $4,000 in equity is less than the firm’s $4,800 maintenance requirement. As a result, the firm may issue you a “margin call,” since the equity in your account has fallen $800 below the firm’s maintenance requirement.

Margin Calls

If your account falls below the firm’s maintenance requirement, your broker generally will make a margin call to ask you to deposit more cash or securities into your account. If you are unable to meet the margin call, your firm will sell your securities to increase the equity in your account up to or above the firm’s maintenance requirement.

Tip: Your broker may not be required to make a margin call or otherwise tell you that your account has fallen below the firm’s maintenance requirement. Your broker may be able to sell your securities at any time without consulting you first. Under most margin agreements, even if your firm offers to give you time to increase the equity in your account, it can sell your securities without waiting for you to meet the margin call.

  • Margin accounts involve a great deal more risk than cash accounts, where you fully pay for the securities you purchase. You may lose more than your initial investment when buying on margin. If you cannot afford to do so, then margin buying is not for you.
  • Read the margin agreement, and ask your broker questions about how a margin account works and whether it’s appropriate for you to trade on margin. Your broker should explain the terms and conditions of the margin agreement.
  • Know how much you will be charged on money you borrow from your broker, and know how these costs affect your overall return.
  • Remember that your brokerage firm can sell your securities without notice to you when you don’t have sufficient equity in your margin account.

More:

Channel Surfing the ME-P

Have you visited our other topic channels? Established to facilitate idea exchange and link our community together, the value of these topics is dependent upon your input. Please take a minute to visit. And, to prevent that annoying spam, we ask that you register. It is fast, free and secure.

???????????????????????????????????????

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

***Invite Dr. Marcinko

(((* 8

[Medical] Entrepreneurs Drawn to Starting Incubators?

INFORMATION FROM THE TRENCHES

Join Our Mailing List

More Ideas to Help [Medical] Entrepreneurs

idea

David Cummings on Startups

Last week I was reading an article about a successful entrepreneur that had started an incubator to work on multiple startups simultaneously. Incubators, now called studios or labs, were popularized during the dot com boom, and most failed to work, leaving a negative connotation for many people. Now, the cost to start is 10x cheaper and there are millions of people with mobile broadband connections, making for a different dynamic compared to 15 years ago. While it is still expensive to scale, getting started is easy.

Here are a few ideas why entrepreneurs are drawn to incubators:

  • Timing a market is terribly difficult, so having multiple startups running simultaneously increases the chance of finding a fit
  • For many (most?) entrepreneurs, the starting part is more fun than the scaling part
  • Small, dedicated teams without a legacy customer base can innovate fast, making it more fun to see rapid progress
  • When…

View original post 81 more words