

***
***
Bitcoin slumped below $72,000, a level last seen 15 months ago, as a broad risk-off sentiment engulfed global markets.
COMMENTS APPRECIATED
***
Share this:

Filed under: iMBA, Inc. | Leave a comment »
ME-P SYNDICATIONS:
WSJ.com,
CNN.com,
Forbes.com,
WashingtonPost.com,
BusinessWeek.com,
USNews.com, Reuters.com,
TimeWarnerCable.com,
e-How.com,
News Alloy.com,
and Congress.org


BOARD CERTIFICATION EXAM STUDY GUIDES
Lower Extremity Trauma
[Click on Image to Enlarge]
The “Medical Executive-Post” is about connecting doctors, health care executives and modern consulting advisors. It’s about free-enterprise, business, practice, policy, personal financial planning and wealth building capitalism. We have an attitude that’s independent, outspoken, intelligent and so Next-Gen; often edgy, usually controversial. And, our consultants “got fly”, just like U. Read it! Write it! Post it! “Medical Executive-Post”. Call or email us for your FREE advertising and sales consultation TODAY [678.779.8597] E-mail: MarcinkoAdvisors1738@outlook.com


 ePodiatryConsentForms.com
 “Providing Management, Financial and Business Solutions for Modernity”
 Support our online development, and advance our onground research initiatives in free market economics, as we seek to showcase the brightest Next-Gen minds.
THE ME-P DISCLAIMER: Posts, comments and opinions do not necessarily represent iMBA, Inc., but become our property after submission. Copyright © 2006 to-date. iMBA, Inc allows colleges, universities, medical and financial professionals and related clinics, hospitals and non-profit healthcare organizations to distribute our proprietary essays, photos, videos, audios and other documents; etc. However, please review copyright and usage information for each individual asset before submission to us, and/or placement on your publication or web site. Attestation references, citations and/or back-links are required. All other assets are property of the individual copyright holder.


***
***
Bitcoin slumped below $72,000, a level last seen 15 months ago, as a broad risk-off sentiment engulfed global markets.
COMMENTS APPRECIATED
***
Filed under: iMBA, Inc. | Leave a comment »
Dr. David Edward Marcinko; MBA MEd CMP
SPONSOR: http://www.HealthDictionarySeries.org
***
***
Launching a successful private accounting practice requires far more than technical expertise. It demands strategic planning, a clear sense of purpose, and the discipline to build systems that support long‑term growth. Many accountants enter private practice because they want independence, deeper client relationships, or the chance to shape their own professional path. Turning that ambition into a thriving business means approaching the launch with intention and a willingness to think like both an accountant and an entrepreneur.
A strong beginning starts with defining the scope and identity of the practice. Accounting is a broad field, and trying to serve every possible client dilutes your message and your efficiency. Choosing a niche—such as small business bookkeeping, tax planning for individuals, accounting for nonprofits, or advisory services for startups—helps you stand out in a crowded market. A niche does not limit opportunity; it clarifies it. When you tailor your services to a specific audience, you can speak directly to their needs, refine your expertise, and build a reputation as the go‑to professional for that group.
Once your niche is clear, the next step is establishing credibility. Clients trust accountants with sensitive financial information, so they need to feel confident in your professionalism and integrity. Credentials, certifications, and licenses matter, but credibility also comes from how you present yourself. A polished brand, a well‑designed website, and clear communication signal reliability. Transparency about your services, pricing, and processes builds trust from the first interaction. In a field where accuracy and ethics are essential, every detail of your presentation contributes to your reputation.
A successful accounting practice also depends on choosing the right business model. You must decide whether you will charge hourly, offer fixed‑fee packages, or use value‑based pricing. Each model has strengths, and the best choice depends on your niche and your philosophy. Fixed‑fee packages often appeal to small businesses that want predictability, while value‑based pricing can work well for advisory services. Whatever model you choose, clarity is essential. Clients appreciate knowing exactly what they are paying for and how your services will benefit them.
Marketing is another critical pillar of a thriving practice. Many accountants underestimate the importance of visibility, assuming that technical skill alone will attract clients. In reality, people need to know you exist before they can hire you. A strong online presence—complete with a professional website, clear service descriptions, and helpful content—helps potential clients understand your value. Writing articles, hosting webinars, or sharing practical tips on social platforms positions you as a knowledgeable and approachable expert. Offline marketing matters too. Networking with attorneys, financial planners, real estate agents, and local business owners can lead to steady referrals. Community involvement, such as speaking at local events or joining business associations, builds trust and name recognition.
Client experience is where a private accounting practice truly distinguishes itself. Accounting can feel intimidating or stressful for many people, so clients value an advisor who communicates clearly, listens carefully, and makes the process feel manageable. A smooth onboarding process sets the tone for the relationship. This includes gathering information efficiently, explaining your workflow, and outlining expectations. Regular communication—whether through monthly check‑ins, quarterly reviews, or timely reminders—helps clients feel supported and informed. When clients trust you and feel cared for, they stay loyal and refer others.
***
***
Operational efficiency is another essential ingredient. As your practice grows, systems and processes become the backbone of your business. This includes workflow management, document storage, compliance procedures, and client communication tools. Investing in the right technology—such as accounting software, secure portals, and customer relationship management systems—saves time and reduces errors. Standardizing your processes ensures consistency and frees you to focus on higher‑value work. Many accountants benefit from outsourcing tasks like marketing, administrative work, or IT support so they can concentrate on serving clients and growing the business.
Adaptability is equally important. The accounting landscape changes constantly, with new regulations, evolving technology, and shifting client expectations. A successful practice stays ahead by embracing continuous learning. This might mean adopting new software, expanding your service offerings, or refining your pricing structure. Flexibility ensures that your practice remains relevant and competitive. Clients appreciate an accountant who stays informed and proactive, especially when regulations or economic conditions shift.
***
***
Finally, launching a successful private accounting practice requires patience and resilience. Building a client base takes time, and early challenges are inevitable. Some months may feel slow, and some marketing efforts may not produce immediate results. Persistence, combined with a commitment to delivering exceptional value, gradually builds momentum. Over time, satisfied clients become advocates, referrals increase, and your practice grows organically.
In essence, launching a successful private accounting practice is a blend of strategic planning, professional integrity, and genuine client care. When you combine technical expertise with thoughtful positioning, strong systems, and a commitment to continuous improvement, you create a practice that not only thrives financially but also makes a meaningful difference in the lives of the clients you serve.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Staff Reporters
SPONSOR: http://www.MarcinkoAssociates.com
***
***
A concept of tax fairness that states that people with different amounts of wealth or different amounts of income should pay tax at different rates. Wealth includes assets such as houses, cars, stocks, bonds, and savings accounts. Income includes wages, interest and dividends, and other payments.
Gross income reduced by certain amounts, such as a deductible IRA contribution or student loan interest
Money that taxpayers must pay to the government when the total tax is greater than their total tax payments
To call for a review of an IRS decision or proposed adjustment.
Authorized IRS e-file Provider
A business authorized by the IRS to participate in the IRS e-file Program. The business may be a sole proprietorship, a partnership, a corporation, or an organization. Authorized IRS e-file Providers include Electronic Return Originators (EROs), Transmitters, Intermediate Service Providers, and Software Developers. These categories are not mutually exclusive. For example, an ERO can at the same time, be a Transmitter, a Software Developer, or an Intermediate Service Provider, depending on the function being performed.
A concept of tax fairness that states that people should pay taxes in proportion to the benefits they receive from government goods and services.
Compensation received by an employee for services performed. A bonus is given in addition to an employee’s usual compensation.
A continuous and regular activity that has income or profit as its primary purpose.
Assuming all other dependency tests are met, the citizen or resident test allows taxpayers to claim a dependency exemption for persons who are U.S. citizens for some part of the year or who live in the United States, Canada, or Mexico for some part of the year.
Compensation received by an employee for services performed. Commissions are paid based on a percentage of sales made or a fixed amount per sale.
An automatic tax collected from employers and employees to finance specific programs.
The result of the government taking in less money than it spends.
Amount that taxpayers can claim for a “qualifying child” or “qualifying relative”. Each exemption reduces the income subject to tax. The exemption amount is a set amount that changes from year to year. One exemption is allowed for each qualifying child or qualifying relative claimed as a dependent.
A qualifying child or qualifying relative, other than the taxpayer or spouse, who entitles the taxpayer to claim a dependency exemption.
This allows tax refunds to be deposited directly to the taxpayer’s bank account. Direct Deposit is a fast, simple, safe, secure way to get a tax refund. The taxpayer must have an established checking or savings account to qualify for Direct Deposit. A bank or financial institution will supply the required account and routing transit numbers to the taxpayer for Direct Deposit.
A tax that cannot be shifted to others, such as the federal income tax.
Includes wages, salaries, tips, includible in gross income, and net earnings from self-employment earnings.
A tax credit for certain people who work, meet certain requirements, and have earned income under a specified limit.
The transmission of tax information directly to the IRS using telephones or computers. Electronic filing options include (1) Online self-prepared using a personal computer and tax preparation software, or (2) using a tax professional. Electronic filing may take place at the taxpayer’s home, a volunteer site, the library, a financial institution, the workplace, malls and stores, or a tax professional’s place of business.
Electronic preparation means that tax preparation software and computers are used to complete tax returns. Electronic tax preparation helps to reduce errors.
Electronic Return Originator (ERO)
The Authorized IRS e-file Provider that originates the electronic submission of an income tax return to the IRS. EROs may originate the electronic submission of income tax returns they either prepared or collected from taxpayers. Some EROs charge a fee for submitting returns electronically.
Works for an employer. Employers can control when, where, and how the employee performs the work.
A tax on the sale or use of specific products or transactions.
Free from withholding of federal income tax. A person must meet certain income, tax liability, and dependency criteria. This does not exempt a person from other kinds of tax withholding, such as the Social Security tax.
Amount that taxpayers can claim for themselves, their spouses, and eligible dependents. There are two types of exemptions-personal and dependency. Each exemption reduces the income subject to tax. While each is worth the same amount, different rules apply to each.
A program sponsored by the IRS in partnership with participating states that allows taxpayers to file federal and state income tax returns electronically at the same time.
The federal government levies a tax on personal income. The federal income tax provides for national programs such as defense, foreign affairs, law enforcement, and interest on the national debt.
Federal Insurance Contributions Act (FICA) Tax
Provides benefits for retired workers and their dependents as well as for disabled workers and their dependents. Also known as the Social Security tax.
To mail or otherwise transmit to an IRS service center the taxpayer’s information, in specified format, about income and tax liability. This information-the return-can be filed on paper, electronically (e-file).
Determines the rate at which income is taxed. The five filing statuses are: single, married filing a joint return, married filing a separate return, head of household, and qualifying widow(er) with dependent child.
Spending and income records and items to keep for tax purposes, including paycheck stubs, statements of interest or dividends earned, and records of gifts, tips, and bonuses. Spending records include canceled checks, cash register receipts, credit card statements, and rent receipts.
This is another term for a proportional tax.
formal tax legislation process
This is another term for a proportional tax.
Form W-4, Employee’s Withholding Allowance Certificate
Completed by the employee and used by the employer to determine the amount of income tax to withhold.
A foster child is any child placed with a taxpayer by an authorized placement agency or by court order. Eligible foster children may be claimed by taxpayers for tax benefits.
An excise tax paid by consumers when they purchase gasoline. The tax covers the manufacture, sale, and use of gasoline.
Money, goods, services, and property a person receives that must be reported on a tax return. Includes unemployment compensation and certain scholarships. It does not include welfare benefits and nontaxable Social Security benefits.
Head of Household filing status
You must meet the following requirements: 1. You are unmarried or considered unmarried on the last day of the year. 2. You paid more than half the cost of keeping up a home for the year. 3. A qualifying person lived with you in the home for more than half the year (except temporary absences, such as school). However, a dependent parent does not have to live with the taxpayer.
The concept that people in the same income group should be taxed at the same rate. “Equals should be taxed equally.”
Taxes on income, both earned (salaries, wages, tips, commissions) and unearned (interest, dividends). Income taxes can be levied on both individuals (personal income taxes) and businesses (business and corporate income taxes).
Performs services for others. The recipients of the services do not control the means or methods the independent contractor uses to accomplish the work. The recipients do control the results of the work; they decide whether the work is acceptable. Independent contractors are self-employed.
A tax that can be shifted to others, such as business property taxes.
A new or developing domestic industry whose costs of production are higher than those of established firms in the same industry in other countries.
***
***
The simultaneous increase of consumer prices and decrease in the value of money and credit.
informal tax legislation process
Individuals and interest groups expressing and promoting their opinions about tax legislation.
The charge for the use of borrowed money.
The income a person receives from certain bank accounts or from lending money to someone else.
Assists in processing tax return information between the ERO (or the taxpayer, in the case of online filing) and the Transmitter.
Internal Revenue Service (IRS)
The federal agency that collects income taxes in the United States.
Includes taxable and tax-exempt interest, dividends, capital gains net income, certain rent and royalty income, and net passive activity income.
Refers to the preparation and transmission of tax return information to the IRS using telephone lines or a computer with a modem or Internet access.
A person who represents the concerns or special interests of a particular group or organization in meetings with lawmakers. Lobbyists work to persuade lawmakers to change laws in the group’s favor.
long-distance telephone tax refund
Taxpayers are eligible to file for refunds of all excise tax they have paid on long-distance service billed to them after Feb. 28, 2003.
A tax paid on expensive goods and services considered by the government to be nonessential.
An economic system based on private enterprise that rests upon three basic freedoms: freedom of the consumer to choose among competing products and services, freedom of the producer to start or expand a business, and freedom of the worker to choose a job and employer.
Married Filing Joint filing status
You are married and both you and your spouse agree to file a joint return. (On a joint return, you report your combined income and deduct your combined allowable expenses.)
Married Filing Separate filing status
You must be married. This method may benefit you if you want to be responsible only for your own tax or if this method results in less tax than a joint return. If you and your spouse do not agree to file a joint return, you may have to use this filing status.
A broad tax that affects a majority of taxpayers.
Used to provide medical benefits for certain individuals when they reach age 65. Workers, retired workers, and the spouses of workers and retired workers are eligible to receive Medicare benefits upon reaching age 65.
When the amount of a credit is greater than the tax owed, taxpayers can only reduce their tax to zero; they cannot receive a “refund” for any excess nonrefundable credit.
A state’s refusal to recognize or obey a federal law.
Include Social Security and Medicare taxes.
Can be claimed for the taxpayer and spouse. Each personal exemption reduces the income subject to tax by the exemption amount.
Personal Identification Number (PIN)
Allow taxpayers to “sign” their tax returns electronically. The PIN, a five-digit self-selected number, ensures that electronically submitted tax returns are authentic. Most taxpayers can qualify to use a PIN.
A tax that takes a larger percentage of income from high-income groups than from low-income groups.
Taxes on property, especially real estate, but also can be on boats, automobiles (often paid along with license fees), recreational vehicles, and business inventories.
A tax that takes the same percentage of income from all income groups.
A tax levied on imported goods with the purpose of reducing domestic consumption of foreign-produced goods.
Benefits that cannot be withheld from those who don’t pay for them, and benefits that may be “consumed” by one person without reducing the amount of the product available for others. Examples include national defense, streetlights, and roads and highways. Public services include welfare programs, law enforcement, and monitoring and regulating trade and the economy.
To be a qualifying child, the dependent must meet eight tests: (1) relationship, (2) age, (3) residence, (4) support, (5) citizenship or residency, (6) joint return, (7) qualifying child of more than one person, and (8) dependent taxpayer.
There are tests that must be met to be a qualifying relative, they are: (1) not a qualifying child, (2) member of household or relationship, (3) citizenship or residency, (4) gross income, (5) support, (6) joint return, and (7) dependent taxpayer.
Qualifying Widow(er) filing status
If your spouse died in 2010, you can use married filing jointly as your filing status for 2010 if you otherwise qualify to use that status. The year of death is the last year for which you can file jointly with your deceased spouse. You may be eligible to use qualifying widow(er) with dependent child as your filing status for two years following the year of death of your spouse. For example, if your spouse died in 2010, and you have not remarried, you may be able to use this filing status for 2011 and 2012. This filing status entitles you to use joint return tax rates and the highest standard deduction amount (if you do not itemize deductions). This status does not entitle you to file a joint return.
Money owed to taxpayers when their total tax payments are greater than the total tax. Refunds are received from the government.
When the amount of a credit is greater than the tax owed, taxpayers can receive a “refund” for some of the unused credit.
A tax that takes a larger percentage of income from low-income groups than from high-income groups.
Factors needed to produce goods and services (natural, human, and capital goods).
The income the nation collects from taxes.
A tax on imported goods levied primarily to generate revenue for the federal government.
Compensation received by an employee for services performed. A salary is a fixed sum paid for a specific period of time worked, such as weekly or monthly.
A tax on retail products based on a set percentage of retail cost.
Self-employment income minus self-employment expenses, when self-employment income is less than self-employment expenses.
Self-employment income minus self-employment expenses, when self-employment income is greater than self-employment expenses.
Similar to Social Security and Medicare taxes. The self-employment tax rate is 15.3 percent of self-employment profit. The self-employment tax is calculated on Schedule SE—Self-Employment Tax. The self-employment tax is reported on Form 1040, U.S. Individual Income Tax Return.
If on the last day of the year, you are unmarried or legally separated from your spouse under a divorce or separate maintenance decree and you do not qualify for another filing status.
A tax on goods such as tobacco and alcohol.
Provides benefits for retired workers and their dependents as well as for the disabled and their dependents. Also known as the Federal Insurance Contributions Act (FICA) tax.
Develops software for the purposes of (1) formatting electronic tax return information according to IRS specifications, and/or (2) transmitting electronic tax return information directly to the IRS.
Reduces the income subject to tax and varies depending on filing status, age, blindness, and dependency.
For dependency test purposes, support includes food, clothing, shelter, education, medical and dental care, recreation, and transportation. It also includes welfare, food stamps, and housing provided by the state. Support includes all income, taxable and nontaxable.
A tax on products imported from foreign countries.
Interest income that is subject to income tax. All interest income is taxable unless specifically excluded.
An action taken to lessen tax liability and maximize after-tax income.
The official body of tax laws and regulations.
A dollar-for-dollar reduction in the tax. Can be deducted directly from taxes owed.
A reduction in the amount of taxes taken by the government.
An amount (often a personal or business expense) that reduces income subject to tax.
Required payments of money to governments that are used to provide public goods and services for the benefit of the community as a whole.
A failure to pay or a deliberate underpayment of taxes.
Interest income that is not subject to income tax. Tax-exempt interest income is earned from bonds issued by states, cities, or counties and the District of Columbia.
A part of a person’s income on which no tax is imposed.
tax liability (or total tax bill)
The amount of tax that must be paid. Taxpayers meet (or pay) their federal income tax liability through withholding, estimated tax payments, and payments made with the tax forms they file with the government.
Computer software designed to complete tax returns. The tax preparation software works with the IRS electronic filing system.
The process that occurs when a tax that has been levied on one person or group is in fact paid by others.
Taxpayers are eligible to file for refunds of all excise tax they have paid on long-distance service billed to them after Feb. 28, 2003.
Money and goods received for services performed by food servers, baggage handlers, hairdressers, and others. Tips go beyond the stated amount of the bill and are given voluntarily.
Taxes on economic transactions, such as the sale of goods and services. These can be based on a set of percentages of the sales value (ad valorem-sales taxes), or they can be a set amount on physical quantities (“per unit”-gasoline taxes).
To send a tax return to the IRS electronically. Tax returns prepared on paper can be sent through the mail.
Sends the electronic return data directly to the IRS.
Money-making activities that people don’t report to the government, including both illegal and legal activities.
An excise tax, often in the form of a license or supplemental charge, levied to fund a public service.
A tax that is paid directly by the consumer of a good, product, or service.
The concept that people in different income groups should pay different rates of taxes or different percentages of their incomes as taxes. “Unequals should be taxed unequally.”
A system of compliance that relies on individual citizens to report their income freely and voluntarily, calculate their tax liability correctly, and file a tax return on time.
Volunteer Income Tax Assistance (VITA)
This provides free income tax return preparation for certain taxpayers. The VITA program assists taxpayers who have limited or moderate incomes, have limited English skills, or are elderly or disabled. Many VITA sites offer electronic preparation and transmission of income tax returns.
Compensation received by employees for services performed. Usually, wages are computed by multiplying an hourly pay rate by the number of hours worked.
withholding (“pay-as-you-earn” taxation)
Money, for example, that employers withhold from employees paychecks. This money is deposited for the government. (It will be credited against the employees’ tax liability when they file their returns.) Employers withhold money for federal income taxes, Social Security taxes and state and local income taxes in some states and localities.
***
COMMENTS APPRECIATED
Refer and Subscribe
***
***
Filed under: Accounting, Financial Planning, Funding Basics, Glossary Terms, Investing, Marcinko Associates, Taxation | Tagged: accountant, accountants, CMA, CPA, EA, finance, Marcinko, personal-finance, tax, tax planning, tax terms, Taxation, taxes | Leave a comment »
Sponsor: http://www.MarcinkoAssociates.com
***
***
Telephonic or electronic advice for medical professionals that is:
The iMBA Discussion Forum™ is a physician-to-advisor telephone or e-mail portal that connects independent financial professionals and medical management consultants, with doctors or healthcare executives desiring affordable and unbiased financial or business advice on an as-needed, pay-per-use basis.
Medical professionals and healthcare executives can now receive direct access to pre-screened iMBA professionals in the areas of Practice Enhancement, Investing, Financial Planning, Asset Allocation, Portfolio Management Taxes, Insurance, Mortgage and Lending, Practice Management, Information Technology, Human Resources and Employee Benefits. To assist our doctor / healthcare executive members, we can be contracted with per-minute or per-project fees, and contacted by client phone, email or secure instant messaging.
The iMBA Discussion Forum™ is designed to fill a growing need for medically focused financial or managerial advice that traditional consultants have not been able to serve. Most financial “consultants” either charge high sales commissions, or levy a percentage of fees for managing client assets. And, management consultants tend to extend their scope of engagement to tangential areas not originally needed, or wanted.
Typically, financial advisors also require clients to meet minimum asset level thresholds ($500,000 to $750,000, or more), or pay thousands of dollars in consulting fees to receive their services. These fee structures have created inherent conflicts of interest and significant barriers for an increasing number of time-compressed and economically constrained physicians or healthcare executives.
TOPICS: https://davidedwardmarcinko.com/coach/
Now, with the iMBA Discussion Forum™, all physicians and executive clients can receive unbiased financial advice, and objective business opinions, on their own terms, anytime-anywhere.
The iMBA Discussion Forum™ eliminates conflicts of interest by providing advice on a per-use basis, so you pay only for what you want and need. iMBA does not sell financial or business products. The result is a unique “no pressure”, and “no conflicts-of-interest experience.”
Get started with your consultation, now! Receive only the advice you need and pay for, from a medically focused and qualified doctor-advisor looking after your best interests.
Contact Us Now! How the iMBA Discussion Forum Works:
Refer and Subscribe
The iMBA Discussion Forum© Fee Schedule
CONTACT: Ann Miller; RN, MHA, CPHQ, CMP™
Email: MarcinkoAdvisors1738@outlook.com
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit a RFP for speaking engagements: MarcinkoAdvisors@outlook.com
***
***
Filed under: Experts Invited, Financial Planning, Marcinko Associates, Touring with Marcinko | Tagged: books, fiduciary opinion, informed opinion, Marcinko, movies, news, RFP, second opinion, speaking, sports, Technology | Leave a comment »
By Staff Reporters
***
***
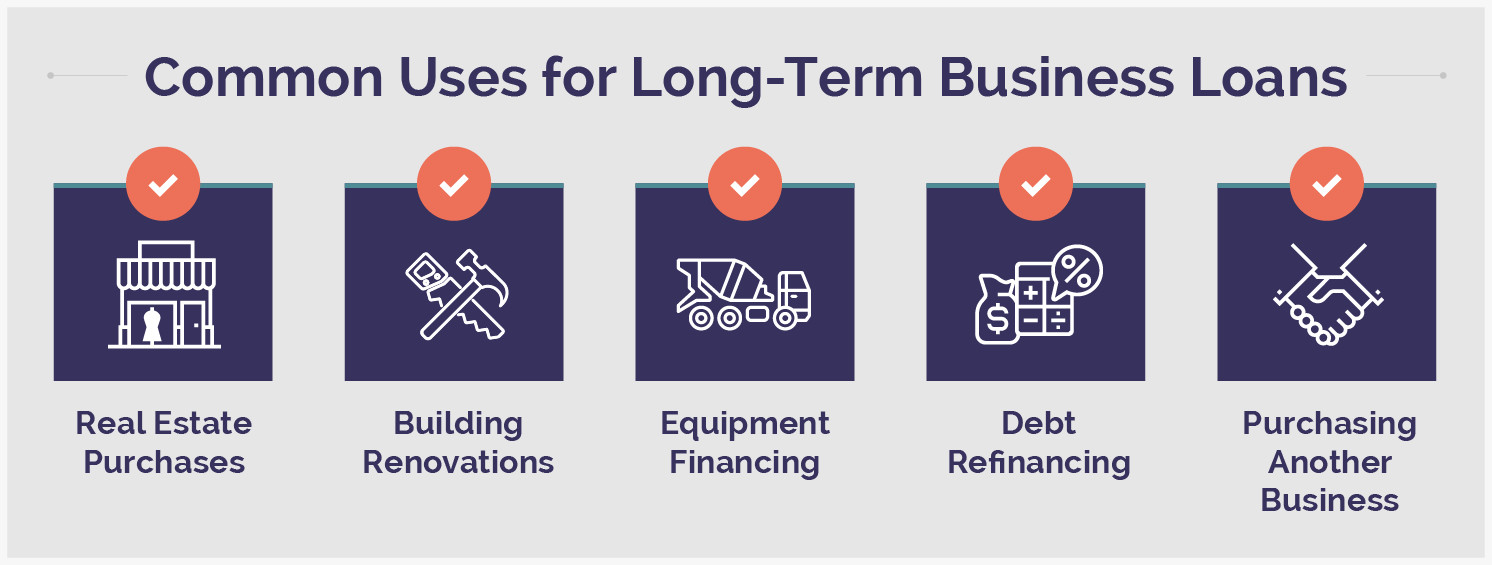
A secured debt is pledged by a specific property. This is a collateralized loan.
Generally, the purchased item is pledged with the proceeds of the loan. This would include long-term liabilities (more than 12 months) such as a mortgage, home equity loan, or a car loan. Although the creditor has the ability to take possession of your property in order to recover a bad debt, it is done very rarely. A creditor is more interested in recovering money. Sometimes, when borrowing money, there may be a requirement to pledge assets that are owned prior to the loan.
For example, a personal loan from a finance company requires that you pledge all personal property such as your car, furniture, and equipment. The same property may become subject to a judicial lien if you are sued and a judgment is made against you. In this case, you would not be able to sell or pledge these assets until the judgment is satisfied. A common example of a lien would be from unpaid federal, state or local taxes. Doctors can be found personally liable for unpaid payroll taxes of employees in their professional corporations.
***
The primary distinction between long-term and short-term liabilities lies in their repayment timing. Long-term liabilities are obligations due beyond one year, while short-term, or current, liabilities are financial obligations settled within one year of the balance sheet date or the company’s operating cycle, whichever is longer. This timing difference impacts how these obligations are viewed in financial analysis.
Examples of short-term liabilities include accounts payable, which are amounts owed to suppliers for goods or services purchased on credit, typically due within 30 to 60 days. Other common short-term obligations are short-term notes payable, accrued expenses like salaries or utilities, and the portion of long-term debt that becomes due within the next 12 months. These obligations are usually paid using current assets.
This distinction is important for financial analysis, as it helps assess a company’s financial health. Short-term liabilities are relevant for evaluating a company’s liquidity, its ability to meet immediate financial obligations. Conversely, long-term liabilities provide insights into a company’s solvency, indicating its ability to meet financial obligations over an extended period and its overall financial stability.
***
Finally, be aware that some assets and liabilities defy short or long-term definition. When this happens, simply be consistent in your comparison of financial statements, over time.
COMMENTS APPRECIATED
Refer, Like and Subscribe
***
***
Filed under: "Ask-an-Advisor", finance, Financial Planning, Investing, Portfolio Management | Tagged: business, debt, finance, loans, long term debt, long term loans, mortgages, personal-finance, real-estate, short term debt | Leave a comment »
By Dr. David Edward Marcinko MBA MEd CMP™
***
***
SPONSOR: http://www.CertifiedMedicalPlanner.org
Physicians are entrepreneurial by nature and take great pride in the creation of their businesses. Market pressures are motivating physicians to be proactive and to make informed decisions concerning the future of their businesses. The decision to sell, buy or merge while often financially driven and is inherently an emotional one. Other economic reasons for a practice valuation include changes in ownership, determining insurance coverage for a practice buy-sell agreement or upon a physician owners death, establishing stock options, or bringing in a new partner.
Practice appraisals are also used for legal reasons such as divorce, bankruptcy, breach of contract and minority shareholder complaints. In 2002, the Financial Accounting Standards Board (FASB) issued rules that required certain intangible assets to be valued, such as goodwill. This may be important for practices seeking start-up, service segmentation extensions, or operational funding.
Estate Planning is another reasons for a medical practice appraisal and the considerations that go along with it are discussed here.
***
***
Estate Planning
Medical practice valuation may be required for estate planning purposes. For a decedent physician with a gross estate of more than $1 million, his or her assets must be reported at fair market value on an estate tax return. If lifetime gifts of a medial practice business interest are made, it is generally wise to obtain an appraisal and attach it to the gift tax return.
Note that when a “closely-held” level of value (in contrast to “freely traded,” “marketable,” or “publicly traded” level) is sought, the valuation consultant may need to make adjustments to the results. There are inherent risks relative to the liquidity of investments in closely held, non-public companies (e.g., medical group practice) that are not relevant to the investment in companies whose shares are publicly traded (freely-traded). Investors in closely-held companies do not have the ability to dispose of an invested interest quickly if the situation is called for, and this relative lack of liquidity of ownership in a closely held company is accompanied by risks and costs associated with the selling of an interest said company (i.e., locating a buyer, negotiation of terms, advisor/broker fees, risk of exposure to the market, etc.).
Conversely, investors in the stock market are most often able to sell their interest in a publicly traded company within hours and receive cash proceeds in a few days. Accordingly, a discount may be applicable to the value of a closely held company due to the inherent illiquidity of the investment. Such a discount is commonly referred to as a “discount for lack of marketability.”
Discount for lack of marketability is typically discussed in three categories: (1) transactions involving restricted stock of publicly traded companies; (2) private transactions of companies prior to their initial public offering (IPO); and, (3) an analysis and comparison of the price to earnings (P/E) ratios of acquisitions of public and private companies respectively published in the “Mergerstat Review Study.”
With a non-controlling interest, in which the holder cannot solely authorize and cannot solely prevent corporate actions (in contrast to a controlling interest), a “discount for lack of control,” (DLOC), may be appropriate. In contrast, a control premium may be applicable to a controlling interest. A control premium is an increase to the pro rata share of the value of the business that reflects the impact on value inherent in the management and financial power that can be exercised by the holders of a control interest of the business (usually the majority holders).
Conversely, a discount for lack of control or minority discount is the reduction from the pro rata share of the value of the business as a whole that reflects the impact on value of the absence or diminution of control that can be exercised by the holders of a subject interest.
Several empirical studies have been done to attempt to quantify DLOC from its antithesis, control premiums. The studies include the Mergerstat Review, an annual series study of the premium paid by investors for controlling interest in publicly traded stock, and the Control Premium Study, a quarterly series study that compiles control premiums of publicly traded stocks by attempting to eliminate the possible distortion caused by speculation of a deal.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like and Subscribe
***
***
Filed under: "Ask-an-Advisor", Accounting, Career Development, Estate Planning, Ethics, Marcinko Associates | Tagged: Accounting, david marcinko, DLOC, Estate Planning, FASB, finance, Financial Planning, medical practice valuation, Mergerstat Review Study, personal-finance, tax-law | Leave a comment »
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MarcinkoAssociates.com
***
***
Starting a real estate agency is one of those ventures that blends entrepreneurship, strategy, and a deep understanding of people. It’s not just about selling property; it’s about building trust, navigating regulations, and creating a brand that stands out in a crowded market. A strong agency doesn’t appear overnight—it’s the result of careful planning, deliberate positioning, and consistent execution. A thoughtful approach from the beginning sets the foundation for long‑term success.
The first step in establishing a real estate agency is developing a clear business concept. Many new agents underestimate how important it is to define their niche early. Real estate is broad: residential sales, commercial leasing, luxury homes, property management, investment consulting, and more. Choosing a focus helps shape everything else—from marketing to staffing to pricing. A niche doesn’t limit growth; it creates clarity. When clients know exactly what you specialize in, they’re more likely to trust you with their biggest financial decisions.
Once the concept is defined, the next essential task is creating a business plan. This isn’t just a formality for banks or investors; it’s a roadmap. A strong business plan outlines the agency’s mission, target market, competitive landscape, financial projections, and operational structure. It forces the founder to think through challenges before they arise. For example, how will the agency generate leads? What will the commission structure look like? How much capital is needed to operate for the first year? These questions shape a realistic strategy rather than relying on guesswork.
Legal and regulatory requirements come next, and they’re non‑negotiable. Real estate is a heavily regulated industry, and every region has its own licensing rules. Typically, the founder must hold a broker’s license, which requires education, experience, and exams. The agency itself may also need a business license, insurance, and compliance with fair housing laws. Establishing proper legal structures—such as forming an LLC or corporation—protects the business and its clients. Skipping these steps can lead to fines or even the loss of the ability to operate, so careful attention to compliance is essential.
With the legal foundation in place, branding becomes the next major priority. A real estate agency’s brand is more than a logo; it’s the personality of the business. It communicates values, professionalism, and the type of clients the agency hopes to attract. A compelling brand includes a memorable name, a consistent visual identity, and a clear message. In a field where clients often choose agents based on trust and familiarity, branding plays a powerful role in shaping perception. A polished website, professional photography, and a strong social media presence help establish credibility from day one.
Marketing and lead generation are the lifeblood of any real estate agency. Even the most skilled broker cannot succeed without clients. Modern agencies rely on a mix of digital and traditional strategies. Online listings, search engine optimization, targeted ads, and social media campaigns help reach buyers and sellers where they already spend their time. At the same time, personal relationships remain central to real estate. Networking events, community involvement, and referrals continue to be some of the most effective ways to build a client base. Successful agencies blend technology with human connection, using each to reinforce the other.
***
***
Building a team is another critical step. Some agencies begin with a single broker, but growth requires additional agents, administrative staff, and sometimes specialists like marketing coordinators or transaction managers. Hiring the right people means looking for individuals who share the agency’s values and bring complementary skills. Training is equally important. Real estate laws, market trends, and technology evolve constantly, so ongoing education keeps the team sharp and competitive. A supportive culture encourages collaboration rather than cutthroat competition, which ultimately benefits clients.
Operational systems tie everything together. A real estate agency needs tools for managing listings, tracking leads, handling contracts, and communicating with clients. Customer relationship management software helps agents stay organized and responsive. Clear processes for onboarding clients, conducting showings, negotiating offers, and closing deals ensure consistency and professionalism. When systems are strong, the agency can scale without chaos.
Finally, establishing a real estate agency requires patience and resilience. The early months can be unpredictable, with fluctuating income and steep learning curves. But persistence pays off. Agencies that stay committed to their mission, adapt to market changes, and prioritize client relationships build reputations that last. Over time, satisfied clients become repeat customers and enthusiastic advocates, fueling sustainable growth.
Creating a real estate agency is both challenging and rewarding. It demands strategic thinking, legal awareness, marketing savvy, and strong interpersonal skills. But for those willing to invest the effort, it offers the chance to shape a business that reflects their vision and serves their community. The journey begins with a single step: a clear idea of what the agency stands for and the determination to bring it to life.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Health Capital Consultants, Inc
***
Between December 2025 and January 2026, the Centers for Medicare & Medicaid Services (CMS) Innovation Center unveiled six new alternative payment models spanning drug pricing, chronic disease management, lifestyle medicine, and accountable care. The models represent a significant expansion of both voluntary and mandatory payment reform initiatives.
This Health Capital Topics article discusses the key provisions, reimbursement mechanisms, and participation requirements of each model. (Read more…)
***
***
Filed under: iMBA, Inc. | Leave a comment »
Dr. David Edward Marcinko; MBA MEd CMP
SPONSOR: http://www.CertifiedMedicalPlanner.org
***
***
1. Define Your Niche Clearly
Trying to serve everyone weakens your message. Choose a specific audience—retirees, young professionals, physicians, small business owners—and tailor your services to their needs.
Be able to explain in one or two sentences what makes your practice different and why clients should trust you with their financial future.
Professional designations, clean branding, and transparent communication help establish trust. Clients want to feel confident that you know what you’re doing.
Decide whether you’ll operate as fee‑only, commission‑based, or hybrid. Align your model with your philosophy and the expectations of your target market.
A clean website, clear service descriptions, and easy ways to contact you make a big difference. Many clients will judge your credibility before they ever meet you.
Articles, short videos, workshops, or newsletters help potential clients understand your approach and build trust before they book a meeting.
Relationships with accountants, attorneys, real estate agents, and business owners can become steady referral sources. Show up, be helpful, and stay visible.
A structured, welcoming onboarding experience sets the tone for the entire relationship. Make it easy for clients to share information and understand what comes next.
Planning software, CRM tools, secure communication platforms, and workflow systems help you stay organized and deliver a polished client experience.
***
***
Financial planning is personal. Listen deeply, communicate clearly, and follow through consistently. Clients stay loyal when they feel understood and supported.
Document your processes—from prospecting to plan delivery to annual reviews. Systems create consistency, reduce errors, and free up time for higher‑value work.
Understand your startup costs, revenue projections, and break‑even point. A financial planner who doesn’t manage their own business finances well sends the wrong message.
You don’t need a large office or a big team on day one. Begin with essential tools and add staff or services as your client base grows.
Regulations, markets, and client expectations evolve. Keep learning, stay curious, and be willing to adjust your approach as the industry shifts.
A successful practice rarely grows overnight. Consistency, integrity, and genuine care for your clients build momentum that compounds over time.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Staff Reporters
***
***
The Role of Artificial Intelligence in Insurance and Risk Management
Artificial Intelligence (AI) is revolutionizing the insurance and risk management industries by enhancing efficiency, accuracy, and customer experience. As data becomes increasingly central to decision-making, AI offers powerful tools to analyze vast datasets, predict outcomes, and automate complex processes. Its integration is reshaping traditional models and enabling insurers to better assess risk, detect fraud, and personalize services.
One of the most transformative applications of AI in insurance is in underwriting. Traditionally, underwriting relied on manual evaluation of risk factors, which was time-consuming and prone to human error. AI algorithms can now process structured and unstructured data—from medical records to social media activity—to assess risk profiles with greater precision. Machine learning models continuously improve as they ingest more data, allowing insurers to refine their risk assessments and pricing strategies dynamically.
Claims processing is another area where AI is making a significant impact. Through natural language processing (NLP) and image recognition, AI can automate the evaluation of claims, reducing the time and cost associated with manual reviews. For example, AI can analyze photos of vehicle damage to estimate repair costs or flag inconsistencies in a claim that may indicate fraud. This not only speeds up the claims cycle but also enhances fraud detection, a critical concern in the industry.
Risk management benefits from AI’s predictive capabilities. By analyzing historical data and identifying patterns, AI can forecast potential risks and suggest mitigation strategies. In property insurance, AI can assess the likelihood of natural disasters by combining satellite imagery with climate data. In health insurance, predictive analytics can identify individuals at higher risk of chronic conditions, enabling early interventions and reducing long-term costs.
***
***
Customer experience is also being transformed by AI. Chatbots and virtual assistants provide 24/7 support, answering queries, guiding users through policy selection, and even initiating claims. These tools improve accessibility and responsiveness, fostering customer satisfaction and loyalty. Moreover, AI-driven personalization allows insurers to tailor products and communications to individual preferences and behaviors, enhancing engagement.
Despite its advantages, the adoption of AI in insurance and risk management raises ethical and regulatory challenges. Data privacy is a major concern, as AI systems require access to sensitive personal information. Ensuring transparency in AI decision-making is also critical, especially when algorithms influence coverage eligibility or claim outcomes. Regulators are increasingly scrutinizing AI applications to ensure fairness, accountability, and compliance with legal standards.
In conclusion, AI is a game-changer for insurance and risk management, offering tools to streamline operations, improve accuracy, and enhance customer service. As the technology evolves, insurers must balance innovation with ethical responsibility, ensuring that A.I. serves both business goals and societal interests. The future of insurance lies in intelligent systems that not only manage risk but also anticipate and prevent it—ushering in a new era of proactive, data-driven protection.
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: "Ask-an-Advisor", economics, finance, Insurance Matters, Investing, Risk Management | Tagged: AI, artificial intelligence, business, chatbots, insurance, marketing, NLP, Risk Management, Technology | Leave a comment »
***
***
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Leave a comment »
By Staff Reporters
***
***
In Healthcare
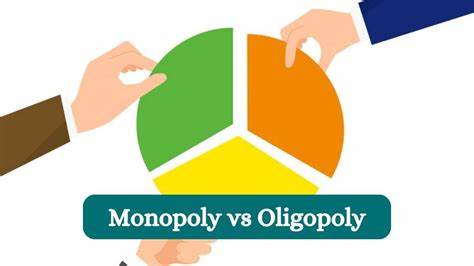
Monopsony and Oligopsony occur when discounts are extracted from healthcare providers because of supply and demand size inequalities, and may run afoul of anti-trust laws.
Many medical providers have monopoly or near-monopoly power, yet antitrust laws prevent some potentially beneficial integration.
***
Introduction
Monopsony and oligopsony are two terms that are often used interchangeably, but they are not the same thing.
Monopsony refers to a market structure where there is only one buyer of a certain product or service, while oligopsony refers to a market structure where there are only a few buyers of a certain product or service.
In this ME-P, we will explore the differences between these two market structures and their implications.
ANTI-TRUST: https://medicalexecutivepost.com/2024/12/29/paradox-anti-trust-definition-with-book/
***
***
1. Number of Buyers
The main difference between monopsony and oligopsony is the number of buyers in the market. In a monopsony, there is only one buyer, which gives them significant bargaining power over the suppliers. In contrast, an oligopsony has a few buyers, which means that the suppliers have some bargaining power, but not as much as they would in a perfectly competitive market.
For example, the government is often the only buyer of certain goods and services, such as military equipment, healthcare [ACA] or public transportation. This gives them significant bargaining power over the suppliers, who have no other buyers to turn to. On the other hand, the automobile industry is an example of an oligopsony, with a few large manufacturers controlling the majority of the market. Suppliers have some bargaining power, but they still have to compete for contracts with the few buyers in the market.
2. Price Setting
In a monopsony, the buyer has the power to set the price of the product or service. Since there is only one buyer, the suppliers have no choice but to accept the price offered. This can lead to lower prices for the buyer, but it can also lead to lower quality products or services, as suppliers may cut corners to meet the buyer’s demands.
In an oligopsony, the buyers have some bargaining power, but they still have to compete with each other for the best deals. This can lead to higher prices for the suppliers, but it can also lead to higher quality products or services, as suppliers have more resources to invest in their products.
3. Competition
One of the main advantages of a perfectly competitive market is the competition between buyers and sellers. This competition leads to better prices and higher quality products or services. In a monopsony, there is no competition between buyers, which can lead to lower quality products or services and higher prices for the suppliers.
In an oligopsony, there is some competition between buyers, which can lead to better prices and higher quality products or services. However, the competition is limited to a few buyers, which means that suppliers have less choice and bargaining power than they would in a perfectly competitive market.
***
***
Assessment
The implications of monopsony and oligopsony depend on the specific market and the parties involved. In general, monopsony can lead to lower prices for the buyer, but it can also lead to lower quality products or services and reduced innovation. Oligopsony can lead to higher prices for the suppliers, but it can also lead to higher quality products or services and increased innovation.
Conclusion
Monopsony and oligopsony are two different market structures with different implications for buyers and suppliers. While monopsony can lead to lower prices for the buyer, it can also lead to reduced quality and innovation. Oligopsony can lead to higher prices for the suppliers, but it can also lead to higher quality and increased innovation.
The best option depends on the specific market and the parties involved.
***
***
COMMENTS APPRECIATED
Refer, Like and Subscribe
Filed under: iMBA, Inc. | Tagged: business, China, digital marketing, entrepreneurship, marketing | Leave a comment »
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.CertifiedMedicalPlanner.org
***
***
Launching a successful insurance agency is a bold and rewarding endeavor, blending entrepreneurship with the responsibility of helping individuals and businesses protect what matters most. Building an agency from the ground up requires strategic planning, disciplined execution, and a clear understanding of how to stand out in a competitive marketplace. While every agency’s journey is unique, several core principles consistently shape long‑term success.
A strong foundation begins with defining your vision. Too many new agencies rush into selling policies without first clarifying what they want to be known for. A clear vision answers essential questions: What type of insurance will you specialize in? Who is your ideal client? What values will guide your agency’s culture and service? Whether you focus on personal lines, commercial coverage, life and health, or a niche market, a well‑defined identity helps you attract the right clients and build a brand that resonates.
Once your vision is established, the next step is developing a comprehensive business plan. This plan should outline your mission, goals, target market, and competitive advantages. It also needs to address operational details such as staffing, marketing strategies, and financial projections. A thoughtful business plan serves as a roadmap, helping you stay focused and make informed decisions as your agency grows. It also demonstrates professionalism and preparedness when seeking carrier appointments or financing.
Understanding the regulatory environment is another critical component. Insurance is a highly regulated industry, and compliance is non‑negotiable. You must obtain the appropriate licenses for yourself and your agency, complete required training, and stay current with continuing education. Beyond licensing, you need to understand rules governing advertising, data security, record keeping, and ethical conduct. A commitment to compliance builds trust with clients and carriers and protects your agency from costly penalties.
***
***
Carrier relationships play a central role in your agency’s success. Insurance carriers evaluate agencies based on business plans, financial stability, and potential for profitable growth. Securing appointments with reputable carriers gives you access to competitive products and underwriting support. When approaching carriers, highlight your market research, sales strategy, and commitment to writing quality business. Strong carrier partnerships also provide training, marketing resources, and technology tools that can accelerate your agency’s development.
Technology is no longer optional; it is a core driver of efficiency and client satisfaction. An agency management system helps organize client information, track policies, and streamline workflows. A customer relationship management platform supports lead tracking and follow‑up. Digital quoting tools, electronic signatures, and online scheduling make the client experience smoother and more convenient. A professional website and active online presence help prospects find you and build credibility. Investing in technology early positions your agency as modern, responsive, and easy to work with.
Marketing is the engine that fuels growth. A successful launch requires a blend of digital and traditional strategies. Search engine optimization, social media engagement, and targeted online advertising help you reach prospects who are actively searching for insurance solutions. Community involvement, networking events, and partnerships with local businesses build trust and generate referrals. Consistency is essential; marketing should be an ongoing effort rather than a one‑time push. A strong brand identity—reflected in your messaging, visuals, and customer experience—helps your agency stand out in a crowded field.
Sales skills are equally important. Insurance is fundamentally a relationship‑driven business. Clients choose agencies they trust, and trust is built through listening, educating, and providing personalized solutions. Effective producers ask thoughtful questions, explain coverage clearly, and follow up promptly. A structured sales process ensures that every lead is handled professionally and consistently. Over time, strong client relationships become a powerful source of referrals and cross‑selling opportunities, fueling sustainable growth.
As your agency expands, hiring and training become essential. The right team members amplify your strengths and help you scale. Look for individuals who are coachable, motivated, and aligned with your agency’s values. Provide ongoing training in products, sales techniques, and customer service. A supportive culture that rewards performance and encourages professional development reduces turnover and enhances client satisfaction. Leadership is not just about managing tasks; it is about inspiring your team to deliver excellence.
Financial discipline underpins long‑term success. Track expenses carefully, reinvest profits strategically, and maintain adequate reserves. Monitor key performance indicators such as retention rates, revenue per client, and new business production. These metrics help you identify trends, adjust strategies, and make informed decisions. Sustainable growth comes from balancing new business with strong retention and operational efficiency.
Launching a successful insurance agency requires vision, preparation, and resilience. The early stages demand long hours, continuous learning, and a willingness to adapt. Yet the rewards—financial independence, community impact, and the satisfaction of protecting clients—make the journey worthwhile. With a clear strategy, strong relationships, and a commitment to excellence, your agency can thrive in a competitive industry and build a legacy of trust and service.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Staff Reporters
***
***
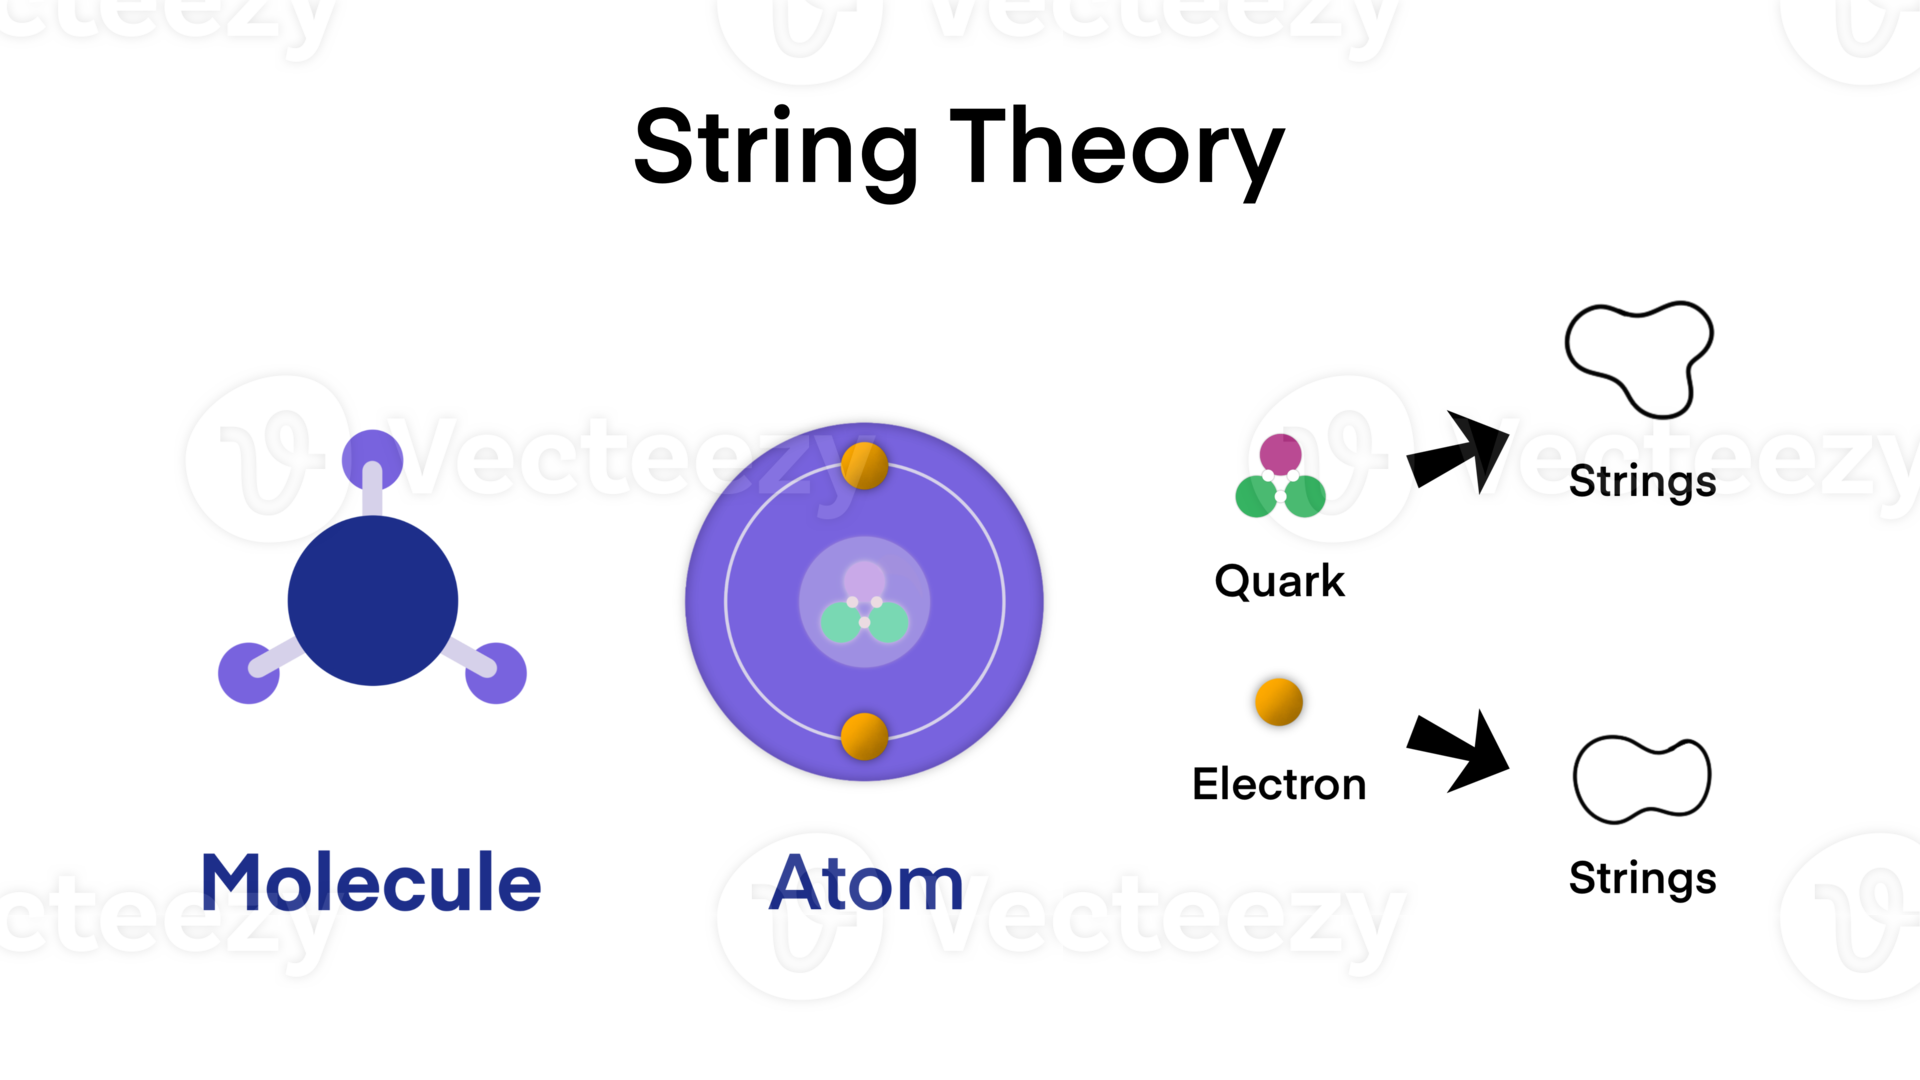
String theory stands as one of the most ambitious and mathematically intricate attempts to understand the fundamental nature of reality. Emerging from the crossroads of quantum mechanics and general relativity, string theory proposes a radical reimagining of the universe’s building blocks—not as point-like particles, but as tiny, vibrating strings. These strings, though unimaginably small, may hold the key to a unified theory of everything.
The origins of string theory trace back to the late 1960s, when physicists sought to explain the strong nuclear force. Initially, string theory was considered a candidate for modeling hadrons, but it was soon overshadowed by quantum chromodynamics. However, the theory’s mathematical structure revealed properties that made it a promising framework for quantum gravity—a domain where traditional physics struggled to reconcile Einstein’s general relativity with quantum mechanics.
Einstein’s theory of general relativity describes gravity as the curvature of spacetime caused by mass and energy, while quantum mechanics governs the behavior of particles at the smallest scales. These two pillars of modern physics, though individually successful, are fundamentally incompatible. String theory offers a potential bridge between them, suggesting that all particles and forces arise from different vibrational modes of one-dimensional strings.
At its heart, string theory replaces point particles with strings—tiny filaments that can be open or closed loops. The way a string vibrates determines the properties of the particle it represents, such as mass and charge. For instance, one vibrational pattern might correspond to an electron, while another might represent a photon.
A striking implication of string theory is the necessity of extra dimensions. While we perceive the universe in three spatial dimensions and one time dimension, string theory requires up to ten spatial dimensions and one time dimension for mathematical consistency. These extra dimensions are thought to be compactified—curled up so tightly that they are imperceptible at human scales. The geometry of these compactified dimensions, often modeled as Calabi-Yau manifolds, influences the physical laws we observe.
Another cornerstone of string theory is supersymmetry, a theoretical symmetry that links bosons (force-carrying particles) and fermions (matter particles). Supersymmetry predicts that every known particle has a heavier superpartner, though none have yet been observed experimentally. If confirmed, supersymmetry could solve several puzzles in particle physics, including the hierarchy problem and the nature of dark matter.
Beyond its quest for unification, string theory has influenced numerous areas of physics and mathematics. It has provided insights into black hole entropy, suggesting that the information content of a black hole can be accounted for by stringy degrees of freedom. The AdS/CFT correspondence, a conjecture arising from string theory, links a gravitational theory in a higher-dimensional space (Anti-de Sitter space) to a conformal field theory on its boundary. This duality has found applications in quantum field theory, condensed matter physics, and even quantum computing
Over time, physicists developed five consistent versions of string theory: Type I, Type IIA, Type IIB, and two heterotic string theories. In the mid-1990s, Edward Witten and others proposed that these seemingly distinct theories were actually different aspects of a single, more fundamental theory known as M-theory. M-theory posits eleven dimensions and includes higher-dimensional objects called branes, to which strings can attach. This unification marked a major milestone in theoretical physics and sparked renewed interest in string theory.
Despite its elegance and potential, string theory faces significant challenges. Foremost among them is the lack of experimental evidence. The energy scales at which stringy effects become apparent are far beyond the reach of current particle accelerators. Moreover, the theory’s vast landscape of possible solutions—estimated to be on the order of 10^500—makes it difficult to extract unique predictions about our universe.
Critics argue that string theory’s reliance on unobservable dimensions and its resistance to empirical testing place it outside the realm of conventional science. Others contend that its mathematical beauty and internal consistency justify continued exploration, even in the absence of direct evidence.
String theory represents a bold and imaginative attempt to unify the forces of nature and reveal the deepest truths of the cosmos. While its experimental validation remains elusive, its impact on theoretical physics and mathematics is undeniable. Whether it ultimately proves to be the “theory of everything” or a stepping stone to a deeper understanding, string theory continues to inspire scientists to look beyond the visible and explore the hidden dimensions of reality.
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: Ask a Doctor, Glossary Terms, Research & Development | Tagged: albert einstein, atoms, black holes, cosmos, fermions, hadron collider, neutrons, protoens, quarks, string theory, strings, supersymmetry | Leave a comment »
By Health Capital Consultants, Inc
***
***
On January 16, 2026, the Department of Justice (DOJ) announced that False Claims Act (FCA) settlements and judgments topped $6.8 billion in fiscal year (FY) 2025, which ended September 30, 2025. This figure marks the largest single-year recovery since the FCA was enacted. The government also opened 401 new investigations. Cumulative FCA settlements and judgments since 1986, when Congress significantly strengthened the statute, now surpass $85 billion.
The FY 2025 recoveries represent a substantial jump from the $2.9 billion collected in FY 2024 and the $2.68 billion collected in FY 2023. (Read more…)
***
***
Filed under: iMBA, Inc. | Leave a comment »
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MarcinkoAssociates.com
***
***
Launching a private medical practice is one of the most rewarding yet challenging steps in a physician’s career. It blends clinical expertise with entrepreneurship, requiring thoughtful planning, financial discipline, and a commitment to building strong patient relationships. While the process can feel overwhelming, breaking it down into key principles makes the journey far more manageable. The following fifteen tips offer a comprehensive guide for physicians preparing to open a thriving private practice.
1. Clarify Your Vision and Mission Every successful practice begins with a clear sense of purpose. Defining your mission helps guide decisions about services, patient experience, and long‑term goals. Whether you aim to provide highly personalized care, focus on a specific specialty, or serve an underserved community, clarity of vision shapes the identity of your practice.
2. Choose the Right Location Location plays a major role in patient volume, accessibility, and visibility. Consider factors such as population demographics, competition, parking availability, and proximity to hospitals. A well‑chosen location can significantly enhance patient convenience and practice growth.
3. Develop a Realistic Business Plan A private practice is a business, and a solid business plan is essential. This includes projected expenses, revenue forecasts, staffing needs, marketing strategies, and growth milestones. A detailed plan not only keeps you organized but also helps secure financing if needed.
4. Understand Your Startup Costs Launching a practice requires upfront investment in equipment, office space, technology, and staffing. Identifying these costs early helps prevent financial surprises. Budgeting for at least several months of operating expenses ensures stability during the initial growth phase.
5. Secure Appropriate Financing Many physicians rely on loans or lines of credit to cover startup expenses. Exploring financing options early allows you to compare terms and choose the most favorable structure. Strong financial planning sets the foundation for long‑term sustainability.
6. Choose the Right Legal Structure Selecting the appropriate legal entity—such as a professional corporation or limited liability company—affects taxes, liability, and ownership. Consulting legal and financial professionals helps ensure your practice is structured in a way that protects your interests.
***
***
7. Obtain All Required Licenses and Credentials Credentialing with insurance companies, securing state licenses, and meeting regulatory requirements can take time. Starting this process early prevents delays in opening your doors and ensures you can bill for services from day one.
8. Invest in Efficient Technology Electronic health records, scheduling systems, billing software, and telehealth platforms are essential tools for modern practices. Choosing user‑friendly, integrated systems improves workflow, reduces administrative burden, and enhances patient satisfaction.
9. Build a Strong Support Team Your staff is the backbone of your practice. Hiring skilled, compassionate individuals—front desk personnel, medical assistants, billers, and nurses—creates a welcoming environment for patients. Investing in training and fostering a positive culture helps retain great employees.
10. Create a Patient‑Centered Experience Patients remember how they are treated as much as the care they receive. Simple touches like short wait times, clear communication, and a warm office atmosphere build loyalty. A patient‑centered approach encourages word‑of‑mouth referrals, which are invaluable for new practices.
11. Develop a Strategic Marketing Plan Marketing is essential for attracting patients, especially in the early stages. A professional website, social media presence, community outreach, and partnerships with local providers help increase visibility. Consistent branding reinforces your practice’s identity and values.
12. Master the Financial Side of Medicine Understanding billing, coding, insurance reimbursement, and cash flow management is crucial. Even if you outsource billing, having a working knowledge of financial operations helps you make informed decisions and avoid costly errors.
13. Prioritize Compliance and Risk Management Private practices must adhere to numerous regulations, from privacy laws to workplace safety standards. Establishing clear policies and conducting regular training protects both your patients and your practice.
14. Stay Flexible and Open to Change The healthcare landscape evolves quickly. Successful practices adapt by embracing new technologies, adjusting workflows, and responding to patient needs. Flexibility allows your practice to grow sustainably and remain competitive.
15. Maintain Work‑Life Balance Launching a practice requires dedication, but burnout can undermine your long‑term success. Setting boundaries, delegating tasks, and taking time for personal well‑being helps you stay energized and focused on delivering excellent care.
Opening a private medical practice is a bold and meaningful step. With thoughtful planning, strong leadership, and a commitment to patient‑centered care, physicians can build practices that are both professionally fulfilling and financially successful. Each of these fifteen tips contributes to a foundation that supports long‑term growth, stability, and the ability to make a lasting impact on the community you serve.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
If you want the opportunity to reach a personalized weekly audience of health care industry insiders, innovators and watchers, the Medical Executive-Post and its educational forums may be right for you?
We are discussed, read and viewed by medical students, physicians, dentists, podiatrists, optometrists and industry analysts; as well as health care administrators, office managers, CXOs, investors, Wall Street insiders and nurse-executives from many health systems in the country. Advertise with us and you’ll put your brand in front of a smart & tightly focused demographic; one at the forefront of our emerging healthcare marketplace of collaboratively informed and professional “movers and shakers.”
Why Advertise with Us?
America‘s medical professionals, practice management consultants and physician focused financial advisors are gravitating to the Internet for informational needs on the healthcare industrial complex. And, since no media currently satisfies their unique personal needs as busy and overburdened professionals, our fundamental mission will be to serve as the interactive business, economic, educational and personal social communication forum for medical professions and related industry participants.
We feature tips, tools, essays, interview, blog comments and other innovative thought-leadership ideas and resources In this day and age of over-saturated information and promotion, our timely and useful web site presents a distinctive opportunity for marketers to make a meaningful connection with busy doctors and al their consulting advisors. And, clearly, there’s a need for a personal, fast-paced, relevant, protean and practical business resource for all medical professionals.
For example, according to a 2012 Physicians’ Financial News survey of 650 doctors:
· 86% go online “every day or week” for business information
· 85% are “interested” in a new business web site for themselves
· 70% are “worried” about their medical business.
According to recent studies from two leading health care research companies Manhattan Research and PERQ/HCI:
· 86% of physicians want news and professional links on a web portal
· 80% “always or sometimes” notice online ads
· 78% use the Internet for professional purposes
· 76% want product and treatment updates delivered by e-detailing
· 64% get e-newsletters
· 60 want blogs from “key opinion leaders.”
· 53% spend more than 15 minutes during an Internet visit.
What the Marketing Experts Say
Most marketing experts agree that correct ad placement is important for building exposure for your brand, product or web site. Placing your targeted link in a prominent location on the Medical Executive Post sidebar is therefore vital.
A limited number of spots are available so act quickly to reserve your place, for TODAY AND TOMORROW!
And, our Medical Executive Post syndicated news feeds go out almost daily to a large audience of senior healthcare administrators and physician-executive readers … and we are growing!
So, catch the eye of some of the smartest people in the health care industry including observers, investors, big pharma, IT executives, CEOs, CFOs, pundits and financial managers – all at the top health care systems, clinics, ASCs, hospitals and physician group practices in the country. And, advertise on the Medical Executive-Post.
Of course, we are also happy to work with you to create a specialized content section or other innovative promotional package emphasizing your brand and targeting a specific health sector, too.
Sign-up Bonus: The first month is free to qualified individuals and entities. Contact us for details.
8


Legal Disclaimer:By using the Medical Executive-Post web site, services and discussion groups, you signify acceptance of our Privacy olicy and Terms of Use(r) Agreement. We do not endorse any company/group/website or individual, we perform no background checks or due perform diligence on anyone listing a job or responding to a job posting, we are not liable for any misuse of our services or misrepresentation by our users. You also agree to hold the Medical Executive Post, and iMBA, Inc and its officers or representatives harmless.
FURTHERMORE, WE ARE NOT LIABLE FOR ANY DAMAGES WHATSOEVER (INCLUDING, WITHOUT LIMITATION, DAMAGES FOR LOSS OF PROFITS, BUSINESS INTERRUPTION, LOSS OF INFORMATION) ARISING OUT OF THE USE OF OR INABILITY TO USE THE MATERIALS, EVEN IF WE HAVE BEEN ADVISED OF THE POSSIBILITY OF SUCH DAMAGES.
If you do not agree to this policy, please do not use our site or services. Your continued use of this site, services and discussion groups following the posting of changes to these terms will mean that you accept those changes. We reserve the right to remove any posting(s) at any time and for any reason. You may not solicit, email or contact Post members without their permission.
Finally the ME-P reserves the right to change the information on this website without notice. We make no representations about the accuracy or completeness of the information on this website or that material available from this site is free of viruses.
***
Filed under: MAST-HEAD | Tagged: Advertise with Us? | 12 Comments »
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MarcinkoAssociates.com
***
***
Launching a successful wealth management practice is both an entrepreneurial pursuit and a long‑term commitment to guiding clients through some of the most important financial decisions of their lives. It requires a blend of technical expertise, strategic planning, emotional intelligence, and a clear vision for the type of advisory firm you want to build. While the industry is competitive, it also offers tremendous opportunity for advisors who can combine trust, competence, and a client‑centered approach. Building a thriving practice begins with a strong foundation and a deliberate strategy that supports sustainable growth.
A successful launch starts with defining your value proposition. Wealth management is a broad field, and clients have countless options for financial advice. To stand out, you need clarity about what makes your practice unique. This includes identifying your target market, the services you will offer, and the philosophy that guides your approach to financial planning and investment management. Some advisors focus on retirees seeking income strategies, while others specialize in business owners, high‑net‑worth families, or young professionals accumulating wealth. A well‑defined niche helps you tailor your messaging, refine your expertise, and build deeper relationships with the clients you are best equipped to serve.
***
***
Once your value proposition is clear, the next step is developing a comprehensive business plan. This plan should outline your mission, goals, operational structure, and financial projections. It should also address how you will attract clients, what technology you will use, and how you will manage compliance and regulatory requirements. A strong business plan acts as a roadmap, helping you stay focused and make informed decisions as your practice grows. It also provides structure during the early stages when you are juggling multiple responsibilities and building systems from scratch.
Regulatory compliance is a critical component of launching a wealth management practice. Whether you operate as an independent registered investment advisor or affiliate with a broker‑dealer, you must understand the rules governing client communication, record keeping, fiduciary responsibilities, and investment recommendations. Compliance is not simply a legal requirement; it is a foundation of trust. Clients rely on you to act in their best interest, safeguard their information, and provide transparent guidance. Establishing strong compliance processes early helps you avoid costly mistakes and reinforces your commitment to ethical practice.
Technology plays a transformative role in modern wealth management. A robust technology stack can streamline operations, enhance client experiences, and improve your ability to scale. Essential tools include financial planning software, portfolio management systems, customer relationship management platforms, and secure communication channels. Digital onboarding, electronic signatures, and client portals create a seamless experience that meets the expectations of today’s investors. Technology also supports data‑driven decision‑making, allowing you to analyze portfolios, track performance, and deliver personalized advice efficiently. Investing in the right tools early positions your practice as modern, responsive, and client‑focused.
Marketing is another cornerstone of a successful launch. Wealth management is a relationship‑driven business, but relationships rarely form without visibility. A strong marketing strategy blends digital outreach with personal engagement. A professional website, educational content, and a consistent presence on social media help establish credibility and attract prospects. Hosting workshops, participating in community events, and building partnerships with accountants, attorneys, and other professionals can generate referrals and expand your network. The key is consistency. Marketing should be an ongoing effort that reinforces your brand and communicates the value you bring to clients’ financial lives.
Client experience is where successful practices truly differentiate themselves. Wealth management is not just about numbers; it is about understanding clients’ goals, fears, and aspirations. Effective advisors listen deeply, ask thoughtful questions, and tailor their recommendations to each client’s unique circumstances. Building trust requires transparency, clear communication, and a commitment to ongoing education. Clients want to feel understood and supported, not just managed. Establishing a structured onboarding process, regular review meetings, and proactive outreach helps create a sense of partnership and reliability. Over time, exceptional client experience becomes your most powerful marketing tool, driving referrals and long‑term loyalty.
As your practice grows, building the right team becomes essential. Even if you start as a solo advisor, you will eventually need support to manage operations, compliance, marketing, and client service. Hiring individuals who share your values and complement your strengths allows you to scale without sacrificing quality. Training and professional development should be ongoing, ensuring your team stays current with industry trends, regulatory changes, and best practices. A strong culture—one that emphasizes integrity, collaboration, and client‑centered service—helps attract and retain both talent and clients.
Financial discipline underpins the long‑term viability of your practice. In the early stages, revenue may be inconsistent, and expenses can accumulate quickly. Careful budgeting, realistic forecasting, and strategic reinvestment are essential. Monitoring key performance indicators such as client acquisition cost, assets under management, revenue per client, and retention rates helps you evaluate progress and make informed decisions. Sustainable growth comes from balancing new client acquisition with deepening relationships and delivering consistent value.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
A FINANCIAL THEORY
By Staff Reporters
***
***
FINANCIAL THEORY
Theories of finance are essential for understanding and analyzing various financial phenomena. They provide the conceptual framework for investment strategies, risk management, and financial decision-making.
***
Merton’s Model for Credit Risk, developed by Robert C. Merton in 1974, represents a significant advancement in the field of financial economics, particularly in the assessment of credit risk. Building upon the foundations of the Black-Scholes Model for options pricing, Merton’s approach introduced a novel method for valuing corporate debt and assessing the probability of default.
Merton’s model conceptualizes a company’s equity as a call option on its assets, with the strike price equivalent to the debt’s face value maturing at the debt’s due date. In this framework, if the value of the company’s assets falls below the debt’s face value at maturity, the firm defaults, as it is more beneficial for equity holders to hand over the assets to the debt holders rather than repay the debt. Conversely, if the asset value exceeds the debt value, the firm pays off its debt and equity holders retain control of the company.
The model calculates the risk of default by analyzing the volatility of the firm’s assets and the level of its liabilities. The key insight of the model is that the safer a company’s debt (lower probability of default), the less valuable the equity as a call option, and vice versa. This approach provides a more dynamic and market-based view of credit risk, as opposed to traditional static measures.
***
***
One of the model’s critical assumptions is that the firm’s assets follow a random walk and are normally distributed. The model also presumes that markets are efficient, and there is no friction in trading. Furthermore, Merton’s model assumes that the firm’s capital structure only comprises equity and zero-coupon debt, which simplifies the real-world complexities of corporate finance.
Despite these simplifications, Merton’s model has had a profound impact on the field of credit risk analysis. It laid the groundwork for the development of more sophisticated credit risk models and tools used in the financial industry, such as Moody’s KMV Model. These models have become integral in the risk management practices of banks and financial institutions, particularly in the assessment of counter-party risk and the pricing of risky debt.
In conclusion, Merton’s Model for Credit Risk has been instrumental in bridging the gap between corporate finance and asset pricing theory. It has provided a more comprehensive and market-based framework for understanding and managing credit risk, which has been pivotal for both academia and the financial industry. The model’s influence extends beyond credit risk analysis, affecting the broader areas of corporate finance, risk management, and financial regulation.
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: "Ask-an-Advisor", business, economics, finance, Glossary Terms, Investing, Portfolio Management | Tagged: Black-Scholes, corporate finance, credit risk, default, economics, finance, financial theory, Merton's Theory, MOODY, Moody's KMV Model, normal distribution, Risk Management, Robert Merton | Leave a comment »
***
***
President Trump is tapping former Federal Reserve official Kevin Warsh to succeed outgoing Fed Chair Jerome Powell, a change in leadership at the central bank that could also augur a shift in monetary FOMC policy.
COMMENTS APPRECIATED
***
Filed under: iMBA, Inc. | Leave a comment »
Dr. David Edward Marcinko, MBA MEd CMP
SPONSOR: http://www.CertifiedMedicalPlanner.org
***
***
The modern digital economy is powered by a small group of technology giants whose infrastructure, scale, and influence have reshaped how the world computes, communicates, and innovates. Among these, four companies—Amazon, Microsoft, Google, and Meta—stand out as the dominant hyperscalers. Their massive global data‑center footprints, cloud platforms, and AI‑driven ecosystems form the backbone of today’s internet services, enterprise computing, and emerging technologies. Understanding their roles reveals how deeply they shape the technological landscape and why their strategic decisions ripple across industries worldwide.
Amazon, through Amazon Web Services (AWS), is widely regarded as the pioneer of hyperscale cloud computing. What began as an internal effort to streamline infrastructure evolved into the world’s largest cloud platform, offering compute, storage, networking, and a vast array of specialized services. AWS’s strength lies in its breadth and maturity: it supports millions of customers, from startups to governments, and continues to expand aggressively into artificial intelligence, machine learning, and edge computing. Its global network of data centers enables rapid deployment and scalability, making it the default choice for many organizations seeking reliability and flexibility. Amazon’s hyperscale strategy is rooted in relentless expansion, operational efficiency, and a willingness to invest heavily in infrastructure long before demand peaks.
Microsoft, through Azure, has emerged as a formidable competitor by leveraging its deep enterprise relationships and software ecosystem. Unlike Amazon, Microsoft entered the hyperscale market with decades of experience supplying businesses with operating systems, productivity tools, and developer platforms. Azure integrates seamlessly with these products, creating a powerful incentive for organizations already embedded in the Microsoft environment. Beyond cloud infrastructure, Microsoft’s hyperscale influence extends into artificial intelligence, cybersecurity, and hybrid cloud solutions. Its acquisition strategy, including major investments in AI research and partnerships, reinforces its position as a leader in enterprise‑grade cloud services. Microsoft’s hyperscale philosophy emphasizes trust, compliance, and integration—qualities that resonate strongly with regulated industries.
Google, known for its search engine and advertising dominance, brings a different kind of expertise to hyperscale computing. Its cloud platform, Google Cloud, is built on the same infrastructure that powers its global search, YouTube, and mapping services. Google’s hyperscale advantage lies in its engineering excellence: it has pioneered innovations in distributed systems, data analytics, and artificial intelligence. Technologies such as container orchestration and advanced machine learning frameworks originated within Google before becoming industry standards. While Google Cloud entered the enterprise market later than AWS and Azure, it has gained traction by focusing on data‑intensive workloads, sustainability leadership, and open‑source collaboration. Google’s hyperscale identity is defined by technical innovation and a commitment to pushing the boundaries of what large‑scale computing can achieve.
Meta, the parent company of Facebook, Instagram, and WhatsApp, represents a different but equally significant form of hyperscaling. Unlike the others, Meta does not operate a commercial cloud platform; instead, it builds hyperscale infrastructure to support its own massive social networks and immersive technologies. Meta’s data centers handle billions of daily interactions, real‑time communication, and vast multimedia content. Its hyperscale efforts increasingly focus on artificial intelligence, recommendation systems, and the development of virtual and augmented reality platforms. As Meta invests in the future of digital interaction—particularly through its vision of immersive virtual environments—it continues to expand and optimize its global infrastructure. Meta’s hyperscale strategy is driven by user engagement at unprecedented scale and the computational demands of next‑generation social technologies.
Together, these four hyperscalers form the foundation of the digital era. They enable global connectivity, power critical business operations, and accelerate innovation across sectors. Their investments in artificial intelligence, sustainability, and next‑generation computing will shape the trajectory of technology for decades to come. While each company approaches hyperscaling from a distinct angle—commercial cloud services, enterprise integration, engineering innovation, or social connectivity—they collectively define the infrastructure of modern life. Understanding their roles is essential to understanding the future of the digital world.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Staff Reporters
SPONSOR: http://www.CertifiedMedicalPlanner.org
***
***
The history of U.S. recessions reflects the nation’s evolving economy, shaped by wars, financial crises, policy shifts, and global events. Since 1857, the U.S. has experienced over 30 recessions, each offering lessons in resilience and reform.
The United States has endured a long and varied history of economic recessions, defined as periods of significant decline in economic activity lasting more than a few months. These downturns are typically marked by falling GDP, rising unemployment, and reduced consumer spending. Since the mid-19th century, recessions have been triggered by a range of factors—from banking panics and inflation to global conflicts and pandemics.
The earliest recorded U.S. recession began in 1857, sparked by a banking crisis and declining international trade. This was followed by the Long Depression of 1873–1879, which lasted a staggering 65 months, making it the longest in U.S. history. The downturn was triggered by the collapse of a major bank and a speculative bubble in railroad investments.
The Great Depression remains the most severe economic crisis in American history. Beginning in 1929 after the stock market crash, it lasted until 1933 and saw unemployment soar to 25%. The Depression reshaped U.S. economic policy, leading to the creation of Social Security, the FDIC, and other New Deal programs aimed at stabilizing the economy and protecting citizens.
Post-World War II recessions were generally shorter and less severe. The 1945 recession, for example, lasted eight months and was caused by the transition from wartime to peacetime production. The 1973–75 recession, however, was more prolonged, driven by an oil embargo and stagflation—a combination of stagnant growth and high inflation.
The early 1980s recession was triggered by the Federal Reserve’s aggressive interest rate hikes to combat inflation. Though painful, it ultimately helped stabilize prices and set the stage for a long period of growth. The early 1990s recession followed a savings and loan crisis and a slowdown in defense spending after the Cold War.
The Great Recession of 2007–2009 was the most significant downturn since the Great Depression. It was caused by the collapse of the housing bubble and widespread failures in financial institutions. Unemployment peaked at 10%, and the crisis led to sweeping reforms in banking and mortgage lending practices.
Most recently, the COVID-19 recession in 2020 was the shortest in U.S. history, lasting just two months. Despite its brevity, it was severe, with unemployment briefly reaching 14.7% due to lockdowns and global supply chain disruptions.
Throughout its history, the U.S. has shown remarkable resilience in recovering from recessions. Each downturn has prompted changes in fiscal and monetary policy, regulatory reform, and shifts in public perception about the role of government and markets. As the economy becomes more interconnected globally, future recessions may be shaped by international events as much as domestic ones.
COMMENTS APPRECIATED
SPEAKING: ME-P Editor Dr. David Edward Marcinko MBA MEd will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: "Ask-an-Advisor", business, CMP Program, economics, finance, Financial Planning, iMBA, Inc., Portfolio Management | Tagged: 1945 recession, banks, CMP, covid recession, depression, economy, Federal Reserve, finance, FOMC, GDP, inflation, interest rates, loan crisis, mortgage, recessions, stagflation | Leave a comment »
SPONSOR: http://www.MarcinkoAssociates.com
Dr. David Edward Marcinko MBA MEd
***
***
Retirement is often imagined as a distant horizon, something to be considered “later” once the demands of medicine finally loosen their grip. Yet for many physicians, the transition from a career defined by purpose, structure, and intensity into a life of freedom can feel surprisingly complex. Financial readiness is only one part of the equation; emotional, professional, and lifestyle planning matter just as much. A successful retirement for doctors requires intention, clarity, and a willingness to design a future that feels as meaningful as the years spent in practice. The following ten tips offer a comprehensive roadmap to help physicians prepare for a retirement that is not only financially secure but deeply satisfying.
Doctors often begin their earning years later than most professionals due to years of training, residency, and fellowship. This delayed start makes early planning even more essential. The power of compounding works best over long periods, so even modest contributions early in a career can grow significantly. Early planning also gives physicians the flexibility to adjust their goals, adapt to life changes, and avoid the pressure of last‑minute financial decisions. Retirement is not a single event but a long-term project, and the earlier the blueprint is drafted, the stronger the foundation becomes.
Many physicians know how to plan a treatment regimen for a patient but rarely apply the same clarity to their own long-term goals. A successful retirement begins with a clear vision: What does an ideal day look like? Where do you want to live? How much travel, leisure, or volunteer work do you imagine? Without a defined vision, financial planning becomes guesswork. With one, it becomes a targeted strategy. Physicians who articulate their personal and professional aspirations for retirement—whether that includes part-time work, teaching, or complete disengagement from medicine—are better equipped to build a plan that supports those dreams.
Physicians often earn high incomes, but that does not automatically translate into long-term wealth. A thoughtful financial strategy is essential. This includes maximizing retirement accounts, diversifying investments, and understanding tax implications. Many doctors benefit from working with financial professionals who understand the unique challenges of medical careers, such as fluctuating income, practice ownership, or late-career peak earnings. A strong financial strategy also includes preparing for healthcare costs, long-term care, and unexpected life events. The goal is not simply to accumulate wealth but to create a sustainable financial ecosystem that supports decades of retirement.
***
***
After years of training on modest salaries, the jump to attending-level income can feel liberating. It’s easy to upgrade homes, cars, vacations, and daily habits. While there is nothing wrong with enjoying the rewards of hard work, unchecked lifestyle inflation can erode long-term financial security. Physicians who maintain a balanced lifestyle—one that allows enjoyment without sacrificing future stability—tend to retire earlier, with more freedom and less stress. The key is intentional spending: choosing what truly adds value rather than reacting to external expectations or comparisons.
A physician’s most valuable financial asset during their working years is their ability to earn. Disability insurance, malpractice coverage, and proper legal protections are essential components of a secure retirement plan. Unexpected illness, injury, or legal challenges can derail even the most carefully constructed financial strategy. Protecting income and assets ensures that retirement planning stays on track regardless of unforeseen circumstances. This step is often overlooked, yet it is one of the most powerful ways to safeguard long-term stability.
Many doctors struggle with the emotional shift that comes with retirement. Medicine is more than a job—it is an identity, a calling, and a source of daily structure. A gradual transition can ease this shift. Options include part-time work, locum tenens assignments, consulting, or teaching. These roles allow physicians to maintain a sense of purpose while adjusting to a slower pace. A phased retirement also provides continued income and benefits, giving doctors more flexibility as they refine their long-term plans.
Physicians spend their careers caring for others, often at the expense of their own well-being. Retirement offers an opportunity to recalibrate. Maintaining physical health through exercise, nutrition, and preventive care is essential for enjoying the freedom retirement brings. Equally important is mental and emotional health. Many doctors experience a loss of identity or purpose when they leave practice. Building a support network, cultivating hobbies, and staying socially engaged can help maintain a sense of fulfillment. A healthy retirement is not just about longevity—it’s about quality of life.
***
***
A successful retirement is not defined by the absence of work but by the presence of meaningful activities. Physicians who develop interests outside of medicine—whether travel, writing, gardening, music, or community service—tend to transition more smoothly. These interests provide structure, joy, and a sense of identity beyond the white coat. Retirement becomes an opportunity to rediscover passions that may have been set aside during years of demanding schedules.
The intensity of a medical career can strain relationships. Long hours, emotional fatigue, and unpredictable schedules often leave little time for family and friends. Retirement offers a chance to reconnect. Investing in relationships—through shared activities, meaningful conversations, or simply being present—can enrich daily life and provide emotional grounding. Strong relationships are one of the most reliable predictors of happiness in retirement, and physicians who nurture them early experience a smoother transition.
Even the best retirement plans require adjustments. Markets fluctuate, health changes, and personal priorities evolve. Physicians who approach retirement with flexibility are better equipped to navigate these shifts. Adaptability allows for creative solutions, whether that means adjusting spending, exploring new income opportunities, or redefining personal goals. Retirement is not a static phase but a dynamic chapter, and embracing change can make it more rewarding.
A successful retirement for doctors is built on more than financial preparation. It requires clarity of purpose, emotional readiness, and a willingness to design a life that feels meaningful beyond the walls of a clinic or hospital. By planning early, protecting assets, nurturing relationships, and cultivating interests outside of medicine, physicians can create a retirement that is not only secure but deeply fulfilling. The transition from a life of service to a life of personal freedom is one of the most significant journeys a doctor will take—and with thoughtful preparation, it can be one of the most rewarding.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MarcinkoAssociates.com
***
***
The evolving landscape of surgical education demands frameworks that integrate technical proficiency, cognitive development, professional identity formation, and global collaboration. The concept of the Zwishmodek—a theoretical model for structuring and evaluating surgical training—offers a multidimensional approach that aligns with the needs of modern surgical practice. This essay examines the Zwishmodek as a comprehensive educational paradigm, exploring its core components, pedagogical implications, and potential to reshape the future of surgical training.
Surgical education has historically been shaped by apprenticeship models, hierarchical structures, and time‑based progression. As surgical practice becomes increasingly complex, these traditional approaches face limitations in ensuring consistent competency, patient safety, and equitable training experiences. The Zwishmodek, though not an established term in existing literature, can be conceptualized as a forward‑looking framework that synthesizes contemporary educational principles into a cohesive model. It emphasizes competency‑based progression, technological integration, reflective practice, and global inter connectedness. By articulating these elements, the Zwishmodek model provides a lens through which surgical educators can re imagine training for the twenty‑first century.
***
***
A central tenet of the Zwishmodek is the prioritization of competency over time‑based advancement. Traditional surgical training often assumes that prolonged exposure naturally yields proficiency. However, variability in learning pace, case availability, and institutional resources can lead to inconsistent outcomes. The Zwishmodek reframes progression as a function of demonstrated mastery rather than duration.
This approach requires clearly defined competencies, structured assessment tools, and individualized learning trajectories. Trainees advance only when they exhibit reliable performance across cognitive, technical, and behavioral domains. Such a model enhances patient safety by ensuring that learners undertake complex procedures only after achieving foundational competence. It also promotes equity by allowing trainees with different learning styles or backgrounds to progress at appropriate rates without stigma or disadvantage.
The Zwishmodek positions technology not as an adjunct but as an integral component of surgical training. Modern surgical education already incorporates simulation, virtual reality, and digital learning platforms, yet the Zwishmodek envisions a deeper and more systematic integration.
Simulation‑based training enables learners to practice high‑risk or infrequent procedures in controlled environments. Virtual and augmented reality systems allow for immersive rehearsal of patient‑specific anatomy, enhancing spatial understanding and procedural planning. Artificial intelligence can analyze performance metrics—such as instrument trajectory, force application, and operative efficiency—providing objective feedback that surpasses traditional observational assessment.
Digital platforms also expand access to surgical knowledge. Video libraries, interactive modules, and remote case discussions allow trainees across geographic and socioeconomic boundaries to engage with expert instruction. Within the Zwishmodek, technology becomes a democratizing force, reducing disparities in training quality and enabling continuous, data‑driven improvement.
Technical skill alone does not define surgical competence. Surgeons must also cultivate ethical judgment, emotional resilience, and reflective capacity. The Zwishmodek incorporates structured reflection as a core pedagogical element, recognizing its role in shaping professional identity and lifelong learning habits.
Reflective practice may take the form of postoperative debriefings, morbidity and mortality analyses, guided self‑assessment, or narrative reflection. These activities encourage trainees to examine their decision‑making processes, recognize cognitive biases, and internalize lessons from both successful and challenging cases. Mentorship plays a critical role in this dimension, as experienced surgeons model professionalism, empathy, and accountability.
By embedding reflection into the educational structure, the Zwishmodek fosters clinicians who are not only technically proficient but also self‑aware, ethically grounded, and capable of navigating the emotional complexities of surgical practice.
The Zwishmodek acknowledges that surgical education exists within a global ecosystem marked by significant disparities in resources, training opportunities, and patient outcomes. A core component of the model is the promotion of international collaboration and equitable access to educational tools.
Digital connectivity enables cross‑border mentorship, shared curricula, and collaborative case discussions. Trainees can observe procedures performed in diverse settings, broadening their clinical perspective and exposing them to varied disease patterns. Institutions can partner to develop shared simulation resources, exchange faculty expertise, and support capacity‑building in low‑resource environments.
By emphasizing global interconnectedness, the Zwishmodek positions surgical education as a collective responsibility. Improving training worldwide ultimately enhances the quality of care delivered to patients across all regions.
The Zwishmodek offers a holistic vision for the future of surgical training. Its emphasis on competency‑based progression aligns with contemporary educational theory, while its integration of technology reflects the realities of modern surgical practice. The inclusion of reflective practice ensures that trainees develop not only technical skill but also the professional maturity required for high‑stakes clinical environments. Finally, its global orientation promotes equity and shared advancement.
Implementing the Zwishmodek requires institutional commitment, faculty development, and investment in technological infrastructure. It also demands cultural shifts toward transparency, adaptability, and learner‑centered pedagogy. Yet the potential benefits—more consistent training outcomes, enhanced patient safety, and a more interconnected global surgical community—justify the effort.
The Zwishmodek represents a conceptual framework that synthesizes the essential elements of modern surgical education into a unified model. By integrating competency‑based progression, technological augmentation, reflective practice, and global collaboration, it offers a blueprint for training surgeons who are technically skilled, ethically grounded, and prepared to meet the evolving demands of their profession. As surgical education continues to transform, the Zwishmodek provides a compelling vision for a more adaptive, equitable, and effective future.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Staff Reporters
SPONSOR: http://www.MarcinkoAssociates.com
***
***
New stock market indices are frequently created to track emerging sectors, regional markets, or particular investment strategies. However, some of the recent and notable stock market indices introduced in recent years focus on new trends or themes such as technology, sustainability, and ESG (Environmental, Social, and Governance) factors. Here are a few noteworthy examples:
One of the newer and increasingly popular indices is the S&P 500 ESG Index, launched in 2021. This index tracks the performance of the companies within the S&P 500 that meet certain environmental, social, and governance (ESG) criteria. The S&P 500 ESG Index aims to provide a more sustainable and socially responsible alternative to the traditional S&P 500 index. It excludes companies involved in industries like tobacco, firearms, or fossil fuels, reflecting the growing interest in socially responsible investing.
Another significant ESG-focused index is the Nasdaq-100 ESG Index, also introduced in 2021. This index tracks the Nasdaq-100, which is typically made up of the 100 largest non-financial companies listed on the Nasdaq stock exchange, but it filters those companies to include only those with strong ESG scores. Given the rapid growth of ESG investing, indices like this one are becoming increasingly important for socially-conscious investors.
The Global X Metaverse ETF Index, introduced in 2022, is another example of a new market index targeting a specific, emerging sector. This index focuses on companies involved in the development of the metaverse, which encompasses technologies like virtual reality (VR), augmented reality (AR), and other digital experiences. As the concept of the metaverse gains popularity, this index is designed to provide investors with exposure to companies working within this new virtual space.
This is an example of a more niche index, combining high-dividend yield investing with ESG factors. Introduced by FTSE Russell in 2022, this index is designed for investors looking for companies with high dividend yields while also considering sustainability and ethical investment criteria. It is part of a broader trend where investors seek to combine solid financial returns with socially responsible practices.
As cryptocurrency continues to grow in prominence, more indices focused on digital assets and cryptocurrency have emerged. For instance, the S&P Bitcoin Index and the Nasdaq Crypto Index were created to provide benchmarks for the growing market of cryptocurrencies and blockchain technology companies. These indices help investors track the performance of digital currencies and crypto-related stocks or funds.
New stock market indices are created for several reasons:
While the S&P 500 ESG Index and Nasdaq-100 ESG Index are among the newest mainstream indices focusing on socially responsible investing, there are also many other niche indices targeting rapidly growing sectors like the metaverse, cryptocurrencies, and digital assets. These indices reflect the evolving nature of global markets and the increasing interest in themes such as sustainability and technological innovation. With such rapid change in the financial landscape, it’s likely that even more specialized indices will continue to emerge in the coming years.
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: "Advisors Only", "Ask-an-Advisor", economics, finance, Investing, Marcinko Associates, Portfolio Management | Tagged: Bitcoin, bitcon, cryptocurrency, digital assets index, Global X Metaverse ETF Index, Investing, Marcinko, NASDAQ, NASDAQ-100 ESG, S&P 500 | Leave a comment »
Dr. David Edward Marcinko; MBA MEd CMP
SPONSOR: http://www.CertifiedMedicalPlanner.org
***
***
Retirement security has been a recurring theme in American economic policy, and the Trump administration approached the issue with a mix of tax incentives, regulatory adjustments, and proposals aimed at expanding access to long‑term savings. Although not all ideas became law, the administration’s overall direction reflected an effort to simplify retirement planning, encourage personal savings, and give workers more flexibility in how they use their retirement funds. Understanding these proposals requires looking at the broader philosophy behind them as well as the specific mechanisms that were introduced or suggested.
One of the most notable changes during the Trump administration was the passage of the SECURE Act, which reshaped several aspects of retirement planning. While the legislation was bipartisan, the administration supported its goals of expanding access to retirement accounts and modernizing outdated rules. The act raised the age for required minimum distributions, allowing retirees to keep money invested for a longer period. It also removed the age cap for contributions to traditional IRAs, acknowledging that many Americans continue working past traditional retirement age. These changes reflected a broader recognition that retirement patterns have shifted and that policies needed to adapt to longer life expectancy and evolving work habits.
Another major theme was expanding access to employer‑sponsored retirement plans. Many small businesses struggle to offer 401(k) plans due to administrative costs and regulatory complexity. The Trump administration supported provisions that made it easier for small employers to join together in pooled retirement plans, reducing overhead and increasing participation. This approach aimed to close the gap between workers at large corporations, who typically have access to robust retirement benefits, and those employed by small businesses, who often do not.
The administration also explored ways to give workers more flexibility in how they use their retirement savings. One proposal allowed penalty‑free withdrawals from retirement accounts for certain life events, such as the birth or adoption of a child. Another idea, discussed but not enacted, involved allowing limited penalty‑free withdrawals for first‑time home purchases. These proposals reflected a belief that retirement accounts could serve as broader financial tools rather than strictly locked‑away funds. Supporters argued that this flexibility would help families manage major expenses without resorting to high‑interest debt, while critics worried that early withdrawals could undermine long‑term savings.
Tax policy played a central role as well. The administration’s broader tax reform efforts included discussions about “Rothification,” a shift toward encouraging after‑tax contributions rather than pre‑tax deductions. While the idea was debated, it did not become law. Still, the conversation highlighted a tension in retirement policy: whether to prioritize immediate tax relief for workers or long‑term revenue stability for the government. The administration generally favored approaches that reduced taxes on investment growth and encouraged individuals to take more responsibility for their financial futures.
Another area of focus was investment choice. The administration supported regulatory changes that made it easier for retirement plans to include annuities, which provide guaranteed lifetime income. Advocates argued that annuities could help retirees avoid outliving their savings, while opponents raised concerns about fees and complexity. The policy direction suggested a desire to give workers more tools to manage longevity risk, even if those tools were not universally embraced.
The administration also revisited fiduciary rules governing financial advisors. A previous rule would have required advisors to act strictly in the best interest of clients when handling retirement accounts. The Trump administration replaced it with a more flexible standard, arguing that the earlier rule limited consumer choice and increased costs. Supporters of the change believed it preserved access to a wider range of financial products, while critics argued it weakened protections for savers. This debate reflected a broader philosophical divide about the balance between regulation and market freedom.
Taken together, the Trump‑era retirement account proposals reveal a consistent set of priorities: expanding access to savings vehicles, increasing flexibility for workers, reducing regulatory burdens on employers, and encouraging long‑term investment. While not all ideas were implemented, the overall direction emphasized individual responsibility and market‑driven solutions. The administration’s approach sought to modernize retirement policy in response to demographic and economic changes, even as it sparked debate about the best way to ensure financial security for future retirees.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
[By Ann Miller RN MHA]
http://www.CertifiedMedicalPlanner.org
Dear Physician Focused Financial Advisors
Did you know that desperate doctors of all ages are turning to knowledgeable financial advisors and medical management consultants for help? Symbiotically too, generalist advisors are finding that the mutual need for knowledge and extreme niche synergy is obvious.
***

***
But, there was no established curriculum or educational program; no corpus of knowledge or codifying terms-of-art; no academic gravitas or fiduciary accountability; and certainly no identifying professional designation that demonstrated integrated subject matter expertise for the increasingly unique healthcare focused financial advisory niche … Until Now!
***

“The informed voice of a new generation of fiduciary advisors for healthcare”

http://e.infogr.am/enter_the_certified_medical_planner?src=embed
***
So, if you are looking to supplement your knowledge, income and designations; and find other qualified professionals you may want to consider the CMP® program.
Enter the Certified Medical Planner™ charter professional designation. And, CMPs™ are FIDUCIARIES, 24/7.
Channel Surfing the ME-P
Have you visited our other topic channels? Established to facilitate idea exchange and link our community together, the value of these topics is dependent upon your input. Please take a minute to visit. And, to prevent that annoying spam, we ask that you register. It is fast, free and secure.
Conclusion
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
***

***
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
* 8
Filed under: "Advisors Only", "Ask-an-Advisor", Career Development, CMP Program, Investing, Touring with Marcinko | Tagged: certified medical planner, CMP, CMP™ Course, financial advisors, financial planners, Marcinko | Leave a comment »
***
***
US consumer confidence fell to its lowest level since 2014
The consumers…they’re not confident.
The Conference Board’s gauge of how optimistic Americans feel about the economy dropped to 84.5—the lowest in over a decade and below economists’ expectations. Respondents frequently cited the costs of gas and groceries, while mentions of politics, the labor market, and health insurance increased since the last reading, the Conference Board said. Experts project that the labor market will stay stagnant in 2026, Bloomberg reported.
COMMENTS APPRECIATED
***
Filed under: iMBA, Inc. | Leave a comment »
By Dr. David Edward Marcinko MBA MEd
***
***
SPONSOR: http://www.MarcinkoAssociates.com
A growing number of surveys measure physician compensation, encompassing a varying depth of analysis. Physician compensation data, divided by specialty and subspecialty, is central to a range of consulting activities including practice assessments and valuations of healthcare enterprises. The AMA maintains the most comprehensive database of information on physicians in the U.S., with information on over 940,000 physicians and residents, and 77,000 medical students. Started in 1906, the AMA “Physician Masterfile,” which contains information on physician education, training, and professional certification information, is updated annually through the Physicians’ Professional Activities questionnaire and the collection and validation efforts of AMA’s Division of Survey and Data Resources (SDR). A selection of other sources of healthcare related compensation and cost data is set forth below.
“Physician Socioeconomic Statistics”, published from 2000 to 2003, was a result of the merger between two prior AMA annuals: (1) “Socioeconomic Characteristics of Medical Practice”; and, (2) “Physician Marketplace Statistics.” Data has compiled from a random sampling of physicians from the Physician Masterfile into what is known as the Socioeconomic Monitoring System, which includes physician age profiles, practice statistics, utilization, physician fees, professional expenses, physician compensation, revenue distribution by payor, and managed care contracts, among other categories.
The Medical Group Management Association’s (MGMA) “Physician Compensation and Production Survey” is one of the largest in the U.S. with approximately 3,000 group practices responding as of the 2023 edition publication. Data is provided on compensation and production for 125 specialties. The survey data are also published on CD by John Wiley & Sons ValueSource; the additional details available in this media provide better bench marking capabilities.
The MGMA’s “Cost Survey” is one of the best known surveys of group practice income and expense data, having been published in some form since 1955, and obtaining over 1,600 respondents, combined, for the 2008 surveys: “Cost Survey for Single Specialty Practices” and “Cost Survey for Multispecialty Practices.” Data is provided for a detailed listing of expense categories and is also calculated as a percentage of revenue and per FTE physician, FTE provider, patient, square foot, and Relative Value Unit (RVU). The survey provides information on multispecialty practices by performance ranking, geographic region, legal organization, size of practice, and percent of capitated revenue. Detailed income and expense data is provided for single specialty practice in over 50 different specialties and subspecialties.
The “Medical Group Financial Operations Survey” was created through a partnership between RSM McGladrey and the American Medical Group Association (AMGA), and provides benchmark data on support staff and physician salaries, physician salaries, staffing profiles and benefits, and other financial indicators. Data is reported as a percent of managed care revenues, per full-time physician, and per square foot, and is subdivided by specialty mix, capitation level, and geographic region with detailed summaries of single specialty practices in several specialties.
“Statistics: Medical and Dental Income and Expense Averages” is an annual survey produced by the National Society of Certified Healthcare Business Consultants (NSCHBC), formerly known as the National Association of Healthcare Consultants (NAHC), and the Academy of Dental CPAs. It has been published annually for a number of years and the “2023 Report Based on 2022 Data” included detailed income and expense data from over 2,700 practices and 4,900 physicians in 62 specialties.
***
***
Medical Specialty Trends
The characteristics of both the practice and the profitability of different physician specialties vary greatly. Information on trends affecting specific specialties should further refine the types of industry information gathered including changes in treatment, technology, competition, reimbursement, and the regulatory environment. For many of the subspecialties, oversupply and under supply issues and the corresponding demand and compensation trends are central to the analysis of potential future earnings and the value of established medical entities. Information that is available and that may be gathered can range from broad practice overviews to, for example, specific procedural utilization demand and forecasts for a precise local geographic area.
A large number of national and state medical associations and organizations gather and produce information on these various aspects of the practice of different individual physician specialties and subspecialties. Information may be found in trade press articles, medical specialty associations and their publications, national surveys, specialty accreditation bodies, governmental reports and studies, and elsewhere. The American Medical Association’s (AMA) as well as the MGMA both publish comprehensive physician practice survey information.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
***
***
Filed under: "Doctors Only", Accounting, Ask a Doctor, curated experts,, Funding Basics, Health Economics, Healthcare Finance, Marcinko Associates | Tagged: AMA, american medical association, Art, books, Cost Survey for Multispecialty Practices, david marcinko, Division of Survey and Data Resources, DO, doctor, doctor compensation data sources, doctor salary, DPM, lifestyle, MD, MGMA, National Society of Certified Healthcare Business Consultants, physician compensation, physician compensation data soures, physician salary, relative value uniuts, RVUs, travel | Leave a comment »
SPONSOR: http://www.MarcinkoAssociates.com
Dr. David Edward Marcinko; MBA MEd
DEFINITIONS
***
***
International diversification occupies a central position in contemporary financial and strategic management discourse, reflecting the realities of an increasingly integrated global economy. At its essence, international diversification refers to the deliberate allocation of investments or business activities across multiple national markets rather than concentrating them within a single domestic environment. Although the concept appears straightforward, its implications are multifaceted, influencing portfolio construction, corporate expansion, and the broader dynamics of global economic interaction. A more formal examination of this strategy illustrates why it has become indispensable for investors and firms seeking stability, growth, and long‑term competitiveness.
For investors, the primary rationale for international diversification lies in its capacity to mitigate risk. Financial markets across countries rarely move in perfect synchrony. Economic cycles differ, political conditions vary, and sectoral strengths are distributed unevenly across regions. By holding assets in multiple countries, investors reduce their exposure to localized downturns. A recession in one economy may coincide with expansion in another, and fluctuations in currency values can either offset or enhance returns. This interplay of global forces creates a more balanced and resilient portfolio than one confined to a single national market.
In addition to risk reduction, international diversification expands the opportunity set available to investors. No single country dominates all industries or innovation pathways. Some economies lead in advanced technology, others in manufacturing, natural resources, or consumer markets. Emerging economies, in particular, offer prospects for rapid growth as their infrastructures develop and their middle classes expand. By extending their reach beyond domestic borders, investors gain access to a broader array of firms, sectors, and long‑term structural trends. This expanded scope can enhance return potential and provide exposure to global developments that may be absent or underrepresented in a home market.
For firms, international diversification carries strategic significance that extends beyond financial considerations. Companies expand abroad to access new customer bases, secure raw materials, reduce production costs, or tap into specialized labor markets. Operating in multiple countries reduces dependence on a single regulatory or economic environment, thereby enhancing organizational resilience. A firm with a diversified international presence can reallocate resources, adjust supply chains, or modify pricing strategies in response to regional shifts. This flexibility strengthens long‑term stability and supports sustained competitive advantage.
Nevertheless, international diversification presents notable challenges. Investors must navigate unfamiliar regulatory frameworks, political uncertainties, and currency risks. A country may offer attractive growth prospects yet lack the institutional transparency or legal protections that investors expect. Firms face comparable complexities. Expanding into foreign markets requires sensitivity to cultural differences, adaptation of products or services to local preferences, and effective management of logistical and operational hurdles. Failure to address these factors can diminish the anticipated benefits of diversification.
***
***
Despite these obstacles, the long‑term advantages of international diversification often outweigh its difficulties. Advances in technology, reductions in trade barriers, and the increasing availability of global financial information have lowered many of the practical barriers that once hindered cross‑border investment and expansion. Real‑time data, digital communication, and integrated supply chains enable both investors and firms to operate globally with greater efficiency and confidence.
International diversification also contributes to innovation and competitiveness. Exposure to global markets encourages firms to adopt best practices, learn from international competitors, and respond to diverse consumer demands. This exchange of ideas fosters innovation and strengthens organizational adaptability. Investors similarly benefit from access to global innovation cycles, gaining exposure to industries and technologies that may be less developed in their domestic markets.
Finally, international diversification supports broader economic stability. When capital and business activity are distributed across regions, localized shocks are less likely to trigger systemic disruptions. Although global interconnectedness can transmit risks, it also creates buffers that help absorb economic volatility. A diversified global financial system is better positioned to sustain long‑term growth and withstand regional disturbances.
In sum, international diversification reflects a fundamental recognition that no single market encompasses all opportunities or risks. For both investors seeking balanced returns and firms pursuing strategic growth, engagement with global markets offers a wider array of possibilities and a more resilient foundation for long‑term success.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
SPONSOR: http://www.MarcinkoAssociates.com
Dr. David Edward Marcinko; MBA MEd
***
***
Broker–dealer markets occupy a central position in modern financial systems, acting as the connective tissue between investors, issuers, and the broader marketplace. These markets are defined by the activities of broker–dealers—financial intermediaries who facilitate the buying and selling of securities either on behalf of clients or for their own accounts. Their dual capacity as both agents and principals creates a dynamic environment that blends service provision, risk‑taking, and market‑making. Understanding how broker–dealer markets operate provides insight into the mechanisms that support liquidity, price discovery, and overall market efficiency.
At the core of broker–dealer markets is the distinction between brokerage and dealing functions. When acting as brokers, these intermediaries execute trades for clients and earn commissions for matching buyers and sellers. Their role is primarily that of a facilitator, ensuring that client orders are executed at the best available prices. In contrast, when acting as dealers, they trade for their own accounts, buying and selling securities with the intention of profiting from price movements or spreads. This principal role requires them to commit capital, assume risk, and maintain inventories of securities. The ability to switch between these roles allows broker–dealers to respond flexibly to market conditions and client needs.
One of the most important contributions of broker–dealer markets is the provision of liquidity. Liquidity refers to the ease with which assets can be bought or sold without causing significant price changes. Dealers enhance liquidity by standing ready to buy or sell securities at publicly quoted prices, even when natural buyers or sellers are not immediately available. This willingness to transact helps stabilize markets, reduces volatility, and ensures that investors can enter or exit positions efficiently. In times of market stress, the presence of committed dealers can prevent disorderly trading and maintain orderly market functioning.
Price discovery is another critical function supported by broker–dealer markets. Through continuous trading, quoting, and negotiation, broker–dealers help establish fair market values for securities. Their quotes reflect both supply‑and‑demand conditions and their own assessments of risk and expected returns. Because dealers often have access to extensive market information, order flow, and analytical tools, their pricing decisions contribute significantly to the informational efficiency of markets. Investors rely on these prices as signals for making informed decisions, and issuers depend on them to gauge market sentiment and capital‑raising conditions.
The structure of broker–dealer markets varies across asset classes and jurisdictions, but certain common features define their operation. Many broker–dealer markets are decentralized, meaning that trading does not occur on a single centralized exchange but rather through networks of dealers who negotiate directly with one another or with clients. This over‑the‑counter (OTC) structure is prevalent in markets for corporate bonds, derivatives, and certain equities. In such environments, relationships, reputation, and negotiation skills play a significant role in determining execution quality. Dealers often specialize in particular sectors or instruments, allowing them to develop expertise and maintain inventories tailored to client demand.
Regulation plays a substantial role in shaping broker–dealer markets. Because broker–dealers handle client assets, provide investment recommendations, and influence market prices, they are subject to oversight designed to protect investors and ensure fair dealing. Regulatory frameworks typically require broker–dealers to maintain adequate capital, manage conflicts of interest, and adhere to standards of conduct. These rules aim to balance the need for market efficiency with the imperative of investor protection. While regulation can impose costs and constraints, it also enhances trust in the financial system, which is essential for market participation.
Technological innovation has transformed broker–dealer markets in recent decades. Electronic trading platforms, algorithmic execution, and real‑time data analytics have reshaped how dealers operate and interact with clients. Automation has reduced transaction costs, increased transparency, and accelerated trade execution. At the same time, it has introduced new challenges, such as managing the risks associated with high‑frequency trading and ensuring that automated systems behave predictably under stress. Broker–dealers have adapted by investing in technology, developing sophisticated risk‑management systems, and refining their market‑making strategies.
Competition within broker–dealer markets has also intensified. Traditional dealers now compete with electronic market makers, alternative trading systems, and other non‑traditional liquidity providers. This competition has narrowed spreads and improved execution quality for many investors. However, it has also pressured traditional dealers to evolve their business models, focusing more on value‑added services such as research, advisory work, and customized trading solutions. The interplay between traditional and electronic participants continues to shape the evolution of these markets.
Despite these changes, the fundamental importance of broker–dealer markets remains unchanged. They continue to serve as vital intermediaries that connect capital seekers with capital providers, facilitate investment activity, and support the functioning of the broader economy. Their ability to provide liquidity, enable price discovery, and manage risk makes them indispensable to financial stability and growth.
In summary, broker–dealer markets represent a complex and dynamic component of the financial landscape. Through their dual roles as brokers and dealers, these intermediaries support efficient trading, enhance liquidity, and contribute to accurate pricing. Their operations are influenced by regulatory frameworks, technological advancements, and competitive pressures, all of which shape their evolving role in global finance. As markets continue to develop, broker–dealers will remain central to the mechanisms that allow financial systems to function smoothly and effectively.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Staff Reporters
SPONSOR: http://www.MarcinkoAssociates.com
***
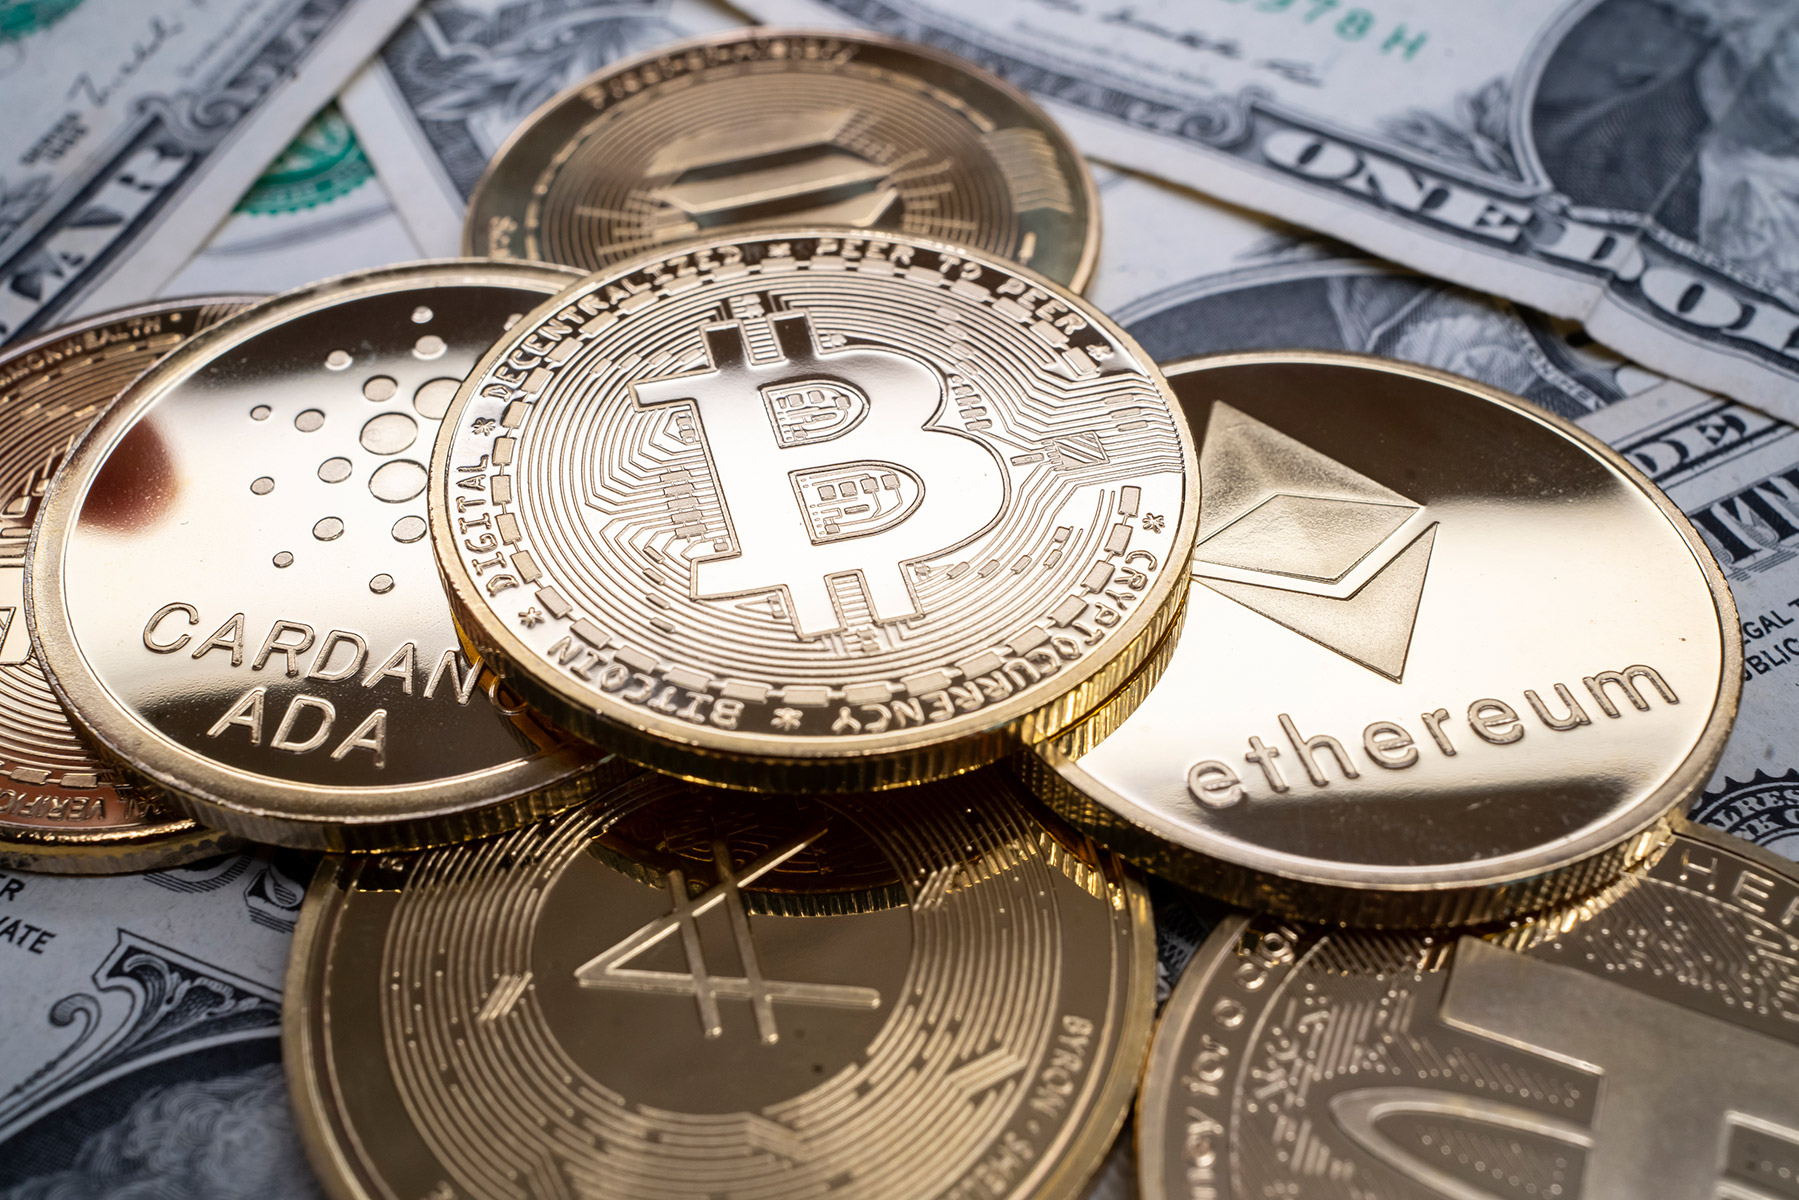
***
Cryptocurrency has evolved from a niche technological experiment into a global financial force. In just over a decade, it has disrupted traditional banking, inspired new economic models, and sparked debates about the future of money. As of 2025, cryptocurrencies are not only investment assets but also tools for innovation, decentralization, and financial inclusion. This essay explores the origins of cryptocurrency, its evolution, and its current status in the global economy.
Before Bitcoin, digital currency was a theoretical concept explored by cryptographers and computer scientists. In the 1980s, David Chaum introduced DigiCash, an early form of electronic money that prioritized privacy. Though innovative, DigiCash failed commercially due to lack of adoption and centralization.
Other attempts, like Hashcash and B-money, laid the groundwork for decentralized systems but never materialized into functioning currencies. These efforts, however, contributed key ideas that would later be incorporated into Bitcoin.
REAL MONEY: https://medicalexecutivepost.com/2025/03/27/cryptocurrency-real-money-or-not/
In 2008, an anonymous figure (or group) known as Satoshi Nakamoto published the Bitcoin white paper: “Bitcoin: A Peer-to-Peer Electronic Cash System.” This document proposed a decentralized currency that used blockchain technology to validate transactions without a central authority.
Bitcoin officially launched in January 2009 with the mining of the genesis block. Early adopters were cryptographers, libertarians, and tech enthusiasts. The first real-world Bitcoin transaction occurred in 2010 when Laszlo Hanyecz paid 10,000 BTC for two pizzas — now commemorated as Bitcoin Pizza Day.
Bitcoin’s design solved the double-spending problem and introduced a transparent, immutable ledger. Its supply was capped at 21 million coins, making it deflationary by design.
Bitcoin’s success inspired the creation of alternative cryptocurrencies, or “altcoins.” Litecoin (2011), Ripple (2012), and Ethereum (2015) introduced new functionalities. Ethereum, in particular, revolutionized the space by enabling smart contracts — self-executing agreements coded directly onto the blockchain.
Smart contracts laid the foundation for decentralized applications (dApps), decentralized finance (DeFi), and non-fungible tokens (NFTs). These innovations expanded crypto’s use cases beyond simple transactions.
In 2017, the crypto market experienced a massive bull run fueled by initial coin offerings (ICOs). Startups raised billions by issuing tokens, often without clear business models or regulatory oversight. While some projects succeeded, many failed or turned out to be scams.
Governments responded with crackdowns. The U.S. Securities and Exchange Commission (SEC) began classifying certain tokens as securities, requiring registration and compliance. China banned ICOs and crypto exchanges altogether.
Despite the volatility, the 2017–2018 cycle cemented crypto’s place in mainstream finance and attracted institutional interest.
The COVID-19 pandemic in 2020 accelerated crypto adoption. As governments printed trillions in stimulus, concerns about inflation grew. Bitcoin was increasingly viewed as “digital gold” — a hedge against fiat currency devaluation.
Major companies like Tesla, MicroStrategy, and Square added Bitcoin to their balance sheets. PayPal and Visa began supporting crypto transactions. The narrative shifted from speculation to legitimacy.
Ethereum’s ecosystem exploded with the rise of DeFi platforms like Uniswap, Aave, and Compound. These services allowed users to lend, borrow, and trade assets without intermediaries. Total value locked (TVL) in DeFi surpassed $100 billion by 2021.
Ethereum also became the backbone of the NFT boom. Artists, musicians, and creators used NFTs to monetize digital content, leading to record-breaking sales and mainstream attention.
STABLE COINS: https://medicalexecutivepost.com/2023/08/11/paypal-crypto-stablecoin-pyusd/
As of 2025, the global cryptocurrency market has added over $600 billion in value year-to-date, with a total market capitalization exceeding $2.5 trillion.
CRYPTO INFLATION: https://medicalexecutivepost.com/2022/08/27/inflation-and-crypto-currency/
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: "Ask-an-Advisor", Alternative Investments, Financial Advisor Listings, Glossary Terms, Marcinko Associates | Tagged: Aave, altcoins, B-money, Bitcoin, blockchain, crypto, crypto-currency, cryptocurrency, DeFi, DigiCash, digital gold, Etherium, Hashcash, ICO boom, Laszlo Hanyecz, Litecoin, Marcinko, MicroStrategy, NFT, Satoshi Nakamoto, Tesla, Uniswap | Leave a comment »
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.CertifiedMedicalPlanner.org
***
***
Bond market indicators form one of the most revealing windows into the health, expectations, and underlying tensions of an economy. While stock markets often capture headlines with their volatility and spectacle, the bond market quietly reflects deeper structural forces—growth prospects, inflation expectations, credit risk, and investor sentiment. Understanding these indicators allows analysts, policymakers, and investors to interpret economic signals that are often more reliable and forward‑looking than equity prices. A well‑rounded view of the bond market requires examining several key measures, each offering a distinct perspective on economic conditions.
One of the most widely discussed indicators is the yield curve, which plots the interest rates of government bonds across different maturities. Under normal conditions, longer‑term bonds carry higher yields than short‑term ones, compensating investors for the risk of time. When the yield curve steepens, it often signals optimism about future growth and inflation. Conversely, a flattening or inverted yield curve—where short‑term yields exceed long‑term yields—suggests that investors expect slower growth or even recession. Historically, yield curve inversions have preceded economic downturns with notable consistency, making this indicator a central focus for economists and financial professionals.
Another essential indicator is the level of interest rates themselves, particularly yields on benchmark government securities such as U.S. Treasury bonds. These yields reflect a combination of monetary policy, inflation expectations, and global demand for safe assets. Rising yields typically indicate expectations of stronger economic activity or higher inflation, while falling yields often point to risk aversion or weakening growth prospects. Because government bond yields influence borrowing costs across the economy—from mortgages to corporate loans—they serve as a foundational reference point for financial conditions.
Closely related is the term premium, which represents the extra compensation investors demand for holding long‑term bonds instead of rolling over short‑term ones. When the term premium is high, it suggests uncertainty about future inflation or interest rates. A low or negative term premium, on the other hand, can reflect strong demand for long‑term safe assets, often driven by global savings patterns or central bank interventions. Shifts in the term premium can significantly affect the shape of the yield curve and the interpretation of other indicators.
Credit‑related indicators also play a crucial role. Credit spreads, which measure the difference in yields between corporate bonds and comparable government bonds, reveal how investors perceive the risk of default. Narrow spreads indicate confidence in corporate balance sheets and economic stability, while widening spreads signal rising concern about credit risk. High‑yield, or “junk,” bond spreads are especially sensitive to shifts in risk appetite and can act as early warnings of financial stress.
Another valuable measure is bond market liquidity, which reflects how easily securities can be bought or sold without affecting prices. Healthy liquidity supports stable markets and efficient price discovery. When liquidity deteriorates—often during periods of uncertainty or market stress—price swings become more pronounced, and borrowing costs can rise abruptly. Monitoring liquidity conditions helps analysts assess the resilience of the financial system.
Inflation‑linked bonds provide additional insight. The difference between yields on nominal government bonds and inflation‑protected securities reveals the market’s breakeven inflation rate, a widely watched gauge of expected inflation. Because inflation erodes the real value of fixed payments, these expectations directly influence bond pricing and monetary policy decisions.
Taken together, these indicators form a comprehensive toolkit for interpreting economic and financial conditions. The bond market’s depth and sensitivity to macroeconomic forces make it an indispensable source of information. While no single indicator tells the whole story, understanding how they interact allows for a more nuanced and forward‑looking assessment of the economy.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Staff Reporters
***
***
In epistemology, the Münchhausen trilemma is a thought experiment intended to demonstrate the theoretical impossibility of proving any truth, even in the fields of logic and mathematics, without appealing to accepted assumptions. If it is asked how any given proposition is known to be true, proof in support of that proposition may be provided. Yet that same question can be asked of that supporting proof and any subsequent supporting proof. The Münchhausen trilemma is that there are only three ways of completing a proof:
The trilemma, then, is having to choose one of three equally unsatisfying options.
COMMENTS APPRECIATED
Like and Subscribe
***
***
Filed under: iMBA, Inc. | Leave a comment »
***
***
By Dr. David Edward Marcinko MBA MEd
***
Milton Friedman was a towering figure in the field of economics, renowned for his unwavering advocacy of free-market capitalism and limited government intervention. Born in 1912 in New York City and raised in Rahway, New Jersey, Friedman rose from modest beginnings to become a Nobel laureate and a leading voice of the Chicago School of Economics.
Friedman’s academic journey began at Rutgers University, where he earned a degree in mathematics and economics. He later pursued graduate studies at the University of Chicago and Columbia University, where he was mentored by prominent economists like Simon Kuznets. His intellectual foundation laid the groundwork for a career that would challenge prevailing economic thought and reshape public policy.
One of Friedman’s most significant contributions was his development of monetarism, a theory emphasizing the role of governments in controlling the money supply to manage inflation and economic stability. In contrast to Keynesian economics, which advocated for active fiscal policy and government spending, Friedman argued that excessive government intervention often led to inefficiencies and inflation. His research demonstrated that inflation is “always and everywhere a monetary phenomenon,” a principle that became central to modern macroeconomic policy.
Friedman’s influence extended beyond academia. His 1962 book, Capitalism and Freedom, articulated a powerful case for economic liberty as a foundation for political freedom. He argued that voluntary exchange and competitive markets were essential for individual choice and prosperity. The book also introduced the Friedman Doctrine, which posited that the primary responsibility of business is to increase its profits, a view that sparked ongoing debates about corporate social responsibility.
In 1976, Friedman was awarded the Nobel Memorial Prize in Economic Sciences for his work on consumption analysis, monetary history, and stabilization policy. His Permanent Income Hypothesis, which suggests that people base their consumption on expected long-term income rather than current income, revolutionized understanding of consumer behavior.
Friedman’s ideas had profound policy implications. He was a vocal critic of the draft and successfully advocated for an all-volunteer military. He also proposed the concept of school vouchers, allowing parents to choose schools for their children, which laid the foundation for modern school choice movements. His work influenced leaders like Ronald Reagan and Margaret Thatcher, who embraced free-market reforms during their administrations.
Despite his acclaim, Friedman’s views were not without controversy. Critics argued that his emphasis on deregulation and privatization sometimes overlooked social equity and environmental concerns. Nonetheless, his legacy remains deeply embedded in economic thought and public discourse.
Milton Friedman passed away in 2006, but his ideas continue to shape debates on economic policy, freedom, and the role of government. His belief in the power of markets and individual choice remains a cornerstone of classical liberalism and a guiding light for economists and policymakers around the world.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: "Advisors Only", "Ask-an-Advisor", CMP Program, curated experts,, economics, Financial Planning, Funding Basics, Health Economics, Marcinko Associates, Portfolio Management | Tagged: Booz Allen Hamilton, economics, Free Markets, friedman doctrine, Keynes, Keynesian, Marcinko, Milton Friedman, monetarism, Permanent Income Hypothesis, politics, school vouchers, simon kuznets | Leave a comment »
***
A paradox is a logically self-contradictory statement or a statement that runs contrary to one’s expectation. It is a statement that, despite apparently valid reasoning from true or apparently true premises, leads to a seemingly self-contradictory or a logically unacceptable conclusion. A paradox usually involves contradictory-yet-interrelated elements that exist simultaneously and persist over time. They result in “persistent contradiction between interdependent elements” leading to a lasting “unity of opposites”.
Classic Definition: Artificial intelligence (AI) refers to computer systems capable of performing complex tasks that historically only a human could do, such as reasoning, making decisions, or solving problems. The term “AI” describes a wide range of technologies that power many of the services and goods we use every day – from apps that recommend TV shows to chat-bots that provide customer support in real time.
Modern Circumstance: The role of artificial intelligence in health care is becoming an increasingly topical and controversial discussion. There remains uncertainty about what is achievable regarding ongoing medical artificial intelligence research. Although there are some people who believe that artificial intelligence will be used, at best, as a tool to assist clinicians in their day-to-day activities, there are others who believe that job automation and replacement is a looming threat.
***
Paradox Example: Moravec’s paradox is a phenomenon observed by robotics researcher Hans Moravec, in which tasks that are easy for humans to perform (eg, motor or social skills) are difficult for machines to replicate, whereas tasks that are difficult for humans (eg, performing mathematical calculations or large-scale data analysis) are relatively easy for machines to accomplish.
***
***
For example, a computer-aided diagnostic system might be able to analyze large volumes of images quickly and accurately but might struggle to recognize clinical context or technical limitations that a human radiologist would easily identify.
Similarly, a machine learning algorithm might be able to predict a patient’s risk of a specific condition on the basis of their medical history and laboratory results but might not be able to account for the nuances of the patient’s individual case or consider the effect of social and environmental factors that a human physician would consider.
In surgery, there has been great progress in the field of robotics in health care when robotic elements are controlled by humans, but artificial intelligence-driven robotic technology has been much slower to develop.Thus far, research into clinical artificial intelligence has focused on improving diagnosis and predictive medicine.
Assessment
Moravec’s paradox also highlights the importance of maintaining a human element in the health-care system, and the need for collaboration between humans and technology to achieve the best possible outcomes.
Conclusion
In the field of medicine, it is becoming indisputable that artificial intelligence will have a role in population health analysis, predictive medicine, and personalized care.
However, for now, the job of doctors seems safe from automation.
Cite: Shuaib A: The increasing role of artificial intelligence in health care: will robots replace doctors in the future? Int J Gen Med. 2020; 13: 891-896
COMMENTS APPRECIATED
Like and Subscribe
***
***
***
Filed under: Ask a Doctor, Glossary Terms, Health Economics, Health Insurance, Health Law & Policy, Healthcare Finance, iMBA, Inc., Information Technology, Marcinko Associates, mental health | Tagged: AI, artificial intelligence, david marcinko, Hans Moravec, health, healthcare, mental health, Morovec's paradox, paradox, Technology | Leave a comment »
DEFINITION
Staff Reporters
SPONSOR: http://www.MarcinkoAssociates.com
***
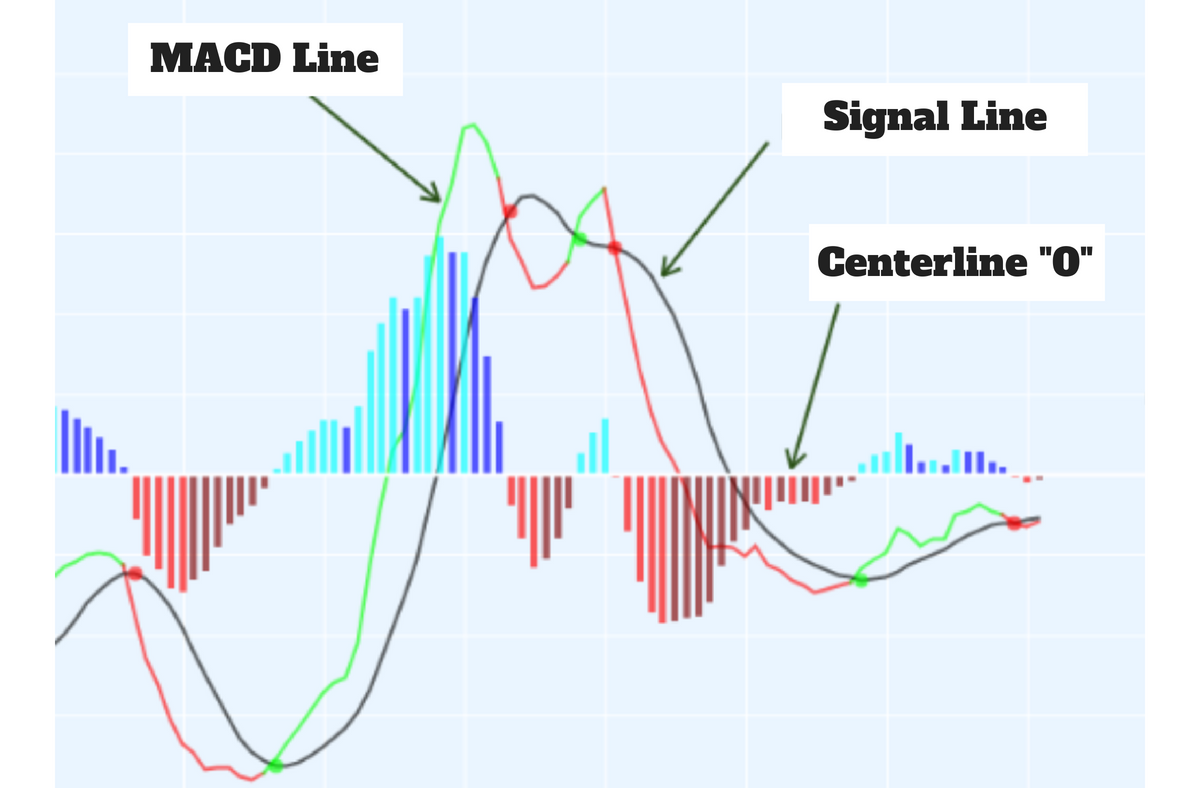
***
From Wikipedia, the free encyclopedia
***

***
MACD, short for moving average convergence/divergence, is a trading indicator used in technical analysis of securities prices, created by Gerald Appel in the late 1970s. It is designed to reveal changes in the strength, direction, momentum, and duration of a trend in a stock’s price.
The MACD indicator (or “oscillator”) is a collection of three time series calculated from historical price data, most often the closing price. These three series are: the MACD series proper, the “signal” or “average” series, and the “divergence” series which is the difference between the two. The MACD series is the difference between a “fast” (short period) exponential moving average (EMA), and a “slow” (longer period) EMA of the price series. The average series is an EMA of the MACD series itself.
The MACD indicator thus depends on three time parameters, namely the time constants of the three EMAs. The notation “MACD(a,b,c)” usually denotes the indicator where the MACD series is the difference of EMAs with characteristic times a and b, and the average series is an EMA of the MACD series with characteristic time c. These parameters are usually measured in days. The most commonly used values are 12, 26, and 9 days, that is, MACD (12,26,9). As true with most of the technical indicators, MACD also finds its period settings from the old days when technical analysis used to be mainly based on the daily charts. The reason was the lack of the modern trading platforms which show the changing prices every moment. As the working week used to be 6-days, the period settings of (12, 26, 9) represent 2 weeks, 1 month and one and a half week. Now when the trading weeks have only 5 days, possibilities of changing the period settings cannot be overruled. However, it is always better to stick to the period settings which are used by the majority of traders as the buying and selling decisions based on the standard settings further push the prices in that direction.
Although the MACD and average series are discrete values in nature, but they are customarily displayed as continuous lines in a plot whose horizontal axis is time, whereas the divergence is shown as a bar chart (often called a histogram).
***

A fast EMA responds more quickly than a slow EMA to recent changes in a stock’s price. By comparing EMAs of different periods, the MACD series can indicate changes in the trend of a stock. It is claimed that the divergence series can reveal subtle shifts in the stock’s trend.
Since the MACD is based on moving averages, it is a lagging indicator. As a future metric of price trends, the MACD is less useful for stocks that are not trending (trading in a range) or are trading with unpredictable price action. Hence the trends will already be completed or almost done by the time MACD shows the trend.
COMMENTS APPRECIATED
Like, Subscribe and Refer
***
***
Filed under: "Ask-an-Advisor", curated experts,, finance, Financial Planning, Funding Basics, Glossary Terms, Investing | Tagged: EMA, finance, Investing, lagging indicator, MACD, Moving Average Convergence/Divergence, stock market, Technical analysis, trading | Leave a comment »
By Artificial Intelligence
***
***
Quantum mechanics is a fundamental branch of physics that explores the behavior of matter and energy at the smallest scales—typically atomic and subatomic levels. Unlike classical physics, which deals with predictable and continuous phenomena, quantum mechanics reveals a world governed by probabilities, uncertainties, and strange dualities. It challenges our intuitive understanding of reality and has revolutionized both science and technology.
The origins of quantum mechanics trace back to the early 20th century, when classical theories failed to explain certain experimental results. Max Planck’s work on black-body radiation in 1900 introduced the idea that energy is quantized, meaning it comes in discrete packets called “quanta.” This concept laid the foundation for quantum theory. Soon after, Albert Einstein explained the photoelectric effect by proposing that light itself is made of particles—later called photons—further reinforcing the idea of quantization.
One of the most striking features of quantum mechanics is wave-particle duality. According to this principle, particles such as electrons and photons exhibit both wave-like and particle-like behavior depending on how they are observed. This duality was famously demonstrated in the double-slit experiment, where particles create an interference pattern typical of waves when not observed, but behave like particles when measured.
Another cornerstone of quantum mechanics is Heisenberg’s uncertainty principle, which states that certain pairs of physical properties—like position and momentum—cannot both be known precisely at the same time. This introduces a fundamental limit to measurement and implies that the act of observing a system can alter its state.
Quantum mechanics also introduces the concept of superposition, where particles can exist in multiple states simultaneously until measured. This idea is illustrated by Schrödinger’s cat thought experiment, in which a cat in a sealed box is both alive and dead until the box is opened and the cat is observed. Though metaphorical, this paradox highlights the non-intuitive nature of quantum systems.
Perhaps the most mysterious phenomenon in quantum mechanics is entanglement. When particles become entangled, their states are linked regardless of the distance between them. A change in one particle instantly affects the other, defying classical notions of locality. This “spooky action at a distance,” as Einstein called it, has been experimentally confirmed and is the basis for emerging technologies like quantum cryptography and quantum teleportation.
Quantum mechanics is not just theoretical—it has practical applications that shape our modern world. Technologies such as lasers, semiconductors, MRI machines, and atomic clocks all rely on quantum principles. Moreover, quantum computing promises to revolutionize information processing by using quantum bits (qubits) that can represent multiple states simultaneously, enabling calculations far beyond the reach of classical computers.
In conclusion, quantum mechanics is a profound and essential framework for understanding the universe at its most fundamental level. It challenges our perceptions, fuels technological innovation, and continues to inspire scientists and philosophers alike. As research advances, quantum mechanics may unlock even deeper mysteries of reality, reshaping our understanding of existence itself.
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: Ask a Doctor, Ethics, Experts Invited | Tagged: AI, albert einstein, entanglements, Erwin Schrodinger, Max Planc, microscopic universe, philosophy, physics, quantum mechanics, quantum-physics, qubits, Science, superposition, Werner Heisenberg | Leave a comment »
By Staff Reporters.
***
***
A fake job or ghost job is a scam job posting for a non-existent or already filled position. A scam is a dishonest scheme to gain money or possessions from someone fraudulently, especially a complex or prolonged one.
Due to current economic conditions in 2025, there’s been a rise in scams related to job postings and financial relief offers, preying on people’s financial insecurities. Keep your wits about you and be wary of potential fraud in seemingly legitimate opportunities.
For example, an employer may post fake job opening listings for many reasons such as inflating statistics about their industries, protecting the company from discrimination lawsuits, fulfilling requirements by human-resources departments, identifying potentially promising recruits for future hiring, pacifying existing employees that the company is looking for extra help, or retaining desirable employees. They may also use this strategy to gather information regarding their competitors’ wages. And, there is a rising trend in employers promising remote work as “bait,” and it underscores the relative power of the employers in the job market.
GHOST NURSING: The 1982 Movie
A young woman nanny plagued with bad luck travels to Thailand to visit a friend. There, her friend suggests a visit to a sorcerer, which results in her adopting a child ghost/demon who begins to protect her, but matters soon go awry.
Impact on the Healthcare Field
This is not a 44 year old science-fiction movie. Medicine and the healthcare industry isn’t immune to the ghost job phantom trend. Some contingent labor or medical staffing agencies lack ethics and post jobs solely to bolster their database, without any intention of filling those roles. This deceptive practice misleads job seekers and wastes their time, further eroding trust in the hiring process.
If you are a nanny or caregiver, you may have your services listed on an online job site. While this is a great way to find work, it can also open you to ghost scams. One phone scam is to send you an offer of employment. The “employer” sends you a check, and asks you to send them some money to buy assistive care items needed for the job. However, the person you are talking to isn’t really interested in you. After you’ve sent the money, the check will bounce and the “employer” will ghost you and disappear. Not only do you not really have a job, you just sent money to a ghost scammer and will not be reimbursed.
Impact on the Finance Field
In finance, ghost jobs can appear for various reasons, such as companies wanting to gauge the labor market, fulfill internal posting policies, or maintain a pool of potential candidates. Consulting roles, including those in financial planning, have seen an increase in ghost jobs, with some firms keeping listings open despite slowing hiring activity. The IRS will never ghost call, but your bank might, which makes it harder to figure out if it’s the real deal; or a ghost scam. Plus, it makes sense that your bank would need to confirm your identity to protect your account. If your bank calls and asks you to confirm if transactions are legitimate, feel free to give a yes or no. But don’t give up any more information than that, says Adam Levin, founder of global identity protection and data risk services firm CyberScout and author of Swiped: How to Protect Yourself in a World Full of Scammers, Phishers, and Identity Thieves. Some scammers rattle off your credit card number and expiration date, then ask you to say your security code as confirmation, he says. Others will claim they froze your credit card because you might be a fraud victim, then ask for your Social Security number.
If someone claiming to be your accountant, insurance agent or financial advisor calls and says you have a computer problem with them, just say no and hang up. No one is ‘watching’ your computer for signs of a virus. And, those scammers won’t fix the problem—they’ll make it worse by installing malware or stealing your account information or even money.
Promoters of cryptocurrency and other investments use complex schemes, often enhanced through deepfake videos or AI-manipulated audio, to lend credibility. According to the FBI’s Internet Crime Complaint Center (IC3), victims reported an estimated $3.9 billion in losses from investment fraud in 2024. Promises of “guaranteed returns” or requests for money transfers via crypto wallets are warning signs.
Many targets lack experience in crypto markets, amplifying risk. Do thorough research, consult official resources (like SEC.gov), and use licensed platforms if investing. Treat “sure thing” tips and unsolicited offers as red flags.
***
The Medical Executive-Post is a news and information aggregator and social media professional network for medical and financial service professionals. Feel free to submit education content to the site as well as links, text posts, images, opinions and videos which are then voted up or down by other members. Comments and dialog are especially welcomed. Daily posts are organized by subject. ME-P administrators moderate the activity. Moderation may also conducted by community-specific moderators who are unpaid volunteers.
COMMENTS APPRECIATED
Like, Subscribe and Refer
***
***
Filed under: "Ask-an-Advisor", Ask a Doctor, Career Development, Ethics, Experts Invited, Financial Planning, Glossary Terms, Investing, LifeStyle | Tagged: accountant, Adam Levin, bank, brokerage, CyberScout, dishonest, fake jobs, FBi, finance, financial advisor, Financial Planning, fraud, ghost jobs, ghost nursing, healthcare, IC3, isurance agent, malware, medicine, phantom jos, phishing, scam, scams, Scheme, SEC, security | Leave a comment »
By Staff Reporters
SPONSOR: http://www.MarcinkoAssociates.com
***
***
Artificial Intelligence (AI) is revolutionizing the banking industry by enhancing efficiency, security, and customer experience. This 500-word essay explores how AI is transforming banking operations and shaping the future of financial services.
Artificial Intelligence (AI) has emerged as a transformative force in the banking sector, reshaping traditional operations and introducing innovative solutions to age-old challenges. As financial institutions strive to remain competitive in a rapidly evolving digital landscape, AI offers tools that enhance efficiency, improve customer service, and bolster security.
One of the most visible applications of AI in banking is customer service automation. AI-powered chatbots and virtual assistants are now commonplace, handling routine inquiries, guiding users through transactions, and offering personalized financial advice. These systems operate 24/7, reducing wait times and freeing human agents to focus on complex issues. For example, banks like Bank of America and JPMorgan Chase have deployed AI-driven assistants that interact with millions of customers daily, providing seamless support and improving satisfaction.
AI also plays a crucial role in fraud detection and risk management. By analyzing vast amounts of transaction data in real time, AI systems can identify unusual patterns and flag potentially fraudulent activities. Machine learning algorithms continuously adapt to new threats, making fraud prevention more proactive and effective. This not only protects customers but also saves banks billions in potential losses.
In the realm of credit scoring and loan approvals, AI has introduced more nuanced and inclusive models. Traditional credit assessments often rely on limited data, excluding individuals with thin credit histories. AI, however, can evaluate alternative data sources—such as utility payments, social media behavior, and employment history—to generate more accurate credit profiles. This enables banks to extend services to underserved populations while minimizing default risks.
Operational efficiency is another area where AI shines. Through process automation, banks can streamline back-office functions like document verification, compliance checks, and data entry. Robotic Process Automation (RPA), powered by AI, reduces human error and accelerates workflows, leading to significant cost savings and improved accuracy.
Moreover, AI enhances personalized banking experiences. By analyzing customer behavior and preferences, AI systems can recommend tailored financial products, investment strategies, and budgeting tools. This level of personalization fosters deeper customer engagement and loyalty.
Despite its benefits, the integration of AI in banking is not without challenges. Data privacy concerns, regulatory compliance, and ethical considerations must be addressed to ensure responsible AI deployment. Banks must invest in robust governance frameworks and transparent algorithms to maintain trust and accountability.
Looking ahead, the role of AI in banking will only expand. Emerging technologies like natural language processing, predictive analytics, and AI-driven cybersecurity will further revolutionize the industry. As banks continue to embrace digital transformation, AI will be at the forefront, driving innovation and redefining the future of finance.
In conclusion, Artificial Intelligence is not just a technological upgrade for banks—it is a strategic imperative. By harnessing AI’s capabilities, financial institutions can deliver smarter, safer, and more customer-centric services, positioning themselves for long-term success in the digital age.
COMMENTS APPRECIATED
SPEAKING: ME-P Editor Dr. David Edward Marcinko MBA MEd will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: "Ask-an-Advisor", Accounting, economics, finance, Insurance Matters, Investing, Marcinko Associates, Portfolio Management | Tagged: AI, artificial intelligence, banking, banking industry, banks, business, data privacy, finance, FOMC, Natural Language Processing, Technology | Leave a comment »
By Staff Reporters
SPONSOR: http://www.CertifiedMedicalPlanner.org
***
***
The economics of information explores how knowledge—or the lack of it—affects decision-making, market behavior, and resource allocation. It reveals why perfect competition rarely exists and why information itself can be a powerful economic asset.
Economics of Information: Understanding the Value and Impact of Knowledge
In traditional economic models, markets are often assumed to operate under perfect information—where all participants have equal access to relevant data. However, in reality, information is often incomplete, asymmetric, or costly to obtain. The field known as economics of information emerged to address these discrepancies, fundamentally reshaping how economists understand markets, incentives, and efficiency.
One of the core concepts in this field is information asymmetry, where one party in a transaction possesses more or better information than the other. This imbalance can lead to adverse selection and moral hazard. For example, in the insurance market, individuals who know they are high-risk are more likely to seek coverage, while insurers may struggle to differentiate between high- and low-risk clients. Similarly, in lending, borrowers may have private knowledge about their ability to repay, which lenders cannot easily verify.
To mitigate these problems, economists have developed mechanisms such as signaling and screening. Signaling occurs when the informed party takes action to reveal their type—like a job applicant earning a degree to signal competence. Screening, on the other hand, involves the uninformed party designing tests or contracts to elicit information—such as offering different insurance packages to separate risk levels.
Another important area is the cost of acquiring information. Gathering data, analyzing trends, or verifying facts requires time and resources. This leads to decisions being made under uncertainty, where individuals rely on heuristics or limited data. The economics of information examines how these costs influence behavior, pricing, and market structure. For instance, consumers may not compare every available product due to search costs, allowing firms to maintain price dispersion.
The rise of digital technology has intensified the relevance of this field. In the age of big data, companies like Google and Amazon thrive by collecting and analyzing vast amounts of user information. This data allows them to personalize services, predict behavior, and gain competitive advantages. However, it also raises concerns about privacy, market power, and inequality—issues that economists of information are increasingly addressing.
Moreover, information goods—such as software, media, and research—have unique economic properties. They are often non-rivalrous and can be reproduced at near-zero marginal cost. This challenges traditional pricing models and calls for innovative approaches like freemium strategies, bundling, and subscription services.
In public policy, the economics of information plays a crucial role in designing regulations, transparency standards, and consumer protections. Governments must balance the need for open access to information with incentives for innovation and investment. For example, patent laws aim to encourage research by granting temporary monopolies, while disclosure requirements in finance promote market integrity.
In conclusion, the economics of information reveals that knowledge is not just a passive input but a dynamic force shaping economic outcomes. By understanding how information is produced, distributed, and used, economists can better explain real-world phenomena and design systems that promote fairness, efficiency, and innovation.
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: "Advisors Only", "Ask-an-Advisor", CMP Program, economics, Health Economics | Tagged: AI, assymetry, CMP, economic value, economics, economics information, economics of knowledge, economy, finance, knowledge, Technology | Leave a comment »
DEFINITIONS
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MarcinkoAssociates.com
***
***
Active portfolio management sits at the center of modern investment practice, offering a dynamic alternative to the more hands‑off, rules‑based approach of passive strategies. At its core, active management is about making informed, deliberate decisions to outperform a benchmark—whether that benchmark is a broad market index, a sector index, or a custom blend of assets. While passive investing has grown rapidly in recent decades, active management remains essential for investors who seek to exploit market inefficiencies, express specific views, or tailor portfolios to unique goals and constraints. Understanding how active management works, why it persists, and what challenges it faces provides a clearer picture of its role in today’s financial landscape.
Active portfolio management begins with a simple premise: markets are not perfectly efficient. Prices do not always reflect all available information, and even when they do, they may not reflect it instantly. Active managers attempt to identify mispriced securities, anticipate market trends, and adjust portfolios accordingly. This process involves a blend of quantitative analysis, qualitative judgment, and continuous monitoring. Unlike passive managers, who replicate an index and accept its return, active managers aim to generate alpha—the excess return above the benchmark that results from skill rather than market exposure.
One of the defining features of active management is security selection. Managers analyze individual stocks, bonds, or other assets to determine which are undervalued or poised for growth. This analysis can take many forms. Fundamental analysts study financial statements, competitive positioning, and macroeconomic conditions. Technical analysts examine price patterns and market behavior. Quantitative managers rely on statistical models to identify patterns that may not be visible to the human eye. Regardless of the method, the goal is the same: to find opportunities that the broader market has overlooked.
Another key component is market timing. While notoriously difficult to execute consistently, market timing involves adjusting the portfolio’s exposure to different asset classes or sectors based on expectations about future market movements. For example, a manager who anticipates an economic slowdown might reduce exposure to cyclical industries and increase holdings in defensive sectors. Similarly, a bond manager might shift duration or credit exposure in response to interest rate forecasts. Effective market timing can significantly enhance returns, but poor timing can just as easily erode them.
***
https://www.amazon.ca/Management-Liability-Insurance-Protection-Strategies/dp/1498725988
***
Risk management is also central to active portfolio management. Because active managers deviate from the benchmark, they assume additional risks—both intentional and unintentional. Managing these risks requires careful monitoring of portfolio exposures, correlations, and potential downside scenarios. Many active managers use sophisticated tools to measure tracking error, stress‑test portfolios, and ensure that risk levels remain aligned with client objectives. In this sense, active management is not simply about taking more risk; it is about taking the right risks.
Despite its potential benefits, active management faces significant challenges. One of the most persistent criticisms is that many active managers fail to outperform their benchmarks after accounting for fees. Passive strategies, with their lower costs and consistent performance relative to the market, have attracted substantial inflows as a result. The rise of index funds and exchange‑traded funds has intensified competition, forcing active managers to justify their value through performance, innovation, or specialized expertise.
Yet active management continues to thrive in certain areas. Markets that are less efficient—such as small‑cap equities, emerging markets, or niche fixed‑income sectors—often provide fertile ground for skilled managers. In these markets, information is scarcer, trading is less frequent, and mispricings are more common. Active managers can also add value through customization. Investors with specific goals, such as income generation, tax efficiency, or environmental and social considerations, may benefit from a tailored approach that passive strategies cannot easily replicate.
Another advantage of active management is its ability to respond to changing market conditions. Passive portfolios remain fully invested in their index constituents regardless of economic cycles, geopolitical events, or corporate developments. Active managers, by contrast, can reduce exposure to troubled companies, increase cash holdings during periods of uncertainty, or capitalize on emerging opportunities. This flexibility can be particularly valuable during periods of market stress, when dispersion among securities increases and skilled decision‑making can have a meaningful impact.
The future of active portfolio management is likely to be shaped by innovation. Advances in data analytics, machine learning, and alternative data sources are transforming how managers identify opportunities and manage risk. Hybrid strategies that blend active and passive elements—such as smart beta or factor‑based investing—are gaining traction as investors seek cost‑effective ways to enhance returns. At the same time, growing interest in sustainable investing is creating new avenues for active managers to differentiate themselves through research, engagement, and stewardship.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
SPONSOR: http://www.MarcinkoAssociates.com
SPEECH! – SPEECH!
***
***
By David Edward Marcinko; MBBS DPM MBA MEd CMP
The Crisis in Medicine — A Call to Action
Ladies and gentlemen,
Today, I stand before you not just to speak about medicine, but to sound the alarm for a profession in peril. The medical field—once a beacon of hope, healing, and honor—is now grappling with a crisis that threatens its very foundation.
Across the country, doctors are burning out, hospitals are closing, and patients are waiting longer for care that’s increasingly harder to afford. This isn’t just a healthcare issue—it’s a human issue.
At the heart of this collapse is the corporatization of medicine. Physicians, once trusted decision-makers, now find themselves at the mercy of insurance companies, hospital administrators, and profit-driven systems. The art of healing has been replaced by spreadsheets and quotas. Doctors are forced to see more patients in less time, not because it’s better for care—but because it’s better for business.
And what of the next generation? Medical students face crushing debt, often exceeding $300,000. Yet even after years of study, thousands are left unmatched to residency programs due to outdated federal caps. Imagine training for a marathon, only to be told you can’t cross the finish line. That’s the reality for many aspiring physicians today.
The COVID-19 pandemic didn’t create this crisis—but it exposed it. Emergency rooms buckled under pressure. Rural hospitals shuttered. Healthcare workers risked their lives, only to face trauma, exhaustion, and in some cases, violence from the very people they sought to help.
We must also confront a cultural shift—one that undermines science, spreads misinformation, and erodes trust in medical professionals. Doctors are harassed, threatened, and doubted. This isn’t just unfair—it’s dangerous.
So what can we do?
We must advocate for reform. Expand residency slots. Reduce the cost of medical education. Protect physician autonomy. And most importantly, restore the soul of medicine—compassion, integrity, and service.
This is not a time for silence. It’s a time for action. Because when medicine collapses, society suffers. But if we rise together—patients, providers, policymakers—we can rebuild a system that heals not just bodies, but communities.
Thank you.
APPLAUSE!
COMMENTS APPRECIATED
SPEAKING: ME-P Editor Dr. David Edward Marcinko MBA MEd will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: Ask a Doctor, Drugs and Pharma, Touring with Marcinko | Tagged: david marcinko, health, healthcare, life, medical students, medicine, mental health, speech | Leave a comment »
***
***
In December, the Consumer Price Index for All Urban Consumers rose 0.3 percent, seasonally adjusted, and rose 2.7 percent over the last 12 months, not seasonally adjusted. The index for all items less food and energy increased 0.2 percent in December (SA); up 2.6 percent over the year (NSA).
MORE: CPI for all items rises 0.3% in December; shelter and food up
COMMENTS APPRECIATED
***
Filed under: iMBA, Inc. | Leave a comment »
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MedicalExecutivePost.com
***
***
Single‑stock exchange‑traded funds (ETFs) represent one of the most striking shifts in the evolution of modern financial products. Unlike traditional ETFs, which are built around diversification and broad market exposure, single‑stock ETFs focus on just one company. They offer amplified or inverse exposure to the daily performance of a single stock, giving traders a powerful and accessible way to express short‑term market views. Their rise has sparked both enthusiasm and concern, as they blend innovation with significant risk.
At their core, single‑stock ETFs are designed to track the daily movement of one publicly traded company. Many of these funds use leverage, meaning they aim to deliver multiples of the stock’s daily return. A 2× leveraged ETF tied to a technology company, for example, seeks to produce twice the stock’s daily gain or loss. Others offer inverse exposure, allowing traders to profit when a stock declines. This structure transforms what would normally require options, margin accounts, or short‑selling into something as simple as buying or selling shares of an ETF.
The mechanics behind these products rely heavily on derivatives such as swaps and futures. Because they reset daily, the performance of a leveraged or inverse ETF over longer periods can diverge dramatically from the underlying stock’s cumulative return. This effect, often called compounding drift, becomes especially pronounced in volatile markets. A stock that oscillates sharply may leave a leveraged ETF far behind, even if the stock ends up close to where it started. For this reason, single‑stock ETFs are generally intended for short‑term tactical trading rather than long‑term investing.
Despite these complexities, the appeal of single‑stock ETFs is easy to understand. They offer a straightforward way to take bold positions without navigating the intricacies of derivatives markets. A trader who believes a company will surge after an earnings announcement can use a leveraged ETF to amplify potential gains. Someone expecting a sharp decline can use an inverse ETF to benefit from downward movement without borrowing shares or managing margin requirements. These products also trade like ordinary stocks, making them accessible to investors who may not have approval to trade options or use leverage in other forms.
Another group drawn to single‑stock ETFs includes investors looking to hedge concentrated positions. Employees who hold large amounts of their company’s stock, for instance, may use inverse ETFs to offset short‑term downside risk without selling their shares. While this approach requires careful monitoring, it offers a tool for managing exposure in situations where selling stock may not be desirable or possible.
However, the very features that make single‑stock ETFs attractive also make them risky. Leverage magnifies losses just as easily as gains, and the daily reset mechanism means that holding these products for more than a short period can produce unexpected outcomes. Many investors underestimate how quickly losses can accumulate when volatility is high. A leveraged ETF tied to a stock experiencing sharp swings can erode in value even if the stock eventually trends upward. This makes education and awareness essential for anyone considering these products.
Critics argue that single‑stock ETFs encourage speculative behavior and may mislead inexperienced investors who assume they function like traditional ETFs. The simplicity of buying a share can mask the complexity of the underlying strategy. Some market observers worry that the proliferation of these products could increase volatility in the stocks they track, especially when large volumes of leveraged or inverse positions build up around major events like earnings releases.
Supporters counter that single‑stock ETFs democratize access to sophisticated strategies that were once limited to advanced traders. They point out that these products can reduce the need for margin accounts, simplify hedging, and offer a transparent alternative to more opaque derivatives. From this perspective, single‑stock ETFs are simply another tool—powerful when used correctly, dangerous when misunderstood.
As the market continues to evolve, single‑stock ETFs occupy a unique and sometimes controversial space. They reflect a broader trend toward customization and precision in financial products, catering to traders who want targeted exposure rather than broad diversification. Their future will likely depend on how well investors understand their mechanics and how responsibly they are used.
In the end, single‑stock ETFs are neither inherently good nor inherently harmful. They are instruments—innovative, potent, and complex. For disciplined traders with a clear strategy and a firm grasp of the risks, they can be valuable tools. For long‑term investors seeking stability, they are generally unsuitable. The key lies in recognizing what they are designed to do and approaching them with the respect that any leveraged financial product demands.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Staff Reporters
***
***
In the dynamic landscape of modern business, understanding market structure is essential for strategic planning and long-term survival. One of the most compelling frameworks for analyzing competitive environments is the “Rule of Three,” a concept popularized by marketing scholars Jagdish Sheth and Rajendra Sisodia. This theory posits that in any mature industry, three dominant companies will eventually control between 70% and 90% of the market share, while smaller niche players survive by specializing. The Rule of Three offers a powerful lens through which businesses can evaluate their position and make informed strategic decisions.
The foundation of the Rule of Three lies in the natural evolution of competitive markets. As industries grow and mature, inefficiencies are weeded out, and consolidation occurs. Companies that fail to scale or differentiate are often absorbed, driven out, or relegated to niche segments. The three dominant firms that emerge typically offer broad product lines, extensive distribution networks, and economies of scale that allow them to compete effectively on price and reach. These firms are not necessarily the most innovative, but they are the most efficient and resilient.
Real-world examples abound. In the U.S. automotive industry, General Motors, Ford, and Stellantis (formerly Chrysler) have long dominated. In the fast-food sector, McDonald’s, Burger King, and Wendy’s hold the lion’s share of the market. Even in technology, Apple, Microsoft, and Google represent the triad of influence across hardware, software, and digital services. These companies exemplify the Rule of Three by maintaining strong brand recognition, operational efficiency, and strategic adaptability.
The Rule of Three also highlights the plight of mid-sized firms. These companies often find themselves squeezed between the dominant players and niche specialists. Without the scale to compete on cost or the uniqueness to attract a specialized audience, they face strategic ambiguity. The theory suggests that such firms must either grow aggressively to join the top tier or shrink intentionally to become niche providers. This insight is particularly valuable for business leaders evaluating mergers, acquisitions, or repositioning strategies.
Niche players, on the other hand, thrive by focusing on specific customer needs, geographic markets, or product categories. Their success lies not in competing with the giants but in offering tailored solutions that the big three cannot efficiently provide. Examples include boutique coffee roasters, artisanal food brands, and specialized software firms. These companies often enjoy loyal customer bases and higher margins, albeit with limited scalability.
Critics of the Rule of Three argue that digital disruption and globalization have complicated market structures, allowing for more fluid competition and the rise of platform-based ecosystems. However, even in these environments, the pattern of three dominant players often persists, albeit with shifting boundaries and definitions of market control.
In conclusion, the Rule of Three remains a valuable strategic tool for understanding competitive dynamics. It encourages businesses to assess their scale, specialization, and strategic direction within the broader market context. Whether aiming to become a dominant player or a niche specialist, recognizing the forces that shape market structure is key to surviving and thriving in competitive industries.
COMMENTS APPRECIATED
Like, Refer and Subscribe
***
***
Filed under: "Ask-an-Advisor", business, Career Development, Glossary Terms, Management | Tagged: AI, Apple, artificial intelligence, Burger King, ChatGPT, competition, competitive markets, Ford, GM, google, Jagdish Seth PhD, microsoft, MSFT, rule of 3, Technology, tule of threes, Wendy's | Leave a comment »
DEFINITIONS
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MarcinkoAssociates.com
***
***
Intrinsic value and market price represent two foundational yet distinct concepts in the field of equity valuation. Although they are often discussed together, they arise from different analytical frameworks and serve different purposes in investment decision‑making. Understanding the divergence between them is essential for evaluating securities with discipline rather than reacting to short‑term market fluctuations. The contrast between intrinsic value and market price also illuminates why financial markets can oscillate between periods of rational assessment and episodes of pronounced mispricing.
Intrinsic value refers to an estimate of a company’s true economic worth based on its ability to generate future cash flows. This estimate is typically derived through analytical methods such as discounted cash‑flow modeling, which requires assumptions about revenue growth, profit margins, capital expenditures, competitive dynamics, and the appropriate discount rate to reflect risk. Because these inputs involve forecasting and judgment, intrinsic value is inherently an approximation rather than a precise figure. It reflects a long‑term perspective grounded in fundamental analysis and an attempt to determine what a business should be worth if market participants were fully informed and entirely rational.
Market price, in contrast, is the observable price at which a stock trades at any given moment. It is determined by the interaction of buyers and sellers in the marketplace and is influenced by a wide range of factors, including investor sentiment, liquidity conditions, macroeconomic news, and short‑term speculation. Market price is therefore a real‑time expression of collective behavior rather than a direct measure of underlying business performance. Because it is shaped by human psychology, it can deviate significantly from fundamental value, sometimes for extended periods.
The divergence between intrinsic value and market price is central to the practice of investing. When market price falls below a well‑reasoned estimate of intrinsic value, the security may represent an attractive opportunity. Conversely, when market price exceeds intrinsic value, the stock may be overvalued and vulnerable to correction. This gap between the two concepts forms the basis of value investing, which relies on identifying mispriced securities and exercising patience while the market gradually corrects its errors. The existence of such mispricing also demonstrates that markets, while often efficient in processing information, are not perfectly efficient at all times. And, several factors contribute to the persistent gap between intrinsic value and market price.
***
***
First, intrinsic value evolves slowly because the underlying economics of a business typically change over long horizons. Market price, however, can shift dramatically within minutes in response to news events, rumors, or shifts in investor sentiment. This difference in time horizons means that short‑term volatility often reflects emotional reactions rather than changes in fundamental value.
Second, intrinsic value is sensitive to the assumptions used in its calculation. Analysts may disagree about growth prospects, competitive threats, or appropriate discount rates, leading to a range of plausible valuations for the same company. Market price, by contrast, aggregates the views of many participants, but aggregation does not guarantee accuracy. The market’s consensus can be overly optimistic during periods of exuberance or excessively pessimistic during times of uncertainty.
Third, risk is incorporated differently in intrinsic value and market price. Intrinsic value accounts for risk through discounting and scenario analysis, whereas market price reflects risk through volatility and investor behavior. During periods of heightened uncertainty, market prices often decline more sharply than intrinsic value would justify, as fear amplifies selling pressure. Conversely, during periods of optimism, prices may rise faster than fundamentals warrant, as investors become willing to pay a premium for anticipated growth.
For long‑term investors, intrinsic value serves as an analytical anchor. It provides a disciplined framework for evaluating whether the market is offering a security at a discount or demanding an excessive premium. Market price, meanwhile, provides the mechanism through which opportunities arise. Without fluctuations in price, there would be no mispricing to exploit and no advantage to conducting fundamental analysis.
It is important, however, to recognize that intrinsic value is not a single, definitive number. It is more appropriately understood as a range of reasonable estimates. Investors who treat intrinsic value as exact risk making decisions with unwarranted confidence. A prudent approach involves establishing a margin of safety—purchasing securities only when market price is meaningfully below the lower bound of the estimated intrinsic value range. This margin helps protect against errors in judgment and unforeseen developments.
In sum, the relationship between intrinsic value and market price lies at the heart of investment analysis. Market price reflects the market’s immediate assessment, shaped by emotion and information flow, while intrinsic value reflects a reasoned evaluation of long‑term economic potential. When the two align, investment decisions are straightforward. When they diverge, the opportunity for thoughtful, disciplined investing emerges.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
By Dr. David Edward Marcinko; MBA MEd
***
SPONSOR: http://www.MarcinkoAssociates.com
Here are some widely used heuristics in economics:
These rules simplify complex relationships, but they’re not foolproof. They’re best used as starting points for analysis, not as rigid laws.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
Filed under: "Ask-an-Advisor", business, economics, finance, Investing, Marcinko Associates | Tagged: books, david marcinko, economic rules thumb, environment, financial rules thumb, GDP, google, J curve, NAIRU, observations, okun's law, Phillips Curve, PPP, random-thoughts, rules of thumb, taylor rule | Leave a comment »
DEFINITIONS
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MarcinkoAssociates.com
***
***
Endowment funds play a distinctive and influential role in the financial stability and long‑term planning of many institutions. They are most commonly associated with universities, foundations, cultural organizations, and nonprofits, but the underlying concept applies broadly: an endowment is a pool of invested capital designed to generate sustainable income far into the future. What makes endowment funds unique is their dual purpose. They must support current operations while preserving purchasing power for generations to come. This balancing act shapes how they are structured, managed, and governed, and it explains why endowments have become essential tools for mission‑driven organizations seeking financial resilience.
At the heart of an endowment fund is the principle of perpetuity. Donors contribute capital with the expectation that it will not be spent outright but instead invested to produce ongoing returns. These returns—rather than the principal—are used to fund scholarships, research, community programs, or other mission‑aligned activities. Because the goal is long‑term sustainability, endowment managers must adopt investment strategies that balance growth and stability. They cannot afford to take excessive risks that jeopardize the fund’s future, nor can they be overly conservative, as inflation would erode the real value of the endowment over time. This tension between risk and preservation is one of the defining challenges of endowment management.
Most endowment funds are divided into three components: the principal, the income, and the spending allocation. The principal, often called the corpus, is the original gift and any subsequent contributions that must remain intact. The income consists of investment returns—interest, dividends, and capital gains. The spending allocation is the portion of that income the institution withdraws each year to support its operations. Many organizations follow a spending rule, often around four to five percent of the endowment’s average market value, to ensure stability and predictability. This rule smooths out the impact of market volatility and helps institutions plan their budgets with confidence.
Investment strategy is central to the success of an endowment fund. Because these funds are designed to last indefinitely, they typically adopt a diversified, long‑term approach. Asset allocation often includes a mix of equities, fixed income, real estate, private equity, hedge funds, and other alternative investments. Equities provide growth potential, while bonds offer stability and income. Alternative assets can enhance returns and reduce correlation with traditional markets. The goal is to create a portfolio that can weather economic cycles and deliver consistent performance over decades. Endowment managers must also consider liquidity needs, ethical investment guidelines, and regulatory requirements, all of which influence portfolio construction.
Governance is another critical aspect of endowment management. Most institutions rely on investment committees, boards of trustees, or dedicated financial officers to oversee the fund. These governing bodies establish policies, monitor performance, and ensure that investment decisions align with the organization’s mission and donor intent. Transparency and accountability are essential, as endowments often attract public scrutiny, especially when they grow to significant size. Clear communication about spending policies, investment philosophy, and financial results helps maintain trust among donors, beneficiaries, and the broader community. Endowment funds provide several other important benefits.
First, they offer financial stability. Because endowment income is relatively predictable, institutions can rely on it to support core operations even during economic downturns or periods of reduced fundraising. This stability is particularly valuable for universities, which use endowment earnings to fund scholarships, faculty positions, and academic programs. Second, endowments promote independence. Organizations with strong endowments are less vulnerable to fluctuations in government funding, tuition revenue, or donor contributions. This independence allows them to pursue long‑term goals without being overly constrained by short‑term financial pressures. Third, endowments encourage innovation. With a steady source of funding, institutions can invest in new initiatives, research projects, or community programs that might not be possible otherwise.
Despite their advantages, endowment funds also face challenges. Market volatility can significantly impact investment returns, affecting the amount available for spending. Inflation poses a long‑term threat to purchasing power, requiring careful management to ensure that the endowment continues to meet future needs. Ethical considerations have also become more prominent, with many stakeholders calling for socially responsible investment practices. Balancing financial performance with environmental, social, and governance priorities can be complex, but it reflects the evolving expectations of donors and society.
Endowment funds remain powerful instruments for supporting institutional missions across generations. Their structure encourages disciplined financial management, their investment strategies promote long‑term growth, and their governance frameworks ensure accountability. While they require careful stewardship, the rewards are substantial: stability, independence, and the ability to make a lasting impact. For organizations committed to enduring missions, endowment funds are not just financial assets—they are foundations for the future.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »
Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.DavidEdwardMarcinko.com
***
***
Social contact marketing has become an essential strategy for doctors who want to build trust, strengthen patient relationships, and create a meaningful presence in their communities. In a healthcare environment where patients have more choices than ever and often feel overwhelmed by information, the way a doctor communicates outside the exam room can be just as important as the care delivered inside it. Social contact marketing focuses on consistent, authentic, human-centered interactions that help doctors remain visible, approachable, and relevant. It is not about advertising in the traditional sense; it is about cultivating connection.
At its heart, social contact marketing is built on the idea that people seek care from professionals they trust. Trust is not formed through a single interaction but through repeated, positive touchpoints. For doctors, these touchpoints can take many forms: educational posts on social media, community events, email newsletters, follow-up messages, or even simple check-ins during key moments in a patient’s health journey. Each interaction reinforces the doctor’s presence and reliability. Over time, this steady visibility helps patients feel more comfortable, more informed, and more confident in their provider.
One of the most powerful aspects of social contact marketing for doctors is the ability to educate. Healthcare is complex, and many patients struggle to understand medical terminology, treatment options, or preventive strategies. When doctors share clear, accessible information—whether through short videos, infographics, or written posts—they help demystify healthcare. This not only empowers patients but also positions the doctor as a trusted guide. Patients begin to see the doctor as someone who genuinely wants them to understand their health, not just someone who prescribes treatments. This shift in perception deepens loyalty and encourages patients to take a more active role in their well-being.
Another key component is personalization. Patients want to feel seen as individuals, not as case numbers. Social contact marketing allows doctors to tailor their communication to the needs and interests of different groups. For example, a pediatrician might share tips for new parents, while a cardiologist might focus on heart-healthy lifestyle habits. Personalized birthday messages, reminders for annual checkups, or follow-ups after major life events can make patients feel valued. These small gestures communicate that the doctor cares about the person, not just the appointment. In a field where empathy is essential, this kind of personalized outreach can significantly strengthen the doctor–patient relationship.
Community involvement also plays a major role in social contact marketing for doctors. Healthcare professionals who participate in local events, volunteer programs, or educational workshops create opportunities for organic, face-to-face interactions. These moments help humanize the doctor and build familiarity. When people meet a doctor in a relaxed, community setting, they often feel more comfortable asking questions or seeking advice. This familiarity can translate into trust, which is especially important when patients must make difficult or emotional healthcare decisions. By blending community presence with digital follow-up, doctors can maintain long-lasting connections that extend beyond the clinic walls.
Consistency is another essential element. Social contact marketing is not about occasional posts or sporadic outreach. It requires a steady rhythm of communication that mirrors the reliability patients expect from their healthcare providers. When doctors consistently share helpful information, respond to comments, or check in with patients, they reinforce their commitment to care. This consistency builds a narrative of dependability. Patients begin to associate the doctor with stability, which is especially comforting in moments of uncertainty or illness. Over time, this dependable presence becomes a defining part of the doctor’s reputation.
***
***
Importantly, social contact marketing also allows doctors to show their human side. Patients often feel intimidated by medical environments or perceive doctors as distant authority figures. Sharing glimpses of personal interests, behind-the-scenes moments in the clinic, or stories about why they chose medicine can help break down those barriers. These authentic moments remind patients that their doctor is a person with passions, values, and a desire to help. This emotional connection can make patients more comfortable discussing sensitive issues, asking questions, or seeking care early rather than waiting until a problem becomes serious.
Another benefit of social contact marketing is its ability to support preventive care. Many health issues can be avoided or managed more effectively when patients receive timely reminders or guidance. Doctors who use social platforms or email newsletters to share seasonal health tips, vaccination reminders, or lifestyle advice help keep patients engaged in their own health. This proactive communication can lead to better outcomes and reduce the need for emergency interventions. It also reinforces the doctor’s role as a partner in long-term wellness rather than a provider who only appears when something goes wrong.
Social contact marketing also helps doctors differentiate themselves in a crowded healthcare landscape. With so many clinics, urgent care centers, and specialists available, patients often rely on familiarity and trust when choosing a provider. A doctor who maintains an active, helpful presence in the community—both online and offline—stands out. Patients are more likely to remember a doctor who regularly shares useful insights or participates in local events than one who remains invisible outside the clinic. This visibility can lead to more referrals, stronger patient retention, and a more positive reputation overall.
Ultimately, social contact marketing is not about self-promotion; it is about relationship-building. It recognizes that healthcare is deeply personal and that patients want to feel connected to the people who care for them. For doctors, adopting this approach means shifting from transactional communication to relational engagement. It means prioritizing presence, empathy, and authenticity. When doctors embrace this mindset, they create a supportive ecosystem where patients feel informed, valued, and understood.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
***
Filed under: iMBA, Inc. | Tagged: david marcinko | Leave a comment »


