DAILY UPDATE: Aetna Ratings Down as Stock Markets Flatten

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

Aetna, CVS’s health insurance arm and the third largest payer in the US, is struggling amid higher medical costs and lower Medicare Advantage star ratings. After CVS reported a nearly 40% YoY drop in operating income in its Q2 2024 earnings released on August 7th, President and CEO Karen Lynch announced the company will replace Aetna’s president, Brian Kane, and initiate a $2 billion cost-savings plan.

CITE: https://www.r2library.com/Resource

What’s up

  • Nvidia jumped 4.08% after it was named a top “rebound” stock by Bank of America.
  • Keycorp leaped 9.24% on the news that the Bank of Nova Scotia will invest $2.8 billion in the company.
  • Robinhood Markets rose 3.46% due to an upgrade from Piper Sandler analysts who say the company’s sudden decline gives it an attractive entry point.
  • Monday.com popped 14.78% thanks to a strong earnings report from the software maker, due in no small part to sealing the largest deal in company history.
  • Barrick Gold soared 9.36% after beating earnings estimates on both the top and bottom lines thanks to the rising price of gold.

What’s down

Here’s where the major stock benchmarks ended:

  • The S&P 500®  index (SPX)added 0.23(0.00%) to 5,344.39; the Dow Jones Industrial Average® ($DJI) fell 140.53 points (–0.36%) to 39,357.01; the NASDAQ Composite rose 35.30points (0.21%) to 16,780.61.
  • The 10-year Treasury note yield (TNX) fell three basis points to just under 3.91%.
  • The CBOE Volatility Index® (VIX) increased 0.34 points (1.67%) to 20.71.

CITE: https://tinyurl.com/2h47urt5

Stat: 8.2%. That’s the percentage of people in the US without health insurance in the first quarter of 2024. (Healthcare Dive)

CITE: https://tinyurl.com/tj8smmes

Visualize: How private equity tangled banks in a web of debt, from the Financial Times.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

What is an “INTERVAL” Mutual Fund?

By Staff Reporters

***

An interval fund is a closed-end mutual fund that buys back shares only during specific intervals. Shares of the First Eagle Credit Opportunities Fund aren’t traded on public exchanges, and purchases or sales take place at the close of business, at the net asset value (NAV).

CITE: https://www.r2library.com/Resource/Title/0826102549

A fund’s NAV is simply the sum of its assets divided by the number of shares. A traditional open-ended mutual fund isn’t publicly traded either, and investors can buy or sell at NAV at the market close every business day. This means the manager of an open-ended fund has limited investment choices because a relatively high level of liquidity is needed to handle daily re-demptions.

***

An interval fund sets intervals (time periods) during which shares can be sold back to the fund manager and the number of shares it is willing to redeem during any interval. This makes it possible for the manager to go for higher yields by participating in less liquid markets.

***

RELATED: https://www.investopedia.com/articles/investing/120516/what-interval-fund.asp

YOUR COMMENTS ARE APPRECIATED.

Thank You

***

FINANCE: https://www.amazon.com/Comprehensive-Financial-Planning-Strategies-Advisors/dp/1482240289/ref=sr_1_1?ie=UTF8&qid=1418580820&sr=8-1&keywords=david+marcinko

***

DAILY UPDATE: Consumer Spending with Spotlight on Intel

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

***

CITE: https://www.r2library.com/Resource

US consumers in the spotlight: How much have you been shopping? We’ll find out this week when crucial July retail sales data is released on Thursday, and Walmart and Home Depot report earnings. The resilience of the US consumer is at the heart of recent concerns over a potential downturn since consumer spending drives 70% of the US economy. So far this earnings season, companies have given more mixed signals than a menu offering jumbo shrimp.

CITE: https://tinyurl.com/2h47urt5

Tech giant Intel will be shedding more than 15% of its workforce—or over 19,000 employees—as part of a plan to cut $10 billion in costs after it failed to meet quarterly expectations.

Intel reported revenue of $12.83 billion on expectations of $12.94 billion in revenue in its second quarter 2024 earnings, reported CNBC. The company reported plunging from a net income of $1.48 billion in Q2 2023 to a net loss of $1.61 billion YOY.

CITE: https://tinyurl.com/tj8smmes

Visualize: How private equity tangled banks in a web of debt, from the Financial Times.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

What is a Stock Market Index IMPLIED OPEN?

FINANCIAL TERMS AND DEFINITIONS FOR PHYSICIANS AND ALL INVESTORS

By Dr. David E. Marcinko MBA MEd CMP®

https://certifiedmedicalplannerdotorg1.files.wordpress.com/2012/03/cmp-logo17.jpg

SPONSOR: http://www.CertifiedMedicalPlanner.org

***

The stock markets have been near all time highs, lately. Physician colleagues and clients are so excited that they are even checking the overnight status of favorite stocks and/or the domestic/overseas markets.

Some colleagues are even becoming a bit OCD by checking the implied open of various markets the night before. But, what exactly is the Implied Open? How is it calculated?

DEFINITION: The Implied Open attempts to predict the prices at which various stock indexes will open, at 9:30am New York time. It is frequently shown on various cable television channels prior to the start of the next business day.

Product Details

CITE: https://www.r2library.com/Resource/Title/0826102549

EXAMPLE: Considering the DJIA as an example, the basis of calculating implied open is the price of a “DJX index option futures contract”. This is not the price of the DJIA itself but rather the current ticker price of an option issued by the Chicago Board Options Exchange.

CBOE: The Chicago Board Options Exchange, located at 400 South LaSalle Street in Chicago, is the largest U.S. options exchange with annual trading volume that hovered around 1.27 billion contracts at the end of 2014. CBOE offers options on over 2,200 companies, 22 stock indices, and 140 exchange-traded funds.

CALCULATION: https://www.quora.com/How-do-you-calculate-the-implied-open-from-futures

***

NOTE: We would like to remind you that new amendments adopted by the U.S. Securities Exchange Commission (SEC) have gone into effect as of September 28, 2021. These amendments restrict the ability of market makers to publish OTC quotations for those companies that have not made required current financial and company information available to regulators and investors.

***

YOUR COMMENTS ARE APPRECIATED.

Thank You

***

PODCAST: Direct Primary Care Entrepreneurship and Innovation

By Free Market Medical Association

***
DEFINITION:
Direct Primary Care (DPC) is an innovative alternative payment model improving access to high functioning healthcare with a simple, flat, affordable membership fee.  No fee-for-service payments.  No third party billing.  The defining element of DPC is an enduring and trusting relationship between a patient and his or her primary care provider.  Patients have extraordinary access to a physician of their choice, often for as little as $70 per month, and physicians are accountable first and foremost their patients.  DPC is embraced by health policymakers on the left and right and creates happy patients and happy doctors all over the country!

CITE: https://www.r2library.com/Resource/Title/082610254

***

***

COMMENTS APPRECIATED

Thank You

***

MANAGED CARE: https://www.amazon.com/Dictionary-Health-Insurance-Managed-Care/dp/0826149944/ref=sr_1_4?ie=UTF8&s=books&qid=1275315485&sr=1-4

***

BUSINESS MEDICINE: https://www.amazon.com/Business-Medical-Practice-Transformational-Doctors/dp/0826105750ht/ref=sr_1_9?ie=UTF8&qid=1448163039&sr=8-9&keywords=david+marcinko

***

PODCAST: Healthcare Start-Ups, Accelerators and Incubators

By Eric Bricker MD

***

***

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: MDMA, Stellantis & Zelle While Correlation is not Causation

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

CITE: https://www.r2library.com/Resource

The FDA declined to approve MDMA as a PTSD treatment, which would have been a big step forward for psychedelics use in mental health care, saying further study is needed. But the agency did approve a nasal spray to treat severe allergic reactions as an alternative to shots like EpiPen.

Stellantis will lay off 2,450 factory workers this year as it phases out an older version of its Ram pickup truck.

CITE: https://tinyurl.com/2h47urt5

Scams via Zelle, the payment service you turn to when you run out of wedding gift ideas, are the subject of an ongoing inquiry by the Consumer Financial Protection Bureau (CFPB), the Wall Street Journal reported this week. Zelle was founded in 2017 by seven of the biggest US banks to compete with peer-to-peer payment apps like Venmo and Cash App. It outgrew its rivals but became a magnet for scams, which customers typically don’t get reimbursed for.

CITE: https://tinyurl.com/tj8smmes

Correlate: A website that shows spurious correlations.

Visualize: How private equity tangled banks in a web of debt, from the Financial Times.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

Appreciating the Six Types of Investment Fees

dr-marcinkoDR. DAVID EDWARD MARCINKO MBA MEd CMP

SPONSOR: http://www.MARCINKOASSOCIATES.com

investing

Investment fees matter. They can make a big difference to your financial health in the long run. Before you put money into any investment, it’s vital to uncover the real costs.They typically include these six types of fees:

1. An up-front commission earned by the salesperson or their firm. Don’t rely on a vague assurance or a verbal answer: get a specific number in writing.If you have trouble getting a number, ask, “If I buy this investment today and want to get out tomorrow, how much do I get back?” If the answer is not “all your money,” the difference is probably the upfront fees and commissions.

I don’t recommend purchasing financial products with significant upfront commission or costs. I have seen investments where these fees run as high as 30% of the money invested. If you were to earn 5% a year on the investment, it would take 8 years just to break even.

2. Ongoing advisory fees. These are monthly, quarterly, or annual fees you pay advisors for their investment advice and oversight. This includes working with you to pick the asset classes, set the diversification, select the managers, tax optimization, rebalancing, and other periodic tasks.

This fee can have many names including wrap fee or investment advisory fee. The normal “rule of thumb” is 1% of the assets the advisor is managing, although fees can range from 0 to 7%. This fee can be charged to you even if the advisor receives an upfront commission. It can be easy to see or hidden away in the fine print of the investment.

3. Additional fees for services. Find out specifically what services are included in the advisor fee. Additional fees for financial planning or ancillary services are rarely disclosed or discussed.

Services can range from minimal hand-holding only focused on your investments to comprehensive, holistic financial planning. Amazingly, there is no correlation between price and the breadth of services. That’s illogical, but the financial services industry gets away with this, in part because consumers don’t do their homework.

4. Ongoing fees charged by the managers of the specific funds or investment products. These fees are referred to as the fund’s expense ratio. This comes out of the profits generated by the manager, and it is one of the hardest fees to find. Only the most transparent advisor or salesperson will disclose it. It is incredibly well hidden; you will never see it in your brokerage statements or your advisor’s invoices. The only way to know the amount of this fee is to read the prospectus or some other third party analysis of the investment, like Morningstar.

These fees can vary greatly for the same investment, depending on the class of share you buy. For example, American Fund’s New Perspective Fund’s expense ratio ranges from0.45% to 1.54%.  The average expense ratio of a mutual fund that invests in stocks is 1.35%. Conversely, the average expense ratio of a Vanguard S&P 500 fund is 0.10%. The difference of 1.25% is staggering over time.

5. Miscellaneous fees. These are also rarely talked about and hard to find. Many advisors charge $50 to $100 a year per account, hundreds of dollars to open or close an account, and even fees to dollar cost average your funds into the market.

6. Transaction fees. Every time you buy or sell a fund, a fee is typically paid to a custodian. These can range from $5 to hundreds of dollars per transaction.

Assessment

Remember, it’s your job to persist until you find out the total costs of an investment. Next week I’ll suggest ways to ask the tough questions about fees.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure. 

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. https://medicalexecutivepost.com/dr-david-marcinkos-bookings/ 

Contact: MarcinkoAdvisors@msn.com

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

2025 Proposed Physician Fee Schedule Cuts Payments – Again

By Health Capital Consultants, LLC

***

***

On July 10, 2024, the Centers for Medicare & Medicaid Services (CMS) released its proposed Medicare Physician Fee Schedule (MPFS) for calendar year (CY) 2025.

CITE: https://www.r2library.com/Resource

In addition to the agency’s suggested cut to physician payments, the proposed rule also announced new covered services. According to CMS, the proposed rule “reflect[s] a broader Administration-wide strategy to create a more equitable health care system that results in better accessibility, quality, affordability, empowerment, and innovation for all Medicare beneficiaries.(Read more…)

COMMENTS APPRECIATED

Thank You

***

***

ETFs: Happy 31st. Birthday

EXCHANGE TRADED FUNDS

By Staff Reporters

SPONSOR: http://www.MarcinkoAssociates.com

***

***

Thirty one years ago yesterday, the first exchange-traded fund (ETF) in the US launched. In the decades since, these once-niche investment products have become ubiquitous on Wall Street, disrupting the mutual fund industry and transforming people’s relationship with the stock market.

CITE: https://www.r2library.com/Resource/Title/0826102549

Exchange Traded Funds

On January 29th, 1993, a spider decoration hanging in the American Stock Exchange heralded the arrival of the first US ETF—what’s now called the SPDR S&P 500 ETF Trust. It had a measly $6.5 million in assets and no one really paid much attention to it. The first US ETF is now the world’s biggest, with $375 billion in assets, and the ETF sector in total had amassed $6.5 trillion in assets by the end of 2022. While mutual funds still have 3x the amount of assets that ETFs have, the tide is turning: Investors poured $600 billion into US ETFs on a net basis last year, but pulled out almost $1 trillion from mutual funds.

ETFs and Tax Efficiency

Definition: An ETF is simply a security that tracks the performance of a particular basket of investments, like stocks. The SPDR S&P 500 ETF, for example, tracks the performance of companies in the S&P 500. Many other ETFs also track indexes, allowing people to park their money in funds that follow the ebbs and flows of the broader market.

If that sounds like a mutual fund…it’s similar. But ETFs have a few advantages over its stuffy, older cousin.

  • ETFs generally have lower fees than mutual funds.
  • They have built-in tax benefits.
  • They’re accessible to anyone with a brokerage account—you can buy or sell them like you would a stock.

CITE: https://www.r2library.com/Resource/Title/0826102549

Finally, all these advantages aside, the rise of ETFs has been also fueled by the growing recognition that trying to invest in individual stocks is foolish. Passive index funds, which aren’t designed for frequent trading, have surged to represent almost half of US fund assets, compared to less than 2% in the early ’90s.

COMMENTS APPRECIATED

Thank You

***

ORDER: https://www.routledge.com/Comprehensive-Financial-Planning-Strategies-for-Doctors-and-Advisors-Best/Marcinko-Hetico/p/book/9781482240283

***

DAILY UPDATE: Medicare, Google & Meta, FTX and the Rising Markets

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

FTX was ordered to pay $12.7 billion to customers. All customers will recoup their deposits that were locked when the crypto exchange went under in 2022, the Commodity Futures Trading Commission just said last Thursday.

CITE: https://www.r2library.com/Resource

Read: How one-hour patient home visits allowed insurers to collect $15 billion from Medicare between 2019 and 2021. (the Wall Street Journal)

CITE: https://tinyurl.com/2h47urt5

What’s up

  • Sweetgreen popped 33.33% after a strong earnings report coupled with forecasts of higher-than-expected sales in 2024.
  • Doximity soared 38.70% thanks to a beat-and-raise quarter from the medical platform that has been investing in its own DoximityGPT AI model.
  • Nikola rose 8.21% after a surprisingly strong quarter in which sales soared 318%.
  • Unity Software jumped 8.22% despite revenue coming in lower year over year, but it was still higher than Wall Street expected.
  • Take-Two Interactive Software surged 4.35% after it beat earnings estimates last quarter, but no word yet on how its Gearbox acquisition is helping its bottom line, nor when GTA 6 is going to be released.
  • Expedia traveled 10.21% higher due to an earnings beat, with the company sidestepping a consumer spending slowdown quite nicely.

What’s down

CITE: https://tinyurl.com/tj8smmes

Here’s where the major benchmarks ended:

  • The S&P 500® index (SPX) rose 25 points (0.5%) to 5,344.16, ending the week little changed; the Dow Jones Industrial Average® ($DJI) rose 51 points (0.1%) to 39,497.54 to end the week down about 0.6%; the NASDAQ Composite® ($COMP) ended 85 points higher (0.5%) at 16,745.30, leaving it about 0.2% lower for the week.
  • The 10-year Treasury note yield (TNX) dropped five basis points to 3.944%.
  • The Cboe Volatility Index (VIX) declined three points (13%) to 20.7.

Google and Meta teamed up to target teens with ads for Instagram on YouTube, going against Google’s own rules, the Financial Times reported.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

What is Financial – Tech?

The Definition of Fin-Tech

cropped-dem

By Dr. David E. Marcinko MBA MEd CMP

Fintech is a portmanteau of financial technology that describes an emerging financial services sector in the 21st century.

Originally, the term applied to technology applied to the back-end of established consumer and trade financial institutions. Since the end of the first decade of the 21st century, the term has expanded to include any technological innovation in the financial sector, including innovations in financial literacy and education, retail banking, investment and even crypto-currencies like bitcoin.

BREAKING DOWN ‘Fintech’

The term financial technology can apply to any innovation in how people transact business, from the invention of money to double-entry bookkeeping. Since the internet revolution and the mobile internet revolution, however, financial technology has grown explosively, and fintech, which originally referred to computer technology applied to the back office of banks or trading firms, now describes a broad variety of technological interventions into personal and commercial finance.

Fintech’s Expanding Horizons

Already technological innovation has up-ended 20th century ways of trading and banking. The mobile-only stock trading app Robinhood charges no fees for trades, and peer-to-peer lending sites like Prosper and Lending Club promise to reduce rates by opening up competition for loans to broad market forces. Technologies being designed that should reach fruition by 2020 include mobile banking, mobile trading on commodities exchanges, digital wallets (like Apple (AAPL) and Google’s (GOOG) developing mobile wallet systems), financial advisory and robo-advisor sites like LearnVest and Betterment, and all-in-one money management tools like Mint and Level.

***

2f436b72-e961-4350-90cf-38293b834eb0-original

***

New Tech in Fintech

In the olden days, individuals and institutions used the invisible hand of the market – represented by the signaling function of price – to make financial decisions. New technologies, like machine learning, predictive behavioral analytics and data-driven marketing, will take the guess work and hocus pocus out of financial decisions. “Learning” apps will not only learn the habits of users, often hidden to themselves, but will engage users in learning games to make their automatic, unconscious spending and saving decisions better. On the back end, improved data analytics will help institutional clients further refine their investment decisions and open new opportunities for financial innovation.

Fintech Users

Who uses fintech? There are four broad categories: 1) B2B for banks and 2) their business clients; and 3) B2C for small businesses and 4) consumers. Trends toward mobile banking, increased information, data and more accurate analytics and decentralization of access will create opportunities for all four groups to interact in heretofore unprecedented ways.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

Musings on “Sector” Mutual Funds

A Historical Review

By Dr. David Edward Marcinko MBA, MEd, CMP™

www.CertifiedMedicalPlanner.org

[Publisher-in-Chief]

Although less than 5-10% of the total number of mutual funds are considered true sector funds, year after year, 40-50% or more of the top-performing funds have been sector funds. However, for some physician investors sold on a buy-and-hold strategy, sector funds may not be their cup of tea. But, sector funds do offer an opportunity to outperform the market indices, possibly even substantially, according to Marshall Schield in “Developing a Sector Funds Strategy” (Personal Financial Planning, November/December 1996, pp. 39–42, Warren, Gorham & Lamont, [800] 950-1205).

A Volatile Strategy

Typically sector funds are more volatile than the majority of growth funds. This volatility springs from: (1) the fact that the majority of stocks in a particular sector fund move together, thereby magnifying the fund’s movement; (2) the focus of the sector fund manager only on stocks in that sector, enabling him or her to target high potential stocks; and (3) the rotation of “in” and “out” sectors at particular times.

So – What’s a Doctor Investor to Do?

An investor in sector funds needs a strategy that will target sectors on the upswing and signal when to move out of declining funds. When selecting sector funds, Schield recommends building a list of funds that are manageable, full of choices in all types of markets, diversified (three to four funds for an aggressive portfolio or 10–12 for a less aggressive approach) and liquid.

The Balancing Act

Also, develop a healthy balance—not a “hit-or-miss” approach. Schield suggested using the “relative strength” approach for sector selection by computing the percent change in the price of funds over a certain number of days and then ranking them for short-term, intermediate, and long-term periods. With respect to determining the proper timing for buying or selling, the author suggests the use of an individual fund timing system, such as comparing the current NAV of the sector against a moving average for 50 or 75 days or combining both short- and long-term moving averages.

Simplicity Rules

In creating buy-and-sell signals:

  • Keep it simple and manageable.
  • Do not look for perfection.
  • Practice patience.
  • Cut losses and let profits run.
  • Stick with your relative strength.
  • Buy/sell signals consistently.

Assessment

Most of all; be prepared to spend and invest the time necessary to be successful. But, have you or your sector funds been successful in the last decade, or so? If so, which sectors? Please opine?’

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct DetailsProduct Details

Product Details  Product Details

   Product Details 

What is a CARRY TRADE?

By Staff Reporters

***

***

A carry trade is a tactic in which an investor borrows a currency with lower interest rates and invests the proceeds in a higher-yielding asset, often in a different market with higher interest rates.

CITE: https://www.r2library.com/Resource

Over the past few years, many funds were using this strategy by buying US equities or selling US bonds with money borrowed from the yen because of the huge disparity in interest rates between the US and Japan. Japan kept the yen cheap on purpose because its economy is primarily export-driven, and the low price of Japanese products kept exports thriving. And the dollar, as the dominant global currency, has remained impressively strong through thick and thin.

This was all fun and profits, until Japan raised interest rates for the first time in 17 years last week. Suddenly, the yen wasn’t as cheap as it once was. And at the exact same time, the US is expected to cut interest rates in September, which means the dollar would become less valuable, completely throwing this international carry trade out of balance

COMMENTS APPRECIATED

Thank You

***

***

What is Risk Adjusted Stock Market Performance?

Update on Some Interesting and Important Financial Calculations

By Timothy J. McIntosh MBA CFP® MPH

By Dr. David Edward Marcinko MBA MEd CMP™

By Jeffrey S. Coons PhD CFA

TMDr. Jeff Coons

dr-david-marcinko9

-INTRODUCTION-

Performance measurement, like an annual physical, is an important feedback loop to monitor progress towards the goals of the medical professional’s investment program.  Performance comparisons to market indices and/or peer groups are a useful part of this feedback loop, as long as they are considered in the context of the market environment and with the limitations of market index and manager database construction.

Inherent to performance comparisons is the reality that portfolios taking greater risk will tend to out-perform less risky investments during bullish phases of a market cycle, but are also more likely to under-perform during the bearish phase.  The reason for focusing on performance comparisons over a full market cycle is that the phases biasing results in favor of higher risk approaches can be balanced with less favorable environments for aggressive approaches to lessen/eliminate those biases.

So, as physicians and other investors, can we eliminate the biases of the market environment by adjusting performance for the risk assumed by the portfolio?  While several interesting calculations have been developed to measure risk-adjusted performance, the unfortunate answer is that the biases of the market environment still tend to have an impact even after adjusting returns for various measures of risk.

However, medical professionals and their advisors will have many different risk-adjusted return statistics presented to them, so understanding the Sharpe ratio, Treynor ratio, Jensen’s measure or alpha, Morningstar star ratings, etc. and their limitations should help to improve the decisions made from the performance measurement feedback loop.

[a] The Treynor Ratio

The Treynor ratio measures the excess return achieved over the risk free return per unit of systematic risk as identified by beta to the market portfolio.  In practice, the Treynor ratio is often calculated using the T-Bill return for the risk-free return and the S&P 500 for the market portfolio.

[b] The Sharpe Ratio

The Sharpe ratio, named after CAPM pioneer William F. Sharpe, was originally formulated by substituting the standard deviation of portfolio returns (i.e., systematic plus unsystematic risk) in the place of beta of the Treynor ratio.  Thus, a fully diversified portfolio with no unsystematic risk will have a Sharpe ratio equal to its Treynor ratio, while a less diversified portfolio may have significantly different Sharpe and Treynor ratios.

***

8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

[c] The Jensen Alpha Measure

The Jensen measure, named after CAPM research Michael C. Jensen, takes advantage of the CAPM equation discussed in the Portfolio Management section to identify a statistically significant excess return or alpha of a portfolio.  The essential idea is that to investigate the performance of an investment manager you must look not only at the overall return of a portfolio, but also at the risk of that portfolio.

For instance, if there are two mutual funds that both have a 12 percent return, a lucid investor will want the fund that is less risky. Jensen’s gauge is one of the ways to help decide if a portfolio is earning the appropriate return for its level of risk. If the value is positive, then the portfolio is earning excess returns. In other words, a positive value for Jensen’s alpha means a fund manager has “beat the market” with his or her stock picking skills compared with the risk the manager has taken.

[d] Database Ratings

The ratings given to mutual funds by databases, such as Morningstar, and various financial magazines are another attempt to develop risk-adjusted return measures.  These ratings are generally based on a ranking system for funds calculated from return and risk statistics.

A popular example is Morningstar’s star ratings, representing a weighting of three, five and ten year risk/return ratings.  This measure uses a return score from cumulative excess monthly fund returns above T-Bills and a risk score derived from the cumulative monthly return below T-Bills, both of which are normalized by the average for the fund’s asset class.  These scores are then subtracted from each other and funds in the asset class are ranked on the difference.  The top 10 percent receive five stars, the next 22.5 percent get four stars, the subsequent 35 percent receive three stars, the next 22.5 percent receive two stars, and the remaining 10 percent get one star.

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

Assessment

Unfortunately, these ratings systems tend to have the same problems of consistency and environmental bias seen in both non-risk adjusted comparisons over 3 and 5 year time periods and the other risk-adjusted return measures discussed above.  The bottom line on performance measurement is that the medical professional should not take the easy way out and accept independent comparisons, no matter how sophisticated, at face value.  Returning to our original rules-of-thumb, understanding the limitations of performance statistics is the key to using those statistics to monitor progress towards one’s goals.

This requires an understanding of performance numbers and comparisons in the context of the market environment and the composition/construction of the indices and peer group universes used as benchmarks.

Another important rule-of-thumb is to avoid projecting forward historical average returns, especially when it comes to strong performance in a bull market environment.  Much of an investment or manager’s performance may be environment-driven, and environments can change dramatically.

Channel Surfing

Have you visited our other topic channels? Established to facilitate idea exchange and link our community together, the value of these topics is dependent upon your input.

ABOUT

Timothy J. McIntosh is Chief Investment Officer and founder of SIPCO.  As chairman of the firm’s investment committee, he oversees all aspects of major client accounts and serves as lead portfolio manager for the firm’s equity and bond portfolios. Mr. McIntosh was a Professor of Finance at Eckerd College from 1998 to 2008. He is the author of The Bear Market Survival Guide and the The Sector Strategist.  He is featured in publications like the Wall Street Journal, New York Times, USA Today, Investment Advisor, Fortune, MD News, Tampa Doctor’s Life, and The St. Petersburg Times.  He has been recognized as a Five Star Wealth Manager in Texas Monthly magazine; and continuously named as Medical Economics’ “Best Financial Advisors for Physicians since 2004.  And, he is a contributor to SeekingAlpha.com., a premier website of investment opinion. Mr. McIntosh earned a Bachelor of Science Degree in Economics from Florida State University; Master of Business Administration (M.B.A) degree from the University of Sarasota; Master of Public Health Degree (M.P.H) from the University of South Florida and is a CERTIFIED FINANCIAL PLANNER® practitioner. His previous experience includes employment with Blue Cross/Blue Shield of Florida, Enterprise Leasing Company, and the United States Army Military Intelligence.

Dr. Jeffrey S. Coons is the Co-Director of Research at Manning & Napier Advisors, Inc. with primary responsibilities focusing on the measurement and management of portfolio risk and return relative to client objectives.  This includes providing analysis across every aspect of the investment process, from objectives setting and asset allocation to on-going monitoring of portfolio risk and return.  Dr. Coons is also member of the Investment Policy Group, which establishes and monitors secular investment trends, macroeconomic overviews, and the investment disciplines of the firm. Dr. Coons holds a doctoral degree in economics from Temple University, graduated with distinction from the University of Rochester with a B.A. in Economics, holds the designation of Chartered Financial Analyst, and is one of the employee-owners of Manning and Napier.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

Sponsors Welcomed

And, credible sponsors and like-minded advertisers are always welcomed.

Support Medical Executive-Post

DAILY UPDATE: Data Breach Up, Novo Nordisk Down as Stock Markets Stumble

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

CITE: https://www.r2library.com/Resource

You might be affected by one of the biggest data breaches ever and not even know it. A recent class action lawsuit filed against Jerico Pictures Inc., a background check company that does business under the name National Public Data, claims that the company was breached by hackers earlier this year.

CITE: https://tinyurl.com/2h47urt5

Here’s where the major benchmarks ended:

  • The SPX dipped 40.5 points (0.8%) to 5,199.5; the Dow Jones Industrial Average® ($DJI) fell 234.2 points (0.6%) to 38,763.45 the NASDAQ Composite ($COMP) fell 171 points (1.1%) to 16,195.8. 
  • The 10-year Treasury note yield (TNX) rose to 3.96%.
  • The Cboe Volatility Index® (VIX) inched up to 27.8, still very elevated.

What’s Up

What’s down

  • Super Micro Computer dropped 20.14% thanks to an earnings miss, as well as the announcement of a 10-for-1 stock split.
  • AirBnB tumbled 13.38% after not only missing analyst estimates last quarter, but warning of slowing demand in the coming quarter.
  • Lyft drove 17.23% lower in spite of strong ridership in the second quarter. Shareholders, however, did not like management’s dour financial forecast for the third quarter.
  • CVS Health sank 3.19% after it slashed its profit guidance for the full year, though it also announced a new cost-cutting program.
  • TripAdvisor took a trip south today, falling 16.61% due to a mixed earnings report and dire warnings of lower revenue in the coming quarter.
  • Amgen stumbled 5% after the biotech company missed Wall Street forecasts in the second quarter.

CITE: https://tinyurl.com/tj8smmes

Novo Nordisk sales thinned on Ozempic earnings miss. Shares of Danish pharmaceutical giant Novo Nordisk sank 8.27% today after the company missed expectations on its sales of popular weight-loss drugs Ozempic and Wegovy. Novo reported $1.7 billion in Wegovy sales, below the $2 billion analysts expected, while Ozempic sales came in $0.2 billion lower than analyst estimates. Overall, the company reported a net profit of $1.86 billion in the second quarter.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

Stock Markets, Magnificent 7, Nikkei and DuckDuckGo

By Staff Reporters

***

***

Stock Markets seesawed up yesterday, making back some of the ground lost to Monday’s sell-off. Analysts say the market could remain volatile until September, when the Fed is widely expected to cut interest rates—barring an emergency cut before then. One of the day’s big winners was Uber, which revved up after smashing Q2 revenue expectations thanks to unexpectedly strong consumer demand.

***

One day after the S&P 500’s worst session since 2022, stocks partially rebounded, putting fears of a recession on hold. Tuesday started well, with Japan’s Nikkei—which had cratered on Monday—logging its best day since 2008, giving US investors some positive energy From there, US stocks, including Magnificent Seven stalwarts like Microsoft and Nvidia, and both major cryptocurrencies, moved up. “Get used to the volatility,” one Bank of America analyst told Bloomberg. The S&P 500 is still up over 10% this year despite this week’s turbulence.

CITE: https://www.r2library.com/Resource

***

Finally, DuckDuckGo might soon get its time to shine. A federal judge just ruled that Google has a monopoly over the search engine business, creating the potential for curbs to its power that could change how you look up people you just met online. Google said it will appeal the ruling, but that’s just on one front. It faces another lawsuit questioning whether it abused its monopoly on online advertising technology.

COMMENTS APPRECIATED

Thank You

***

***

ACCOUNTING: Mark to Market [MTM] Fair Value

***

***

By Staff Reporters

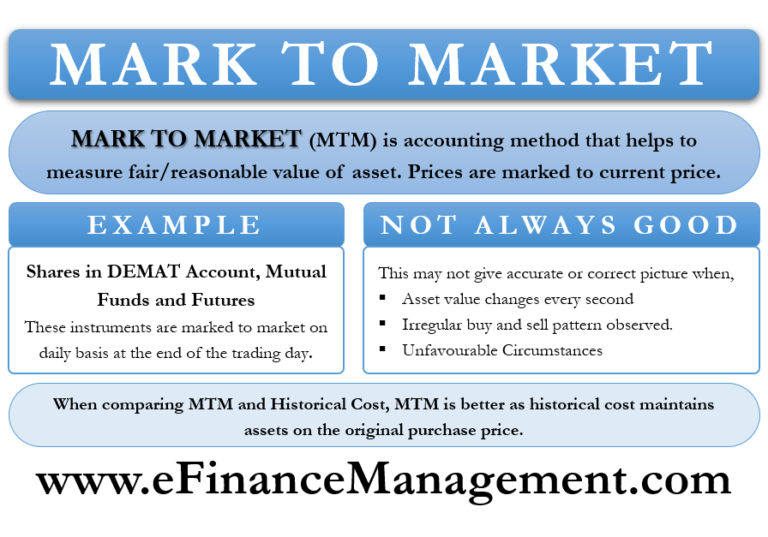
According to Wikipeida, Mark-to-market (MTM or M2M) or fair value accounting is accounting for the “fair value” of an asset or liability based on the current market price, or the price for similar assets and liabilities, or based on another objectively assessed “fair” value.[1] Fair value accounting has been a part of Generally Accepted Accounting Principles (GAAP) in the United States since the early 1990s. Failure to use it is viewed as the cause of the Orange County Bankruptcy,[2][3] even though its use is considered to be one of the reasons for the Enron scandal and the eventual bankruptcy of the company, as well as the closure of the accounting firm Arthur Andersen.[4]

Mark-to-market accounting can change values on the balance sheet as market conditions change. In contrast, historical cost accounting, based on the past transactions, is simpler, more stable, and easier to perform, but does not represent current market value. It summarizes past transactions instead. Mark-to-market accounting can become volatile if market prices fluctuate greatly or change unpredictably. Buyers and sellers may claim a number of specific instances when this is the case, including inability to value the future income and expenses both accurately and collectively, often due to unreliable information, or over-optimistic or over-pessimistic expectations of cash flow and earnings.[5]

Stock brokers allow their clients to access credit via margin accounts. These accounts allow clients to borrow funds to buy securities. Therefore, the amount of funds available is more than the value of cash (or equivalents). The credit is provided by charging a rate of interest and requiring a certain amount of collateral, in a similar way that banks provide loans. Even though the value of securities (stocks or other financial instruments such as options) fluctuates in the market, the value of accounts is not computed in real time. Marking-to-market is performed typically at the end of the trading day, and if the account value decreases below a given threshold (typically a ratio predefined by the broker), the broker issues a margin call that requires the client to deposit more funds or liquidate the account.

COMMENTS APPRECIATE

Thank You

***

***

About Securities Order and Position Types

A Primer for Physician Investors and Medical Professionals

By: DR. David Edward Marcinko; MBA, MEd, CMP™

[Editor-in-Chief] http://www.CertifiedMedicalPlanner.org

[PART 6 OF 8]

BC Dr. Marcinko

NOTE: This is an eight part ME-P series based on a weekend lecture I gave more than a decade ago to an interested group of graduate, business and medical school students. The material is a bit dated and some facts and specifics may have changed since then. But, the overall thought-leadership information of the essay remains interesting and informative. We trust you will enjoy it.

Introduction

At this point  in our long ME-P essay, it is important to understand the different types of orders and positions that can be used to buy and sell securities from the specialist.

Market Order:

A market order is an order to be executed at the best possible price at the time the order reaches the floor. Market orders are the most common of all orders. The greatest advantage of the market order is speed. The doctor specifies no price in this type of order, he merely orders his broker to sell or buy at the best possible price, regardless of what it may be. The best possible price on a buy is the lowest possible price. The best possible price on a sell is the highest possible price. In other words, if a medical professional customer is buying, he logically wants to pay as little as possible, but he is not going to quibble over price. He wants the stock now, whatever it takes to get it. If he’s a seller, the doctor client wants to receive as much as possible, but will not quibble, he wants out, and will take what he can get, right now. No other type of order can be executed so rapidly.

Some market orders are executed in less than one minute from the time the broker phones in the order. Because the investor has specified no price, a market order will always be executed. The doctor is literally saying, “I will pay whatever it takes, or accept whatever is offered”.

Limit Order:

The chief characteristic of a limit order is that the doctor decides in advance on a price at which he decides to trade. He believes that his price is one that will be reached in the market in reasonable time. He is willing to wait to do business until he has obtained his price even at the risk his order may not be executed either in the near future or at all. In the execution of a limit order, the broker is to execute it at the limit price or better. Better, means that a limit order to buy is executed at the customer’s price limit or lower, in a limit order to sell, at price limit or higher. If the broker can obtain a more favorable price for his doctor customer than the one specified, he is required to do so.

Order Length:

Now, even though the doctor has given his price limit, we need to know the length of effectiveness of the order. Is the order good for today only? If so, it is a day order, it automatically expires at the end of the day.  Alternatively, the doctor may enter an open or, “good until canceled” order. This type of order is used when the doctor believes that the fluctuations in the market price of the stock in which he’s interested will be large enough in the future that they will cause the market price to either fall to, or rise to, his desired price, i.e. his limit price. He is reasonably sure of his judgment and is in no hurry to have/his order executed. He knows what he wants to pay or receive and is willing to wait for an indefinite period.

Years ago, such orders were carried for long periods of time without being reconfirmed. This was very unsatisfactory for all parties concerned.  A doctor would frequently forget his order existed and, if the price ever reached his limit and the order was executed, the resulting trade might not be one he wished to make. To avoid the problem, open (GTC) orders must be reconfirmed by the doctor customer each six months. Does that mean six months after the order is entered? …No! The exchange has appointed the last business day of April and the last business day of October as the two dates per year when all open orders must be reconfirmed.

Example: Dr. Smith wants to buy 100 shares of XYZ. The price has been fluctuating between 50 and 55. He places a limit order to buy at 51, although the current market price is 54. Limit orders to buy (buy limit orders) are always placed below the current market. To do otherwise makes no sense. It is possible that, within a reasonable time, the price will drop to 51 and his broker can purchase the stock for him at that price. If the broker can purchase the stock at less that 51, that would certainly be fine with the doctor customer since he wants to pay no more than 51. A sell limit order works in reverse and is always placed above the current market price.

Example: Dr. Smith wants to sell 100 shares of XYZ stock. The order is 54. A sell limit order is place at 56. Sell limit orders are always placed above the market price. As soon as the pride rises to 56, if it ever does, the broker will execute it at 56 or higher. In no case will it be executed at less than 56.

The advantage of the limit order is that the doctor has a chance to buy at less or to sell at more than the current market price prevailing when he placed the order. He assumes that the market price will become more favorable in the future than it is at the time the order is placed. The word” chance ” is important. There is also the “chance” that the order will not be executed at all. The doctor just mentioned, who wanted to buy at 51, may never get his order filled since the price may not fall that low.  If he wanted to sell at 56, the order may also not ever be executed since it might not rise that high during the time period the order is in effect.

Stop Orders:

A very important type of order is the stop order, frequently called a stop-loss order. There are two distinct types of stop orders. One is the stop order to sell, called a sell stop, and the other is a stop order to buy, called a buy stop. Either type might be thought of as a suspended market order; it goes into effect only if the stock reaches or passes through a certain price.

The fact that the market price reaches or goes through the specified stop price does not mean the broker will obtain execution at the exact stop price. It merely means that the order becomes a market order and will be executed at the best possible price thereafter. The price specified on a stop order bears a relationship to the current market price exactly opposite to that on a limit order. Whereas a sell limit is placed at a price above the current market, a sell stop is placed at a price below the current market. Similarly, while a buy limit is placed at a price below the current market, a buy stop is placed at a price above the current market. Why would a doctor investor use a stop order?

There are two established uses for stop orders. One of them might be called protective, the other might be called preventive.

Protective: This order protects a doctors’ existing profit on a stock currently owned.

For example, a doctor purchases a stock at 60. It rises to 70. He has made a paper profit of $10 per share. He realizes that the market may reverse itself. He therefore gives his broker a stop order to sell at 67. If the reversal does occur and the price drops to 67 or less, the order immediately becomes a market order. The stock is disposed of at the best possible price. This may be exactly 67, or it may be slightly above or below that figure. Why? …Because what happened at 67 was that his order became a market order; the price he actually received was dependent upon the next activity in the market. Let us suppose that the sale was made at 66 1/2. The doctor customer made a gross profit of 6 1/2 points per share on his original purchase. Without the stop order, the stock may have dropped considerably below that before the customer could have placed a market order and his profit might have been less or, in fact, he might have even sold at a loss.

Preventive:

A doctor purchases 100 shares of a stock at 30. He obviously anticipates that the price of the stock will rise in the near future (why else would he buy?). However, he realizes that his judgment may be faulty. He therefore, at the time of purchase, places a sell stop order at a price somewhat below his purchase price, for example, at 28. As yet, he has made neither profit nor loss; he’s merely acting to prevent a loss that might follow if he made the wrong bet and the stock does fall in price. If the stock does drop, the doctor knows that once it gets as low as 28, a market order will be turned in for him and, therefore, he will lose only 2 points or thereabout. It might have been much more had he not used the sell stop.

***

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

Miscellaneous Orders and Positions

Beside market, limit  and stop orders, there are some other miscellaneous orders to know.

A stop limit order is a stop order that, once triggered or activated, becomes a limit order. Realize that it is possible for a stop limit to be triggered and not executed, as the limit price specified by the doctor may not be available.

In addition, there are all or none and fill or kill orders, and even though both require the entire order to be filled, there are distinct differences. An all or none (AON) is an order in which the broker is directed to fill the entire order or none of it. A fill or kill (FOK) is an order either to buy or to sell a security in which the broker is directed to attempt to fill the entire”‘ amount of the order immediately and in full, or that it be canceled.

The difference between an all or none and a fill or kill order is that with an all or none order, immediate execution is not required, while immediate execution is a critical component of the fill or kill. Be cause of the immediacy requirement, FOK orders are never found on the specialist’s book. Another difference is that AON orders are only permitted for bonds, not stocks, while FOK orders may be used for either.

Also, there exists an immediate or cancel order (IOC), which is an order to buy or sell a security in which the broker is directed to attempt to fill immediately as much of the order as possible and cancel any part remaining. This type of order differs from a fill or kill order which requires the entire order to be filled. An IOC order will permit a partial fill. Because of the immediacy requirement, IOC and FOK orders are never found on the specialist’s book.

Long and Short Positions

A long buy position means that shares are for sale from a market makers inventory, or owned by the medical investor, outright. Market makers take long positions when customers and other firms wish to sell, and they take short positions when customers and other firms want to buy in quantities larger than the market maker’s inventory. By always being ready, willing, and able to handle orders in this way, market makers assure the investing public of a ready market in the securities in which they are interested. When a security can be bought and sold at firm prices very quickly and easily, the security is said to have a high degree of liquidity, also known as marketability.

A short position investor seeks to make a profit by participating in the decline in the market price of a security.

Now, let’s see how these terms, long and short, apply to transactions by medical investors, rather than market makers, in the securities markets.

When a doctor buys any security, he is said to be taking a long position in that security. This means the investor is an owner of the security. Why does a doctor take a long position in a security? Beside, receiving dividend income, to make a profit from an increase in the market price. Once the security has risen sufficiently in price to satisfy the investor’s profit needs, the investor will liquidate his long position, or sell his stock. This would officially be known as a long sale of stock, though few people in the securities business use the label “long sale”. This is the manner in which the above investor had made a profit is the traditional method used; buy low, sell high.

Let’s look at an actual investment in General Motors to investigate this principle further. A medical investor has taken a long position in 100 shares of General Motors stock at a price of $70 per share. This means that the manner in which he can do that is by placing a market order which will be executed at the best “available market price at the time, or by the / placing of a buy limit order with a limit price of $70 per share. The investor firmly believes, on the basis of reports that he has read about the automobile industry and General Motors specifically, that at $70 a share, General Motors is a real bargain. He believes that based on its current level of performance, it should be selling for a price of between $80 and $85 per share. But, the doctor investor has a dilemma. He feels certain that the price is going to rise but he cannot watch his computer, or call his broker, every hour of every day. The reason he can’t watch is because patients have to be seen in the office. The only people who watch a computer screen all day are those in the offices of brokerage firms (stock broker registered representatives), and doctor day traders, among others.

In the above example, with a sell limit order, if the doctor investor was willing to settle for a profit of $12 per share, what order would he place at this time? If you said, “sell at $82 good ’til canceled”, you are correct. Why GTC rather than a day order? Because our doctor investor knows that General Motors is probably not going to rise from $70 to $82 in one day. If he had placed an order to sell at $82 without the GTC qualification, his order would have been canceled at the end of this trading day. He would have had to re-enter the order each morning until he got an execution at 82. Marking the order GTC (or open) relieves him of any need to replace the order every morning. Several weeks later, when General Motors has reached $82 per share in the market, his order to sell at 82 is executed. The medical investor has bought at 70 and sold at 82 and realized a $12 per share profit for his efforts.

Let’s suppose that the medical investor, who has just established a $12 per share profit, has evaluated the performance of General Motors common stock by looking at the market performance over a period of many years. Let’s further assume that the investor has found by evaluating the market price statistics of General Motors is that the pattern of movement of General Motors is cyclical. By cyclical, we mean that it moves up and down according to a regular pattern of behavior. Let’s say the investor has observed that in the past, General Motors had repeated a pattern of moving from prices in the $60 per share range as a low, to a high of approximately $90 per share. Further, our investor has observed that this pattern of performance takes approximately 10 to l2 months to do a full cycle; that is, it moves from about 60 to about 90 and back to about 60 within a period of roughly l2 months. If this pattern repeats itself continually, the investor would be well advised to buy the stock at prices in the low to mid 60’s hold onto it until it moves well into the 80’s, and then sell his long position at a profit. However, what this means is that our investor is going to be invested in General Motors only 6 months of each year. That is, he will invest when the price is low and, usually within half a year, it will reach its high before turning around and going back to its low again. How can the doctor investor make a profit not only on the rise in price of General Motors in the first 6 months of the cycle, but on the fall in price of General Motors in the second half of the cycle? One technique that is available is the use of the short sale.

The Short Sale

If a doctor investor feels that GM is at its peak of $ 90 per share, he may borrow 100 shares from his brokerage firm and sell the 100 shares of borrowed GM at $ 90. This is selling stock that is not owned and is known as a short sale. The transaction ends when the doctor returns the borrowed securities at a lower price and pockets the difference as a profit. In this case, the doctor investor has sold high, and bought low.

Odd Lots

Most of the thousands of buy and sell orders executed on a typical day on the NYSE are in 100 share or multi-100 share lots. These are called round lots. Some of the inactive stocks traded at post 30, the non-horseshoe shaped post in the northwest corner of the exchange, are traded in 70 share round lots due to their inactivity. So, while a round lot is normally 700 shares, there are cases where it could be 10 shares. Any trade for less than a round lot is known as an odd lot. The execution of odd lot orders is somewhat different than round lots and needs explanation.

When a stock broker receives an odd lot order from one of his doctor customers, the order is processed in the same manner as any other order. However, when it gets to the floor, the commission broker knows that this is an order that will not be part of the regular auction market. He takes the order to the specialist in that stock and leaves the order with the specialist. One of the clerks assisting the specialist records the order and waits for the next auction to occur in that particular stock. As soon as a round lot trade occurs in that particular stock as a result of an auction at the post, which may occur seconds later, minutes later, or maybe not until the next day, the clerk makes a record of the trade price.

Every odd lot order that has been received since the last round lot trade, whether an order to buy or sell, is then executed at the just noted round lot price, the price at which the next round lot traded after receipt of the customer’s odd lot order, plus or minus the specialist’s “cut “.  Just like everything else he does, the specialist doesn’t work for nothing. Generally, he will add 1/8 of a point to the price per share of every odd lot buy order and reduce the proceeds of each odd lot sale order by 1/8 per share. This is the compensation he earns for the effort of breaking round lots into odd lots. Remember, odd lots are never auctioned but, there can be no odd lot trade unless a round lot trades after receipt of the odd lot order.

Part 5 of 8: About Securities “Shelf Registration”

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct DetailsProduct Details

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™
Product DetailsProduct Details

Product Details

***

DAILY UPDATE: New Coronavirus Variant and Stock Markets Both Up

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***
http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

Health tech startup Guidehealth, which assists health systems with value-based care coordination, has raised $14 million in its seed round to make further investments in technology.


Clover Health reported a net income of $7.2 million during the second quarter and raised its full-year guidance.


And … Tenet Healthcare is selling five Alabama hospitals to Orlando Health and is entering into a new revenue cycle management arrangement through Conifer Health Solution

CITE: https://www.r2library.com/Resource

What’s up

What’s down

CITE: https://tinyurl.com/2h47urt5

Here’s where the major stock market benchmarks ended:

  • The S&P 500 index (SPX) rose 53.7 points (1%) to 5,240.03; the Dow Jones Industrial Average® ($DJI) climbed 294.39 points (0.76%) to 38,997.66; the NASDAQ Composite ($COMP) advanced 166.77 points (1%) to 16,366,85.
  • The 10-year Treasury note yield (TNX) increased about 10 basis points to 3.88%.
  • The CBOE Volatility Index® (VIX) ended at 27.7, well above lows below 11 last month.

CITE: https://tinyurl.com/tj8smmes

A new coronavirus variant named KP.3.1.1 has risen to dominance in the U.S., almost doubling in prevalence in just two weeks, the Centers for Disease Control and Prevention reports. Experts are warning that the new variant—which, as of August 3, accounts for more than 1 in 4 U.S. COVID-19 cases—is “more of a challenge” to our immune systems compared to previous variants.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***
***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

RSI: Relative Strength Index [Stock Markets]

By Staff Reporters

http://www.MARCINKOAssociates.com

***
***

The relative strength index (RSI) is a technical indicator used in the analysis of financial markets. It is intended to chart the current and historical strength or weakness of a stock or market based on the closing prices of a recent trading period. The indicator should not be confused with relative strength.

The RSI is classified as a momentum oscillator, measuring the velocity and magnitude of price movements. Momentum is the rate of the rise or fall in price. The relative strength RS is given as the ratio of higher closes to lower closes. Concretely, one computes two averages of absolute values of closing price changes, i.e. two sums involving the sizes of candles in a candle chart. The RSI computes momentum as the ratio of higher closes to overall closes: stocks which have had more or stronger positive changes have a higher RSI than stocks which have had more or stronger negative changes.

The RSI is most typically used on a 14-day time frame, measured on a scale from 0 to 100, with high and low levels marked at 70 and 30, respectively. Short or longer time frames are used for alternately shorter or longer outlooks. High and low levels—80 and 20, or 90 and 10—occur less frequently but indicate stronger momentum.

The relative strength index was developed by J. Welles Wilder and published in a 1978 book, New Concepts in Technical Trading Systems, and in Commodities magazine (now Modern Trader magazine) in the June 1978 issue. It has become one of the most popular oscillator indices.

The RSI provides signals that tell investors to buy when the security or currency is oversold and to sell when it is overbought.

RSI with recommended parameters and its day-to-day optimization was tested and compared with other strategies in Marek and Šedivá (2017). The testing was randomized in time and companies and showed that RSI can still produce good results; however, in longer time it is usually overcome by the simple buy-and-hold strategy.

***
***

COMMENTS APPRECIATED

Thank You

***

DAILY UPDATE: Google Monopoly, Mag 7 Still Down as VIX “Fear Index” Rises and Stock Markets Plunge!

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

CITE: https://www.r2library.com/Resource

A federal judge ruled that Google engaged in illegal practices to preserve its search engine monopoly, delivering a major antitrust victory to the Justice Department in its effort to rein in Silicon Valley technology giants. Google, which performs about 90 percent of the world’s internet searches, exploited its market dominance to stomp out competitors, U.S. District Judge Amit P. Mehta said in the long-awaited ruling.

CITE: https://tinyurl.com/2h47urt5

Stat: $900 billion. That’s the potential market value loss of the Magnificent Seven tech companies as investors shed tech stocks. The selloff comes as investors are looking for safer bets in the event of a recession. (Reuters)

CITE: https://tinyurl.com/tj8smmes

Here’s where the major benchmarks ended:

  • The S&P 500 index tanked 160.23 points (–3.00%) to 5,186.33; the Dow Jones Industrial Average® ($DJI) plunged 1,033.99 points (–2.60%) to 38,703.27; the NASDAQ Composite plummeted 576.08 points (–3.43%) to 16,200.08.
  • The 10-year Treasury note yield (TNX) dropped to 3.78%, the lowest close since June 2023.
  • The CBOE Volatility Index® (VIX) ended at 37.04, a four-year high but well-off intraday peaks above 60.

Today, the VIX reached levels not seen since early 2020 during the pandemic panic. This type of volatility can suggest oversold conditions. A higher VIX, sometimes called the “fear index,” reflects uncertainty and can suggest quicker, more intense market swings.

What’s up

What’s down

  • Apple stumbled 4.82% after Warren Buffett’s Berkshire Hathway revealed it has cut its position in the tech company by nearly 50%.
  • Nvidia fell 6.36% after a report this weekend revealed that its brand new chips will be delayed by three months or more due to design flaws.
  • Tesla sank 4.23% due to concerns about the auto maker’s global growth, despite Elon Musk’s recent positivity.
  • Intel continued to crumble, sliding 6.38% as the after-effects of its terrible second-quarter earnings report continue to be felt.
  • Bitcoin-related stocks plummeted today as cryptocurrencies were unable to avoid a major selloff. Coinbase plunged 7.32%, while MicroStrategy dropped 9.60%, and even Robinhood tumbled 8.17%.

Visualize: How private equity tangled banks in a web of debt, from the Financial Times.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***
***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

KEY PRINCIPLES: Assessing Medical Practice Financial Value via U.S.P.A.P. Rules

****

Invite Dr. Marcinko | The Leading Business Education Network for Doctors,  Financial Advisors and Health Industry Consultants

BY DR. DAVID EDWARD MARCINKO MBA CMP®

https://certifiedmedicalplannerdotorg1.files.wordpress.com/2012/03/cmp-logo17.jpg

SPONSOR: http://www.CertifiedMedicalPlanner.org

CITE: https://www.r2library.com/Resource/Title/082610254

***
When it comes to purchasing a medical practice, there are a variety of factors that one must consider in evaluating the worth of the practice. Assessing the value of a practice is fraught with potential landmines if one does not go into the process with a strong understanding of some key principles to medical practice valuation.

   According to the Dictionary of Health Economics and Finance, practice valuation is the “formal process of determining the worth of healthcare or other medical business entity at a specific point in time and the act or process of determining fair market value.” Fair market value is defined as “ … the price at which a willing buyer will buy and a willing seller will sell an asset in an open free market with full disclosure.”

   The Internal Revenue Service (IRS) Revenue Ruling 59-60 clearly states that fair market value “is essentially a future prophecy and must be based on facts available at the required date of appraisal.”

   Unfortunately, one cannot directly observe the value of a medical practice as there are a number of underlying issues. Obviously, the buyer and seller are pursuing opposite objectives, and this reality is not necessarily conducive to facilitating clarity on those issues.

   Accordingly, let us consider a few mistakes that are commonly made by physicians who are considering the purchase of a medical practice.

A Guide To The Myths And Realities Of Medical Practice Valuation

   • Valuations are material representations providing a range of transferable worth.
   • Valuations are reproducible estimates based on economic assumptions.
   • Valuations are not “back of the envelope multiples” using specious benchmarks.
   • Valuations are defensible and should be “signed off” by the completing firm attesting to origination guidelines and in accordance with the Uniform Standards of Professional Appraisal Practice (USPAP) and IRS formats as needed.
   • Financial accounting value (book value) is not fair market value.
   • Professional valuators represent only one party. The buyer or seller-owner is the client.
   • Unbiased valuators do not provide financing or equity participation schemes.

Knowing The Distinctions Among Engagement Types

   The Institute of Medical Business Advisors uses three levels that approximate engagement types for the industry. These levels are comprehensive valuation, limited valuation and ad-hoc valuation.

   A comprehensive valuation is an extensive service designed to provide an unambiguous opinion of the value range. It is supported by all procedures that valuators deem relevant with mandatory onsite review. This gold standard is suitable for contentious situations like divorce, partnership dissolution, estate planning and gifting, etc. The written opinion of value is applicable for litigation support activities like depositions and trial. It is also useful for external reporting to bankers, investors, the public and IRS, etc.

   A limited valuation lacks additional suggested USPAP procedures. It is considered to be an “agreed upon procedure,” which is used in circumstances in which the client is the only user. For example, one may use the limited valuation when updating a buy-sell agreement or when putting together a practice buy-in for a valued associate. This limited valuation would not be for external purposes. No onsite visit is needed. A formal opinion of value is not rendered.

   An ad-hoc valuation is a low level engagement that provides a gross and non-specific approximation of value based on limited limited parameters or concerns by involved parties. Neither a written report nor an opinion of value is rendered. The ad-hoc valuation is often used periodically as an internal organic growth/decline gauge.

Are You Following Industry Standards And Rules?

   Specifically, when it comes to USPAP transactions involving physician practices, the following points are implied by the industry and the IRS.

   • Discounted cash flow analysis is the most relevant income approach and must be done on an “after-tax” basis. It generally produces a higher value but is costly, detail-oriented and time consuming.
   • Project practice collections based on reasonable assumptions for the practice and market, etc.
   • Physician compensation is based on market rates consistent with age, experience and productivity.
   • Majority (control) premiums and minority (lack of control) discounts are also to be considered. A majority premium is the amount paid to gain enough ownership to set policies, direct operations and make decisions for the practice. A minority discount for partial ownership does not allow this power. Thus, majority ownership is valuated higher than minority ownership purchase.

What About Personal Goodwill And Practice Goodwill?

   Goodwill represents the difference between practice purchase price and the value of the net assets. Personal goodwill results from the charisma, skills and reputation of a specific doctor. These attributes accrue solely to the individual, are not transferable and cannot be sold. Personal goodwill has little or no economic value.

   Transferable medical practice goodwill has value, may be transferred and is defined as the unidentified residual attributes that contribute to the propensity of patients and managed care contracts (and their revenue streams) to return in the future.

   However, bear in mind that the Goodwill Registry, an older source used to determine the average percentage of revenue contributed to practice goodwill, has sparse to no podiatry input, may be dated for some specialties and leads to abnormally high values.

   In addition to various multiple factors, one must also appreciate the impact of a changing environment and practice transfer in a local market, which can augment or blunt goodwill value. It is also important to determine whether patients or HMOs return because of true goodwill or are mandated to do so by contractual obligations.

   Now to further confuse the issue, how each kind of goodwill is allocated in situations like divorce depends on state law. For example, some courts weigh in on the apportionment of both kinds of goodwill, other courts exclude both kinds of goodwill and other courts pursue a case-by-case approach.

Understanding ‘Excess Earnings Capitalization’ And Compensation Issues

   Another way to determine goodwill value is through “excess earnings capitalization.” This economic method looks at the difference between salary and what you would have to pay a comparable doctor replacement.

   As an example, when you subtract the numbers and divide the result by 20 percent, an important percentage referred to as the capitalization rate emerges. The final number gives a dollar value for practice goodwill. Courts seem to prefer this method in divorce situations because it tends to reflect a practice’s current value.

   Regardless of the practice business model, physician compensation is inversely related to practice value. In other words, the more a doctor takes home in above average salary, the less the practice is generally worth and vice versa.

Emphasize Practice Specifics Over Benchmarks And Formulas

   In the stable economic past, physicians may have used industry benchmarks as quick and inexpensive substitutes for professionally prepared valuations. However, this practice can be fraught with peril if challenged. The courts seem to frown on this simplistic and dated methodology. Moreover, generic benchmark formulas assume a financial statement reporting standard that just does not exist with contemporary professional valuations.

   Therefore, almost every competitive issue that impacts value should be addressed with each practice engagement. This includes but is not limited to:

   • contemporary dislocations by third parties, Medicare and commercial payers;
   • retail clinics and changes in supply/ demand and specialty trends;
   • the rise of ambulatory surgery centers, walk-in clinics and specialty hospitals;
   • outsourced care and medical tourism;
   • alterations in resource based-relative value units, ambulatory payment classifications (APCs), diagnosis-related groups (DRGs) and newer Medicare-severity diagnosis-related groups (MS-DRGs); and
• the Medicare Modernization Act, HIPAA, OSHA, the EEOC and other regulations.

   One must also consider the impact of current employee trends to high-deductible health care plans and private concierge medicine. Another consideration is employer shifts away from defined benefits plans to defined contribution plans.

Aggregating Or ‘Normalizing’ Financial Information: What You Should Know

   In addition to possibly conducting employee interviews, one must gather appropriate financial information in order to properly value a practice. As a starting point, interested physician buyers should be able to see the following information for the most recent three-year period.

   • Practice (corporate) tax returns
   • Equipment/automobile leasing and/or tax depreciation schedules
   • Accounts receivable aging schedule
   • Consolidated financial statements (P&L, cash flow, balance sheet and retained earnings)
   • Prior buy-sell and/or non-compete agreements

   It is especially important to eliminate one-time, non-recurring practice expenses. These are adjusted for excessive or below normal expenses on the profit and loss statement. Such “normalization” can produce a big surprise for benchmark proponents and formula-driven advocates when a selling doctor runs personal expenditures through the practice that a buyer or court would not consider legitimate. Of course, one is less likely to encounter such shenanigans when the valuation is conducted according to professional USPAP and IRS style guidelines.

   For example, we recall one doctor who painted his home and wrote it off as a valid business expense. Deleting other major expenses such as country club memberships make a practice look more profitable. This is good news if you are selling it. It is bad news if you are getting a divorce.

   Conversely, you may have to defend legitimate business expenses that an appraiser may seek to normalize. For example, doctors may pay for a vehicle through their practice. If they use the vehicle to travel between multiple offices and hospitals, the expense may be legitimate.

   Also realize that the appraiser may also add expenses that have not been incurred. For example, the appraiser may add an office manager’s salary if your spouse is in that role for free. This produces a lower appraised value and is common in small podiatry practices. Honorarium is another example that does not figure into value calculations.

   Of course, normalization is a sophisticated and time intensive process. However, the expert earns his or her professional fee, and defends the resulting valuation range when challenged.

Keys To Selecting The Right Valuator Professional

   The most important credentials to look for are fiduciary level experience, specificity and independence. Some doctors mistakenly turn to those who may have never appraised a practice before. Just because an appraiser has initials behind his or her name, it does not mean he or she understands the peculiarities of medical specialties. Agents, brokers, solicitors and other intermediaries are not fiduciaries.

   Physicians looking to assess a practice for possible sale/purchase should only select an independent health economist, who will be your advocate under Securities Exchange Commission (SEC), IRS or other relevant managerial accounting guidelines.

   Moreover, be very wary if the valuation is not done in an independent manner or, worse, performed for both parties simultaneously.

Essential Insights On Professional Fees And What You Can Expect

   Of course, it is almost impossible to answer concerns regarding fees without specific information. The cost of a valuation can range from $0 to $50,000 for an onsite team of experts for behemoth practices and ambulatory surgery centers. Keep in mind that in most cases you want to ensure the value determination will stand up to IRS scrutiny so the $0 rule of thumb approach is not an option.

   However, most reputable firms use a blended fee schedule of fixed and hourly rates (plus expenses). Internists should expect to spend approximately $5,000 to $10,000 for an average sized practice and a limited appraisal that is completely suitable for most internal activities.

   External appraisals or poorly aggregated financial information, onsite reviews and litigation support services incur additional costs. However, most doctors find the money well spent. Expect to pay a retainer and sign a formal professional engagement letter.

   Finally, once the practice price is agreed upon, sales contract terms and agreements present a plethora of financing challenges for both parties to consider. For example, one must negotiate bank loans (if they are even available), payment rates and length, personal promissory guarantees, down payment offsets, earn-out arrangements and Uniform Commercial Codes.

Final Notes

   Do not be surprised if a sales broker does not consider the aforementioned issues as the modern health era emerges. Most agent-appraisers are predominantly concerned with earning commissions by working both transaction parties and may not represent your best interests. Also be aware that they are usually not obliged to disclose conflicts of interest and do not provide testimony as a court approved expert witness.

   However, it is a fait accompli that medical practice worth is presently deteriorating. As the population ages and third-party reimbursements plummet, doctors are commoditized and traditional retail medicine is replaced by more efficient wholesale business models like workplace health clinics. The subprime mortgage default fiasco, credit freeze, potential tax reform law expiration, the ACA, VBC, capitation payments and the political specter of a nationalized healthcare system only add fuel to the macroeconomic fires of uncertainty. Do not forget the corona pandemic.

   As a result, a good medical practice is no longer good business necessarily and retiring doctors can no longer automatically expect to extract premium sales prices. Moreover, uninformed young physicians should not be goaded to overpay.

COMMENTS APPRECIATED.

Subscribe to the Medical Executive Post

Thank You

The Author

Dr. Marcinko is a nationally known speaker and the founding partner of the iMBA Inc and http://www.MedicalExecutivePost.com He is also the Academic Provost for http://www.CertifiedMedicalPlanner.org

***

***
***
HEALTH ECONOMICS: Podcast and Research Paper Presentations

By Staff Reporters

***

***

RESEARCH PAPER: https://scholar.harvard.edu/files/mankiw/files/economics_of_healthcare.pdf

PODCAST: https://tinyurl.com/wdyk65mw

CITE: https://www.r2library.com/Resource

COMMENTS APPRECIATED

Thank You

***
***

DAILY UPDATE: Turn Key Health, Intel, Coke and Eli Lilly

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***
http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

The FDA said shortages of Eli Lilly’s popular weight loss and diabetes drugs are over.

Coca-Cola must pay $6 billion in back taxes and interest to the Internal Revenue Service, a federal tax court ruled. Coke is appealing but will pay the bill for now.

CITE: https://www.r2library.com/Resource

Stat: 40.1%. That’s the percentage of people in the US who said they had “a lot of trust” in physicians and hospitals in January 2024, down from 71.5% in April 2020. (JAMA Network Open)

Quote: “We can usher people here and they can get the help that they need because the hospitals are clearly overwhelmed.”—Yolanda Gales, a program director with a Maryland County mobile crisis response team, on the opening of the county’s first 24/7 mental health centers (the Washington Post)

Read: One report says that dozens of incarcerated patients died while under the care of Turn Key Health Clinics. (the Marshall Project)

Careers in care: Indeed has a dedicated job board for healthcare pros. It features employers with top company ratings for your perusing pleasure. Check it out.*

CITE: https://tinyurl.com/2h47urt5

Stocks plunged Friday as an unexpectedly bleak jobs report had investors second-guessing the Fed’s decision to wait until September to cut interest rates. Intel suffered its worst drop in 50 years and traded at its lowest price since 2013 after it missed on earnings, announced major layoffs, and suspended its dividend.

CITE: https://tinyurl.com/tj8smmes

Visualize: How private equity tangled banks in a web of debt, from the Financial Times.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***
***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

RECESSION INDICATOR: Inverted Yield Curve?

By Staff Reporters

***

***

When economic trouble and/or uncertainty is brewing, it’s not uncommon for the US Treasury yield curve to flatten or even invert. A yield curve inversion, like we’re experiencing now, involves short-term-maturing bonds sporting higher yields than longer-dated Treasury bonds. It’s an indication that investors are worried about the U.S. economic outlook.

For the past 64 years, the Federal Reserve Bank of New York has used the Treasury yield spread between the 10-year bond rate and three-month bond rate to calculate the probability of a U.S. recession occurring within the next 12 months. Over these 64 years, the probability of a recession has topped 25% a dozen times and 40% on eight occasions. 

With the exception of a peak probability of a recession of 41.14% in October 1966, the New York Fed’s recession-forecasting tool hasn’t been wrong if it’s surpassed 40%. In other words, if the New York Fed’s recession probability indicator surpasses 40%, we’ve had a recession within 12 months, without fail, for more than a half-century.

In December 2022, this recession probability tool hit 47.31%. That’s the highest reading since 1981, and a very clear indication that economic activity is expected to slow at some point in 2024?

***

***

COMMENTS APPRECIATED

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

ORDER: https://www.routledge.com/Comprehensive-Financial-Planning-Strategies-for-Doctors-and-Advisors-Best/Marcinko-Hetico/p/book/9781482240283

***

COMMENTS APPRECIATED

Thank You

***

FINANCIAL EDUCATION PODCAST: CMPs™ are In … Are CPAs Out?

CERTIFIED MEDICAL PLANNER

By Staff Reporters

SPONSOR: http://www.CertifiedMedicalPlanner.og

***

Statistics: 7.4%. That’s the percentage drop in students who graduated with a degree in accounting in the 2021–2022 school year than the year before. Low starting salaries, heavy workloads, and uncertainty around AI are driving the exodus of students from choosing accounting degrees. (the Wall Street Journal).

MORE: https://www.wsj.com/lifestyle/careers/accounting-salary-cpa-shortage-dec2caa2?utm_campaign=mb&utm_medium=newsletter&utm_source=morning_brew

PODCAST: https://www.ted.com/talks/dan_bricklin_meet_the_inventor_of_the_electronic_spreadsheet

***
COMMENTS APPRECIATED
Thank You

***

***

DAILY UPDATE: Wells Fargo and Record Stock Market Sell Off

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

Here’s where the major benchmarks ended:

  • The S&P 500® (SPX) index dropped 100.12 points (-1.8%) to 5,346.56, and finished down 2.1% for the week; the Dow Jones Industrial Average® ($DJI) dropped 610.71 points (-1.5%) to 39,737.26, and finished down 2.1% for the week; the NASDAQ Composite®($COMP) fell 417.98 points (-2.4%) to 16,776.16, and ended down 3.4% for the week.  
  • The 10-year Treasury note yield (TNX) fell to 3.79%, the lowest close since last December 27.
  • The CBOE Volatility Index® (VIX) rose to 23.66, the highest close since March 2023 after topping 29, a nearly two-year high, intraday.

CITE: https://www.r2library.com/Resource

What’s up

What’s down

CITE: https://tinyurl.com/2h47urt5

Wells Fargo wealth management client is suing the company for alleged breach of fiduciary duty related to its cash sweep program, which pays customers interest rates as low as 0.05% on their uninvested cash.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

“Triple Entry Accounting”

What it is – How it works?

[By staff reporters]

The term “Triple Entry Accounting,” was first used by Ian Grigg, financial cryptographer, and described in his paper published in 2005, three years before the emergence of Bitcoin and its underlying Blockchain protocol.

Here is the original historical article on “Triple Entry Accounting” by Grigg:

LINK: https://nakamotoinstitute.org/triple-entry-accounting/

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Book Marcinko: https://medicalexecutivepost.com/dr-david-marcinkos-bookings/

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, IT, business and policy management ecosystem.

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

Accounting -VERSUS- Economic Profit

Yes – There is A Difference

[By staff reporters]

***

***

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

DAILY UPDATE: Intel, Colon Cancer, Fewer Cardiologists and UnitedHealth Tactics as the Stock Markets Tank!

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

***

Stat: $895. That’s the out-of-pocket cost for a blood test that screens for colon cancer, which may receive more widespread insurance coverage now that it has FDA approval. (CNBC)

Quote: “There’s no question that the health statistics of rural America are worse than the health statistics of more urban America.”—Robert Harrington, a cardiologist and dean of Weill Cornell Medicine, on the lack of cardiologists in rural parts of the US (the Washington Post)

Read: Critics say that UnitedHealth has used questionable tactics and exploitation to achieve dominance in healthcare. (Stat)

CITE: https://www.r2library.com/Resource

Intel is slashing 15% of its staff as part of a $10 billion plan to reduce costs, the tech company announced in its second-quarter earnings Thursday.

CITE: https://tinyurl.com/2h47urt5

What’s up

What’s down

CITE: https://tinyurl.com/tj8smmes

Visualize: How private equity tangled banks in a web of debt, from the Financial Times.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

On the Financial Advice “Suitability” Standard

 It  Does Not Mean What You Think

By Rick Kahkler CFP® 

If you wanted hiking footwear, you probably would be surprised if a salesperson at an outdoors store suggested flip-flops. You would expect someone knowledgeable about hiking to recommend sturdy boots or shoes more suitable for your needs.

In the same way, if you consulted someone who sells financial products, you probably would expect them to recommend investments that are suitable for your needs. In fact, securities law provides a “suitability” standard for financial advisers who receive commissions for selling products like insurance, annuities, or non-public REITs.

Definition

Unfortunately, when it comes to investments, the word “suitability” does not mean what you probably think it means. It requires only that the adviser is honest with you and that you are legally able to evaluate and purchase the product. It does not require that the product be good for you to own in terms of being best for or even appropriate for your needs.

On the other hand, securities law requires advisers who charge fees for financial advice to be held to a “fiduciary” standard, which means they must be impartial, unbiased, and work as an advocate for clients.

http://www.HealthDictionarySeries.org

Assuming a financial representative is giving you “fiduciary” advice when in fact that person is only required to provide “suitable” advice could mean the difference between investment success or financial disaster. I mean for that to sound dire and alarming, because it is. I will even dare to say that understanding the difference between fiduciary and suitable advice is more important than the investment itself.

My alarmist opinion is supported by a recent article, “The Real Cost(s) of Suitability,” by financial editor Bob Veres. To find out whether consumers are actually harmed by relying on “suitable” advice, he gathered stories from over 100 subscribers to his Inside Information newsletter, most of whom are fiduciaries.

These examples are heartbreaking.

They include:

  • Financial advisers who sold high-premium, high-commission life insurance “investments” to customers who, in some cases, had to borrow from retirement accounts or take distributions to pay the premiums—as well as pay income taxes and penalties on the distributions.
  • Financial advisers who moved customers’ conservatively invested retirements funds into high-fee annuities, promising guarantees of no losses and returns of 5% that under scrutiny proved fictitious and will never be realized.
  • Financial advisers who made excessive numbers of trades, not to benefit customers but to generate transaction fees.
  • Financial advisers whose “suitable” recommendations, in too many cases, not only reduced clients’ investment returns, but actually drained clients’ portfolios and greatly damaged their ability to provide adequately for themselves in retirement.

Veres quoted Kathleen Campbell, of Campbell Financial Partners in Fort Myers, FL, as saying, “Suitable means plenty suitable for the broker and not so suitable for the client.” She called suitability “one of the biggest farces in the financial advisory world.”

I absolutely agree. It is essential to know whether a financial representative is held to a fiduciary or suitability standard.

Here’s how to tell the difference:

  • If you pay a fee for financial advice, with no sale or obligation to purchase a product, that’s a fiduciary adviser.
  • If there is no fee, you are dealing with a “suitability standard” broker, agent, or representative who has no legal requirement to give you unbiased advice.

Assessment

Understanding when you are getting impartial advice that’s in your best interests, and when you are getting conflicted and biased advice that is in the adviser’s best interest, is critical to your financial health.

Please, be wary of advisers whose recommendations emphasize “no fees.” Their “suitable” advice may leave you in a perilous situation—one much worse than wandering through the wilderness in flip-flops instead of hiking shoes. 

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Book Marcinko: https://medicalexecutivepost.com/dr-david-marcinkos-bookings/

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, IT, business and policy management ecosystem.

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

DAILY UPDATE: Rite Aid, Walgreens, CVS and Blood Drops as Technology Stock Rise

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

***

Five years after Theranos went dark, a couple of startups have managed to develop the futuristic tech, according to the Wall Street Journal.

  • Becton Dickinson developed a finger-prick device to collect drops of blood.
  • Babson Diagnostics made a machine that analyzes blood obtained through Becton’s device. It runs routine tests that you’d get at the doctor with one-tenth of the amount of blood that a traditional vein collection requires.

CITE: https://www.r2library.com/Resource

Here’s where the major benchmarks ended:

  • The S&P 500® (SPX) index climbed 85.86 points (1.6%) to 5,522.30; the Dow Jones Industrial Average® ($DJI) rose 99.46 points (0.2%) to 40,842.79; the NASDAQ Composite®($COMP) added 451.98 points (2.6%) to 17,599.40.
  • The 10-year Treasury note yield (TNX) dropped four basis points to just under 4.11%. 
  • The CBOE Volatility Index® (VIX) fell to 16.36.

What’s up

  • Starbucks rose 2.65% despite missing sales forecasts, with shareholders instead focusing on bullish business projections from management.
  • Boeing ascended 2.05% in a surprise turnaround after announcing subpar earnings. Investors are enthusiastic about the appointment of Robert Ortberg as the new CEO.
  • Match Group swiped right 13.21% after the company announced plans to reduce headcount in order to help offset lower subscriber numbers.
  • DuPont rallied 4.10% as the chemical company’s turnaround plans seem to be bearing fruit.
  • Arista Networks soared 11.32% thanks to high demand from AI users for the company’s data centers.
  • AutoNation revved 6.30% higher due to impressive growth in spite of a massive car dealership cyberattack earlier this year.

What’s down

CITE: https://tinyurl.com/2h47urt5

Rite Aid has been in Chapter 11 bankruptcy since October and has closed nearly 700 locations. CVS (CVS) and Walgreens (WBA) have managed to stay solvent, but both companies have been closing stores as well.

CITE: https://tinyurl.com/tj8smmes

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

IPO: Ackman Fund Postponed

By Staff Reporters

***

***

Bill Ackman’s fund postpones IPO

The billionaire hedge fund boss and frequent main character on X has delayed the stock market debut of the closed-end fund Pershing Square USA, which was scheduled for early next week, a notice on the New York Stock Exchange’s website said.

The decision to wait came days after Ackman said in a letter to investors that the firm was downsizing its expectations for the share sale from a target of about $25 billion (which would have made it the largest-ever IPO of its kind) to something between $2.5 billion and $4 billion.

Ackman has a similar fund already trading shares in Europe and has hinted he might take his larger firm, Pershing Square, public as soon as next year.

COMMENTS APPRECIATED

Thank You

***

***

PODCAST: About the Mathematical WOLFRAM ALPHA Computational Knowledge Engine

What it is – How it works

SMART CONTRACTS

[By Staff Reporters]

Wolfram Alpha is an online mathematical search engine launched in March 2009 and developed by Stephen Wolfram. It seeks to answer factual queries directly by computing the answer from structured data, rather than providing a list of web pages that might contain the answer.

In this way, WA differs from traditional semantic search engines, which index a large number of answers and then try to match the question to one. Wolfram Alpha has many parallels with Cyc, a project aimed since the 1980s at developing a common-sense inference engine. Wolfram Alpha is built on Wolfram’s earlier flagship product, Mathematica, which encompasses computer algebra, symbolic and numerical computation, visualization, and statistics capabilities.

With Mathematica running in the background, WA is suited to answer mathematical questions. The answer usually presents a human-readable solution.

Link: http://www.wolframalpha.com/

Technology

Wolfram Alpha is written in about 5 million lines of Mathematica (using webMathematica and gridMathematica) code and runs on 10,000 CPUs. As well as being a web site, Wolfram Alpha provides an API (for a fee) that delivers computational answers to other applications. One such application is the Bing search engine.

Capabilities

As an example, one can input the name of a website, and it will return relevant information about the site, including its location, site rank, number of visitors and more. The database currently includes hundreds of datasets, including current and historical weather, drug data, star charts, currency conversion, and many others. The datasets have been accumulated over approximately two years, and are expected to continue to grow. The range of questions that can be answered is also expected to grow with the expansion of the datasets.

Audio: http://www.wolframalpha.com/screencast/introducingwolframalpha.html

Utility and Usefulness

Wolfram Alpha is ideal for use by all readers and subscribers of the ME-P. It may be used by doctors, nurses, financial advisors and insurance agents, economists, mathematicians, editors, and publishers, teachers and students of all academic levels. The graphical nature of output is particularly helpful.

Assessment

Wolfram Alpha has received mixed reviews, to date. Advocates point to its potential, some even stating that how it determines output result is more important than current usefulness.

Note: Info courtesy wikipedia.org

PODCAST: https://www.bing.com/videos/search?q=stephen+wolfram&docid=608027542444182789&mid=7432EA16AEF1CDF4FCDD7432EA16AEF1CDF4FCDD&view=detail&FORM=VIRE

Conclusion

And so, your thoughts and comments on this ME-P are appreciated. Give Wolfram Alpha a click, listen to the audio-cast, and tell us what you think. Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:
HOSPITALS: http://www.crcpress.com/product/isbn/9781466558731
CLINICS: http://www.crcpress.com/product/isbn/9781439879900
BLOG: www.MedicalExecutivePost.com
FINANCE: Financial Planning for Physicians and Advisors
INSURANCE: Risk Management and Insurance Strategies for Physicians and Advisors

Product DetailsProduct DetailsProduct Details

Daniel Vande Lune MD on How HCQIA provided immunity is misused by hospitals for sham peer-review

Join Our Mailing List

Originally posted on Disrupted Physician

PUBLISHER’S NOTE: From time-to-time the ME-P might re-post an essay or opinion of vital interest to our readers and industrial ecosystem. This article is one of those times from an Award Winning Blogger and physician colleague from the Disrupted Physician. Feel free to visit his website directly and support his work as you deem fit.

https://www.gofundme.com/PHPReform

Langan MD

 The Ability for Hospitals to Hide behind the Immunity of HCQIA and the Abuse and Coercion by the PHP: my story and caveats.

I have been asked to write a guest blog and whole heartedly agreed. I am not afraid to tell my story ……

***

Guest Post: Dr. Daniel Vande Lune, MD discusses how HCQIA provided immunity is misused by hospitals for sham peer-review — Disrupted Physician

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

DAILY UPDATE: Healthcare Costs, Lobbyists and Private Equity as Technology Drowns

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

***

In the second quarter, 14 healthcare organizations spent more than a million dollars lobbying the federal government for healthcare policy change, led by the American Hospital Association and AARP.

CITE: https://www.r2library.com/Resource

Sen. Ed Markey (D-Massachusetts) and Rep. Pramila Jayapal (D-Washington) introduced strengthened legislation to rein in the actions of private equity firms that invest in healthcare facilities. The Health Over Wealth Act would require PE firms to put out reports on the facilities’ pay of executives, set up escrow accounts and receive a license from the Department of Health & Human Services prior to investing in healthcare facilities.

CITE: https://tinyurl.com/2h47urt5

The Federal Open Market Committee (FOMC) meeting ending tomorrow is widely expected to conclude with no interest rate move. Instead, it could serve as a platform to help prepare market participants for a possible cut at the September meeting.

Here’s where the major benchmarks ended:

  • The S&P 500® (SPX) index lost 27.1 points (–0.5%) to 5,436.44; the Dow Jones Industrial Average® ($DJI) climbed 203.4 points (0.5%) to 40,743.33; the NASDAQ Composite®($COMP) fell 222.78 points (–1.3%) to 17,147.42. 
  • The 10-year Treasury note yield (TNX) dropped about two basis points to 4.14%.
  • The CBOE Volatility Index® (VIX) jumped to 17.77, not far below last week’s highs.

What’s up

  • Paypal popped 8.59% after announcing impressive earnings and proving it’s got nothing to fear from Apple’s moves into the online payment world.
  • JetBlue Airways soared 12.31% thanks to a surprise profit last quarter rather than the loss analysts expected.
  • Affirm Holdings rose 2.31% due to an upgrade from “neutral” to “buy” from Bank of America analysts.
  • Tenable Holdings surged 9.30% after the cybersecurity company made it clear it’s willing to take acquisition offers.
  • F5 jumped 12.99% thanks to a beat-and-raise earnings report.

What’s down

CITE: https://tinyurl.com/tj8smmes

Visualize: A key measure of employer healthcare costs is poised for its biggest annual increase in more than a decade as more people use mental health care and get prescriptions for new, expensive drugs—yes, including Ozempic—according to a new PwC report.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

MICROSOFT DOWN: Online Outage Hit Again After Global IT Meltdown

BREAKING NEWS

Story by Andrew Griffin • 4h ago

By Staff Reporters

***

***

Microsoft’s online service have been hit by another outage, days after an IT meltdown that brought much of the world to a halt. The company said it was investigating reports of user problems accessing its services, with some reporting being unable to access email and other functions.

An alert on the technology giant’s service status website said it was looking into a “network infrastructure” issue that was impacting access to Microsoft services.

The incident comes less than two weeks after a major global IT outage knocked global infrastructure including transportation and healthcare services offline because of a flawed software update from cybersecurity firm CrowdStrike affected Microsoft devices.

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Bank Debt and Flat Stock Markets

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

***

CITE: https://www.r2library.com/Resource

Here’s where the major benchmarks ended:

  • The S&P 500® (SPX) index rose 4.44 points (0.1%) to 5,463.54; the Dow Jones Industrial Average® ($DJI) slipped 49.41 points (–0.1%) to 40,539.93; the NASDAQ Composite®($COMP) gained 12.32 points (0.1%) to close at 17,370.20. 
  • The 10-year Treasury note yield (TNX) fell roughly five basis points to just under 4.18%.
  • The CBOE Volatility Index® (VIX) finished nearly steady but still elevated at 16.59.

CITE: https://tinyurl.com/2h47urt5

What’s up

What’s down

  • Abbott Laboratories sank 0.45% after it was ordered to pay $495 million in damages for failing to warn of the risks to premature infants drinking its formula, a far higher number than analysts expected. Shares of its peer Reckitt Benckiser fell 8.65% in sympathy.
  • Arm Holdings slipped 5.07% after an HSBC analyst downgraded the company due to its sky-high valuation.
  • Heineken fell 8.18% thanks to slower beer sales in key markets, as well as the poor performance of its investment in Chinese brewer CR Beer.
  • Loews slid 1.47% due to an announcement that CEO James Tisch will step down after 25 years at the helm.
  • 3M dropped 1.56%, falling back to Earth after the stock enjoyed its best day of trading ever last Friday.

CITE: https://tinyurl.com/tj8smmes

Visualize: How private equity tangled banks in a web of debt, from the Financial Times.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

Three BOTS of Artificial Intelligence

A.I. and Computers

By Staff Reporters

***

***

***

***

  • Google revealed its answer to ChatGPT: an “experimental conversational AI service” called Bard that’s currently in testing mode.
  • Microsoft (which invested in ChatGPT) announced its own surprise event scheduled for later today in order to “share some progress on a few exciting projects.”
  • Chinese tech giant Baidu confirmed it’s on track to introduce its AI chatbot, known as “Ernie Bot” in English, in March.

***
COMMENTS APPRECIATED

Thank You

***

ORDER: https://www.amazon.com/Dictionary-Health-Information-Technology-Security/dp/0826149952/ref=sr_1_5?ie=UTF8&s=books&qid=1254413315&sr=1-5

***

LAUGH -or- CRY?

***

IAN BEAN MD

***

The “Magnificent 7” and the Dangers of Stock Market Hype

By Vitaliy Katsenelson CFA

***

***

The Magnificent 7 and the Dangers of Market Hype
You can also listen to a professional narration of this article on iTunes & online.
Despite the S&P 500 showing gains in the mid-teens, the average stock on the market is either up slightly or flat for the year. Most of the gains in the index came from the Magnificent 7 stocks, which constitute 35% of the index! The equal-weighted index, where the Magnicent 7 have only a 1.4% weight, is up only about 4% this year (as of this writing). 

The Magnificent 7 are starting to look like the Nifty Fifty stocks from the 1970s (Kodak, Polaroid, Avon, Xerox, and others) – stocks you “had to own” or you were left behind – until all your gains were taken away or you faced a decade or two of no returns. Forty years later, it’s easy to dismiss these companies as has-beens. They’ve all either gone bankrupt or become irrelevant.

But back then, they were the stars of corporate America, just like the Magnificent 7 are today.
As an investor, it’s crucial to know which games you play and which ones you don’t.

Let me explain: The Magnificent 7 and the Dangers of Market Hype

***

COMMENTS APPRECIATED

Thank You

***

***

DAILY UPDATE: Technology Stocks

MEDICAL EXECUTIVE-POST TODAY’S NEWSLETTER BRIEFING

***

Essays, Opinions and Curated News in Health Economics, Investing, Business, Management and Financial Planning for Physician Entrepreneurs and their Savvy Advisors and Consultants

Serving Almost One Million Doctors, Financial Advisors and Medical Management Consultants Daily

A Partner of the Institute of Medical Business Advisors , Inc.

http://www.MedicalBusinessAdvisors.com

SPONSORED BY: Marcinko & Associates, Inc.

***

http://www.MarcinkoAssociates.com

Daily Update Provided By Staff Reporters Since 2007.
How May We Serve You?
© Copyright Institute of Medical Business Advisors, Inc. All rights reserved. 2024

REFER A COLLEAGUE: MarcinkoAdvisors@msn.com

SPONSORSHIPS AVAILABLE: https://medicalexecutivepost.com/sponsors/

ADVERTISE ON THE ME-P: https://tinyurl.com/ytb5955z

Your Referral Count -0-

***

A magnificent earnings week is on tap: Four of the Magnificent Seven—Microsoft, Meta, Amazon, and Apple—will drop their reports throughout this week.

CITE: https://www.r2library.com/Resource

Technology stocks were down last week but investors are encouraged by signs that 2024’s rally—which had been underpinned by a handful of Big Tech companies—is spreading to a broader swath of the market. For instance, the industrial focused Dow Jones Industrial Average has gained for four straight weeks, and the small-cap Russell 3000 is now up 14% this year. All eyes will be on the upcoming Federal Reserve meeting and the busiest earnings week of the season.

CITE: https://tinyurl.com/2h47urt5

Donald Trump pledges to make the US “the crypto capital of the planet.” The former president pitched himself as the pro-crypto candidate in a keynote speech at the Bitcoin 2024 conference in Nashville. He told the audience that, if elected, he’d fire SEC Chair Gary Gensler (whom the crypto community accuses of waging a war on crypto) and install regulators friendly to digital tokens. He also said he’d create a strategic national crypto stockpile as part of a plan to make the US the “bitcoin superpower of the world.”

CITE: https://tinyurl.com/tj8smmes

Consider two numbers: $568.34 and $60.09. The first is Zoom’s highest closing stock price, from October 2020; the second is its stock price today. That’s an 89% decline, caused by more workers heading back into the office (even Zoom employees) and competition from rival products by Microsoft and Google.

Visualize: How private equity tangled banks in a web of debt, from the Financial Times.

COMMENTS APPRECIATED

PLEASE SUBSCRIBE: MarcinkoAdvisors@msn.com

Thank You

***

***

***

***

EDUCATIONAL TEXTBOOKS: https://tinyurl.com/4zdxuuwf

***

SURVEY: Primary Care Doctors Deliver Most Medical Care

***

By MCOL

***

***

25% of Primary Care Doctors Delivered 86% of Medical Care

 •  25% of primary care doctors delivered 86% of medical care.
 •  25% of specialists on average provided 75% of medical care.
 •  16.3% of physicians listed in Medicaid managed care plan provider network directors in a year qualified as ghost physicians (seeing zero Medicaid beneficiaries over the course of the year in an outpatient setting).
 •  The share of ghost physicians ranged from 13.4% to 24.9% across states.

Source: Health Affairs via Fierce Healthcare, May 5, 2022

***

COMMENTS APPRECIATED

Thank You

***

***

***

PODCAST: Scaling Primary Care

By Eric Bricker MD

***

***

COMMENTS APPRECIATED

Thank You

***

***

SCOTUS: Rejects Chevron Deference [Healthcare Industry Implications]

By Health Capital Consultants, LLC

***

***

On June 28, 2024, the U.S. Supreme Court issued a seismic decision explicitly overruling the Chevron doctrine,” which will limit the ability of federal agencies to rely on their own interpretation of the laws they administer.

Under the Chevron doctrine, more commonly referred to as Chevron deference, courts were mandated to uphold a federal agency’s interpretation of a statute as long as it was reasonable.

This Health Capital Topics article discusses the Chevron doctrine, the Supreme Court’s decision, and the impact of this ruling on the healthcare industry. (Read more…)

COMMENTS APPRECIATED

Thank You

***

***