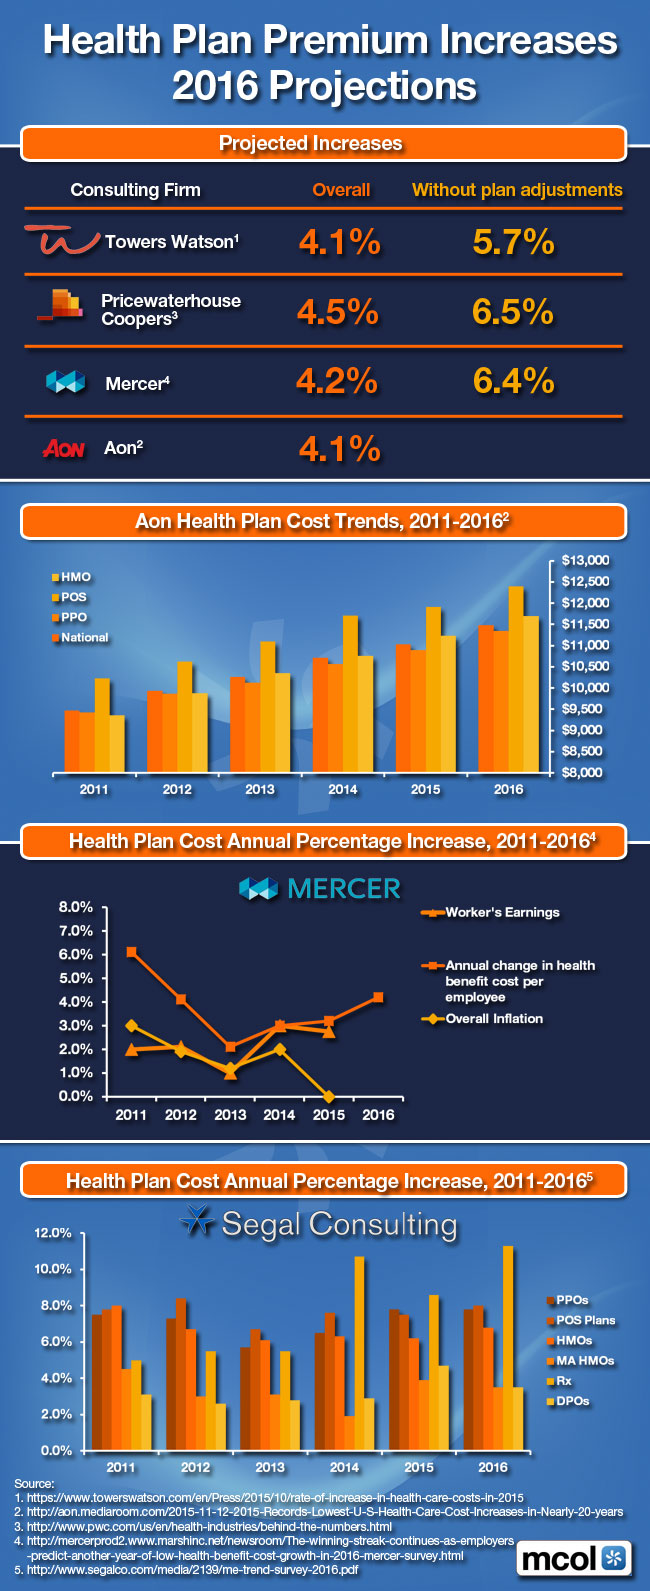
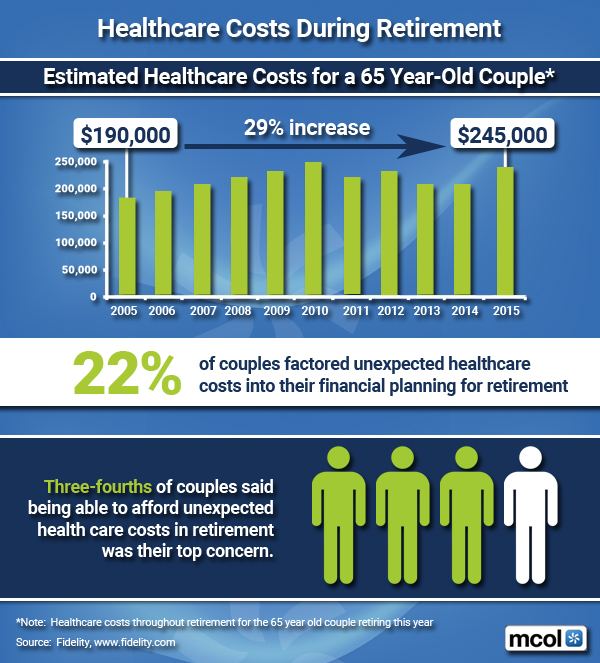
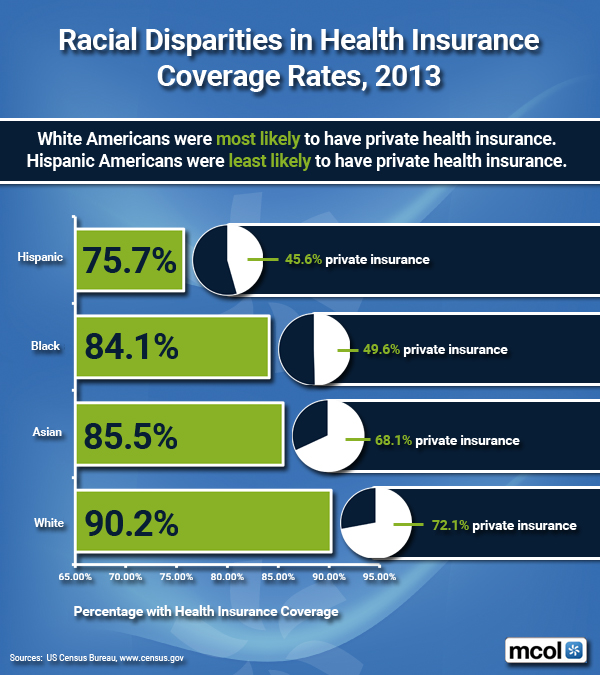
Health Plan Premium Increases for 2016

Join Our Mailing List

Projections for 2016

By http://www.MCOL.com

***

ImageProxy

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

***

dollar-1029742_640

***

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

 ***

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™   Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***


ALL ABOUT HEALTH TURNUP

Join Our Mailing List

[By Staff Reporters]

http://www.MCOL.com

ABOUT HEALTH TURNUP

[Healthcare news that’s not quite right]

***
Health Turnup is published monthly via email. Subscriptions are free. Subscribers also receive weekly e-Bulletins and announcements. Detailed information is available at www.HealthTurnup.com, including the subscriber privacy policy, advertising information and disclaimers that all articles contained in this newsletter are fictitious in nature, and are provided for satirical purposes.

Inquiries can directed to info@healthturnup.com or 209.577.4888.

HealthTurnup is a service of MCOL. Copyright 2015, MCOL, Inc.

All Rights Reserved.    

***

ImageProxy***

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

Housing Wealth Continues to Rise

Join Our Mailing List

Back to pre-financial-crisis levels?

josh

[By Josh Velazquez CMPS]

jvelazquez@bankingunusual.com

The amount of equity that Americans have in their homes has risen back up to pre-financial-crisis levels.

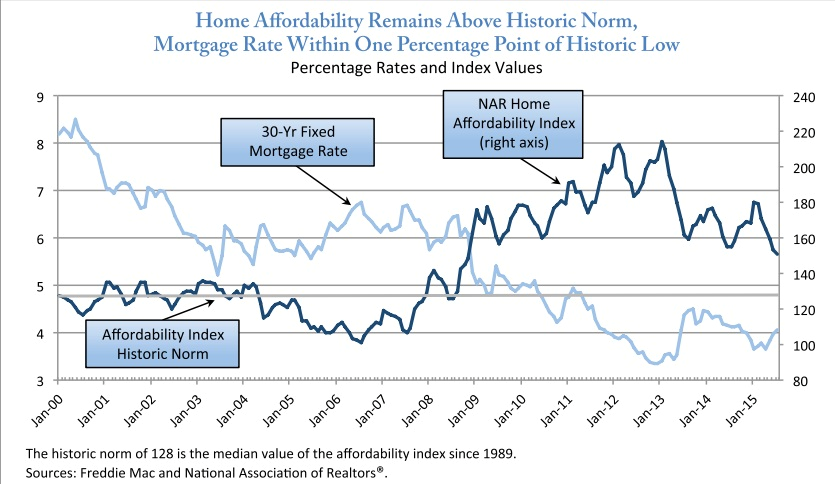
The interesting thing is that it still seems like there is room to grow because housing affordability is still very comfortably above its historical average (see chart below).

This is partly due to the fact that mortgage rates remain low and home ownership is still very affordable relative to renting a house.

***

untitled-1

***

Bottom line: if you or someone you know missed the opportunity to purchase a home a few years ago, it may not be too late to ride this wave higher!

 *** untitled-2

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

***

Drs. Home

***

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™ Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

14 Smart Things to Consider for Your 2015 Year-End Financial Checklist

Join Our Mailing List

Be Ready for a Great 2016!

pat

[By Patrick Bourbon CFA]

1. IRA – 401(k) / 403(b) retirement accounts – Are you on track for a comfortable retirement?   You could increase the funding of your IRA and company retirement plan like a 401(k) or 403(b) accounts.   401(k) and 403(b) accounts allow individuals younger than 50 to contribute $18,000 each year, and individuals 50 and older to contribute $24,000. Some plans allow workers to make additional contributions of after-tax money.

For those under 50, the maximum is $53,000 for 2015. Doing so does not reduce your taxable income, but taxes are deferred on any earnings that the after-tax money makes. Later, some people roll these contributions into a Roth IRA, tax-free so the money would then grow tax-free.   Traditional and Roth IRAs allow individuals younger than 50 to contribute $5,500 each year and individuals 50 and older to contribute $6,500. Even if you earn too much to contribute to a Roth IRA directly, you can open a traditional nondeductible IRA and convert it to a Roth; there is no income limit on traditional nondeductible IRAs or conversions.    Returns generated in IRA and 401(k) / 403(b) accounts compound tax-free over their entire life.

2. Start tax planning! It’s not too early to think about taxes. Asset location & Tax efficiency   Review your taxable and non-taxable accounts to ensure they are optimized for tax efficiency. If you have foreign bank accounts, make sure you comply with FATCA and FBAR (forms FinCEN 114, 8938, 8621…). If you have forgotten, you may look into the Offshore Voluntary Disclosure Program (OVDP) or Streamlined procedures.

3. Portfolio rebalancing   Make sure you have rebalanced your portfolios to keep them in line with your goals, time horizon and risk tolerance. The market movements this summer may have thrown off your portfolio balance between stocks and bonds.   David Swensen, the Chief Investment Officer at the Yale Endowment, performed an analysis that showed optimal rebalancing could add 0.4% to your annual return.

4. Harvest your capital losses   Maybe it is time to sell some funds, ETF, stocks to generate some capital losses?   Tax-loss harvesting is a method of reducing your taxes by selling an investment that is trading at a significant loss.  Find out if you have any loss carryovers from prior years to be applied against capital gains (from sale of funds, ETF, stocks… in your taxable/brokerage accounts). If your current year’s capital losses exceed your capital gains, you have a net capital loss. You can use up to $3,000 of that loss ($1,500 if you are married filing separately) to offset other taxable income such as your salaries, wages, interest and dividends. If the capital loss is more than $3,000, you can carry over the excess and apply it against capital gains next year.

5. Emergency fund   Don’t forget to establish or tune up your emergency fund. This is a good time to set aside money for next year’s cash needs. It is an account that is used to set aside funds to be used in an emergency, such as the loss of a job, an illness or a major expense.

6. Review your insurance policies   Do you have a life, disability and long term care insurance? Make sure you and your loved ones are well protected if something happens to you. Your life may have changed (birth, marriage …). If you do have enough coverage it is also a good time simply to review the different types of coverage you have. Whole life or Variable Universal Life may help you reduce your taxes.

7. Health Spending Account   Did you maximize your contribution to your healthcare HSA? The interest and earnings in this account are tax free! The maximum contribution for 2015 is $3,350 for an individual and $6,650 for a family ($1,000 catch-up over 55). The contributions are tax deductible and withdraws are non-taxable if they are used for medical expenses. Over the age of 65 you can withdraw funds at your ordinary tax rate (if the distribution is not used for unreimbursed medical expenses). Fidelity estimates that a 65-year-old couple retiring in 2014 will need $220,000 for health care costs in retirement, in addition to expenses covered by Medicare. The HSA can be a great source of tax-free money to pay those bills.

8. Required Minimum Distribution   If you are age 70.5 or older, remember to take your required minimum distribution to avoid a potential 50% penalty.

9. 529 Plan   Did you contribute to your 529 educational plan for your child/children?   You can contribute $14,000 per year (annual limit) for each parent or you can pre-fund in a single instance up to five years’ worth of contributions, up to $70,000 (5 x $14,000). Together, that means a married couple can open a 529 plan with $140,000.   Money saved in a 529 plan grows tax-free when used for eligible educational expenses, and some states have additional tax benefits for residents who contribute to a plan in that state.

10. Determine your net worth   Add up what you own (home, car, savings, investments…) and subtract what you owe (mortgage, loans, credit cards, …).   This will allow you to track your progress year to year. It may also give you some incentive to save more and create a better budget for next year.

11. Check your credit score Go to annualcreditreport.com and request a free credit report from each of the three nationwide credit reporting agencies. You’re entitled to one free report from each agency every 12 months.

12. Check your beneficiaries   You can check the beneficiaries on your retirement accounts or insurance policies at any time, but it’s a good idea to do this at least annually.

13. Update your estate plan   New baby? Newly married or divorced? Make sure your beneficiary designations reflect any changes. Don’t yet have an estate plan? Make that a new year’s resolution!  Estate planning may include updating or establishing a “will” or trust that can help avoid public disclosure of assets in probate.

14. Spending and automated savings – You want to look ahead   Did you review your budget and set up automated savings?   You may have started the year with a clear budget, but did you to stick to it?    Fall can be a good time of the year for your financial checkup and to reflect on your spending and develop a budget for next year.  It is also a very good time to put whatever you can on automatic. Bills, recurring payments, even savings—the more you can put on auto pay now, the easier your financial life will be next year.   With this year’s facts and figures in front of you, it will be easier to plan and prioritize your expenditures for next year.

Assessment

198174

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

 ***

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

Front Matter with Foreword by Jason Dyken MD MBA

logos

“BY DOCTORS – FOR DOCTORS – PEER REVIEWED – FIDUCIARY FOCUSED

***

Are Interest Rates expected to increase in December?

Join Our Mailing List

And, the Bureau of Labor Statistics (BLS) said …

Art

By Arthur Chalekian GEPC
[Financial Consultant]

U.S. job growth surpassed expectations in October. About 271,000 jobs were created across diverse industries: professional and business services, health care, retail, construction, and others. That was a significantly higher number than predicted by economists who participated in a survey conducted by The Wall Street Journal. They expected to see 183,000 new jobs for October.

BLS revised

The BLS revised August and September jobs numbers higher overall and reported improvement on the wage front, too. Average hourly earnings increased by nine cents during October. For the year, hourly earnings are up 2.5 percent. Rising wages and a 5 percent unemployment rate “appear to indicate the labor market has reached full employment,” reported Barron’s.

Strong employment data supports the idea the Fed will begin to lift the Fed funds rate this year. On Friday, former Chairman of the Federal Reserve Ben Bernanke wrote in his blog:

“Wednesday was something of a trifecta for Fed watchers: Chair Yellen, Board Vice-Chair Stanley Fischer, and Federal Reserve Bank of New York president Bill Dudley (who is also the vice chair of the Federal Open Market Committee) all made public appearances. Moreover, the comments by all three members of the Fed’s leadership explicitly or implicitly supported the idea that a December rate increase by the FOMC is a distinct possibility. (The possibility of a rate increase is even more distinct with this morning’s strong job market report.)”

Markets responded swiftly, according to The Wall Street Journal, as investors repositioned their portfolios in anticipation of a rate hike. While stock market indices remained relatively steady, there was considerable volatility within certain sectors. An expert cited by the publication commented:

“…one of the big rotation trades on Friday was investors taking money out of companies such as utilities and real-estate-investment trusts, and putting it into those that are expected to benefit from higher rates, such as financial companies.”

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

***

On the lack of encryption of ePHI in transmission and at rest

Join Our Mailing List 

Shahid N. Shah MS[By Shahid N. Shah MS]

ePHI is vulnerable to be compromised in all the states it is in. Whether it is at rest (in databases and files), or in motion (being transmitted through networks), or in use (being updated, or read), or is disposed (discarded paper files or electronic storage media).

Using encryption puts an extra layer of security to ePHI because even if someone gains access or reads ePHI, if it is encrypted then the chances of ePHI getting compromised diminishes. It makes the data unreadable and unusable by unauthorized persons. When ePHI is transmitted through networks, it is possible that it will be accessed by unauthorized persons, thus compromising ePHI. These type of unauthorized access hacking may not be immediately known, but can cause many damages.

Major Mitigation

ePHI should be encrypted and there must also be reasonable and appropriate mechanisms in place to prevent access to ePHI so that it is not accessed by persons or software programs that have not been granted access rights.

There are many different encryption methods and technologies to encrypt data in motion (SSL, VPN) or at rest. Choose the methods and technologies that best meet the physician’s office requirements.

Success criteria

The risk analysis/assessment reports will provide a clear indication of whether these type of risks exists or has been mitigated with appropriate controls.

***

secret

***

Assessment

Auditing logs that track access to ePHI can be verified periodically to check if there has been unauthorized access by persons or software programs that have not been granted access rights.

More

ABOUT 

Mr. Shahid N. Shah is an internationally recognized healthcare thought-leader across the Internet. He is a consultant to various federal agencies on technology matters and winner of Federal Computer Week’s coveted “Fed 100″ Award, in 2009. Over a twenty year career, he built multiple clinical solutions and helped design-deploy an electronic health record solution for the American Red Cross and two web-based eMRs used by hundreds of physicians with many large groupware and collaboration sites. As ex-CTO for a billion dollar division of CardinalHealth, he helped design advanced clinical interfaces for medical devices and hospitals. Mr. Shah is senior technology strategy advisor to NIH’s SBIR/STTR program helping small businesses commercialize healthcare applications. He runs four successful blogs: At http://shahid.shah.org he writes about architecture issues; at http://www.healthcareguy.com he provides valuable insights on applying technology in health care; at http://www.federalarchitect.com he advises senior federal technologists; and at http://www.hitsphere.com he gives a glimpse of HIT as an aggregator. Mr. Shah is a Microsoft MVP (Solutions Architect) Award Winner for 2007, and a Microsoft MVP (Solutions Architect) Award Winner for 2006. He also served as a HIMSS Enterprise IT Committee Member. Mr. Shah received a BS in computer science from the Pennsylvania State University and MS in Technology Management from the University of Maryland. 

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

Congrats to Dr. Angus Stewart Deaton

Join Our Mailing List

[Staff reporters]

Angus Deaton – Princeton University

The Princeton University economist Angus Deaton won this year’s Nobel Prize in economic sciences.

https://en.wikipedia.org/wiki/Angus_Deaton

Nobel Prize Medal

***

ME-P Health Economics, Financial Planning & Investing, Medical Practice, Risk Management and Insurance Textbooksfor Doctors and Advisors

ME-P At Your Service!

***

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

[HOSPITAL OPERATIONS, ORGANIZATIONAL BEHAVIOR AND FINANCIAL MANAGEMENT COMPANION TEXTBOOK SET]

Product DetailsProduct Details

[Foreword Dr. Phillips MD JD MBA LLM] *** [Foreword Dr. Nash MD MBA FACP]

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

Product Details

http://www.BusinessofMedicalPractice.com

***

Dr. David Edward Marcinko, editor-in-chief, is a next-generation apostle of Nobel Laureate Kenneth Joseph Arrow, PhD, as a health-care economist, insurance advisor, financial advisor, risk manager, and board-certified surgeon from Temple University in Philadelphia. In the past, he edited eight practice-management books, three medical textbooks and manuals in four languages, five financial planning yearbooks, dozens of interactive CD-ROMs, and three comprehensive health-care administration dictionaries. Internationally recognized for his clinical work, he is a distinguished visiting professor of surgery and a recipient of an honorary Bachelor of Medicine–Bachelor of Surgery (MBBS) degree from Marien Hospital in Aachen, Germany. He provides litigation support and expert witness testimony in state and federal court, with medical publications archived in the Library of Congress and the Library of Medicine at the National Institutes of Health.

***

Why we build [business and/or valuation] investment models?

Join Our Mailing List 

Qualitatively and quantitatively intensive!

By Vitaliy N. Katsenelson CFA 

vitalyOur investment process at IMA is both qualitatively and quantitatively intensive. Throughout the course of a year we look at hundreds of companies. Most of them receive only a cursory look – we don’t like the business, the valuation is too stretched, or we simply have no insight into the business. We usually glance at them and move on.

But, if we really like the business and/or its valuation, we build a model. Often, just from a cursory look we know that the stock is not cheap enough, but if we really (really!) like the business we’ll invest the time to model it so we can understand it better and set a price at which we want to buy it (and then wait).

***

We build models

***

We build a lot of models. We built over a hundred models last year (we bought only a handful of stocks). Building models is important for us. Models help us to understand businesses better. They provide insights as to which metrics matter and which don’t. They allow us stress test the business: we don’t just look at the upside but spend a lot of times looking at the downside – we try to “kill” the business. We usually try to drill down to essential operating metrics. If it is a convenience store retailer, we’ll look into gallons of gas sold and profit per gallon. If it is a driller (see our Helmerich & Payne analysis), we look at utilization rates, rigs in service, average revenue per rig per day, etc.

***

In the past, when we owned Joseph A. Banks, a model helped us understand the impact maturation of its new stores had on same-store sales (PDF, see slide 49). Half of Joseph A. Banks stores were less than five years old, and their maturation drove significant same-store sales increase for years.

***

We looked at American Express before the crisis, which gave us insight into inflated profit margins of the financial sector, and thus we avoided for the most part the carnage in the financials. We thought American Express stock was not cheap enough at the time, but we learned that Amex’s high swipe-fee revenue provided an important buffer to help the company absorb significant loan losses. Amex could have withstood over 10% loan losses on its credit card portfolio and still have remained profitable. This insight gave us the confidence to buy Amex during the crisis.

***

value

***

Models are important because they help us remain rational. It is only the matter of time before a stock we own will “blow up” (or, in layman’s terms, decline). We can go back to our model and assess whether the decline is warranted. The model then gives us the confidence to make a rational (very key word) decision: buy more, do nothing, or sell.

***

Assessment

***

Models are frameworks that help us think about the businesses we analyze. We are always aware of John Maynard Keynes’ expression, “I’d rather be vaguely right than precisely wrong.” Models are not a panacea, but they are an important and often invaluable tool. However, models are only as good as their builders and the inputs to them.

***

ABOUT

Vitaliy N. Katsenelson, CFA, is Chief Investment Officer at Investment Management Associates in Denver, Colo. He is the author of Active Value Investing (Wiley 2007) and The Little Book of Sideways Markets (Wiley, 2010).  His books have been translated into eight languages.  Forbes called him – the new Benjamin Graham.

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

Front Matter with Foreword by Jason Dyken MD MBA

logos

“BY DOCTORS – FOR DOCTORS – PEER REVIEWED – FIDUCIARY FOCUSED”

***

About the “Surface Transportation and Veterans Health Care Choice Improvement Act of 2015”

Join Our Mailing List

Changes and Updates in Tax Return Due Dates

By Bobby Whirley CPA, Alpharetta, GA

[Whirley & Associates, LLC + Proactive Advisory]

On July 31st, 2015, President Obama signed into law P.L. 114-41, the “Surface Transportation and Veterans Health Care Choice Improvement Act of 2015.”

Although this new law was primarily designed as a 3-month stopgap extension of the Highway Trust Fund and related measures, it includes a number of important tax provisions, including revised due dates for partnership and C corporation returns and revised extended due dates for some returns. This letter provides an overview of these provisions, which may have an impact on you, your family, or your business.

Revised Due Dates for Partnership and C Corporation Returns

Domestic corporations (including S corporations) currently must file their returns by the 15th day of the third month after the end of their tax year. Thus, corporations using the calendar year must file their returns by March 15 of the following year. The partnership return is due on the 15th day of the fourth month after the end of the partnership’s tax year. And, partnerships using a calendar year must file their returns by April 15th of the following year. Since the due date of the partnership return is the same date as the due date for an individual tax return, individuals holding partnership interests often must file for an extension to file their returns because their Schedule K-1s may not arrive until the last minute.

***

ImageProxy

***

Under the new law, in a major restructuring of entity return due dates, effective generally for returns for tax years beginning after December 31st, 2015:

  • Partnerships and S corporations will have to file their returns by the 15th day of the third month after the end of the tax year. Thus, entities using a calendar year will have to file by March 15th of the following year. In other words, the filing deadline for partnerships will be accelerated by one month; the filing deadline for S corporations stays the same. By having most partnership returns due one month before individual returns are due, taxpayers and practitioners will generally not have to extend, or scurry around at the last minute to file, the returns of individuals who are partners in partnerships.
  • C corporations will have to file by the 15th day of the fourth month after the end of the tax year. Thus, C corporations using a calendar year will have to file by April 15th of the following year. In other words, the filing deadline for C corporations will be deferred for one month.
  • Keep in mind that these important changes to the filing deadlines generally won’t go into effect until the 2016 returns have to be filed. Under a special rule for C corporations with fiscal years ending on June 30th, the change is deferred for ten years — it won’t apply until tax years beginning after December 31st, 2025.

***

Veterans Day 2015

***

Revised Extended Due Dates for Various Returns

  • Taxpayers who can’t file a tax form on time can ask the IRS for an extension to file the form. Effective for tax returns for tax years beginning after December 31st, 2015, the new law directs the IRS to modify its regulations to provide for a longer extension to file a number of forms, including the following:
  • Form 1065 (U.S. Return of Partnership Income) will have a maximum extension of six-months (currently, a 5-month extension applies). The extension will end on September 15th for calendar year taxpayers.
  • Form 1041 (U.S. Income Tax Return for Estates and Trusts) will have a maximum extension of five and a half months (currently, a 5-month extension applies). The extension will end on Sept. 30th for calendar year taxpayers.
  • The Form 5500 series (Annual Return/Report of Employee Benefit Plan) will have a maximum automatic extension of three and a half months (under currently law, a 2½ month period applies). The extension will end on November 15 for calendar year filers.

FinCEN Report Due Date Revised

  • Taxpayers with a financial interest in or signature authority over certain foreign financial accounts must file FinCEN Form 114, Report of Foreign Bank and Financial Accounts (FBAR). Currently, this form must be filed by June 30 of the year immediately following the calendar year being reported, and no extensions are allowed.

***

rote

***

Assessment

Under the new law, for returns for tax years beginning after December 31, 2015, the due date of FinCEN Report 114 will be April 15 with a maximum extension for a 6-month period ending on October 15th. The IRS may also waive the penalty for failure to timely request an extension for filing the Report, for any taxpayer required to file FinCEN Form 114 for the first time.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

 Front Matter with Foreword by Jason Dyken MD MBA

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

logos

“BY DOCTORS – FOR DOCTORS – PEER REVIEWED – FIDUCIARY FOCUSED”

***

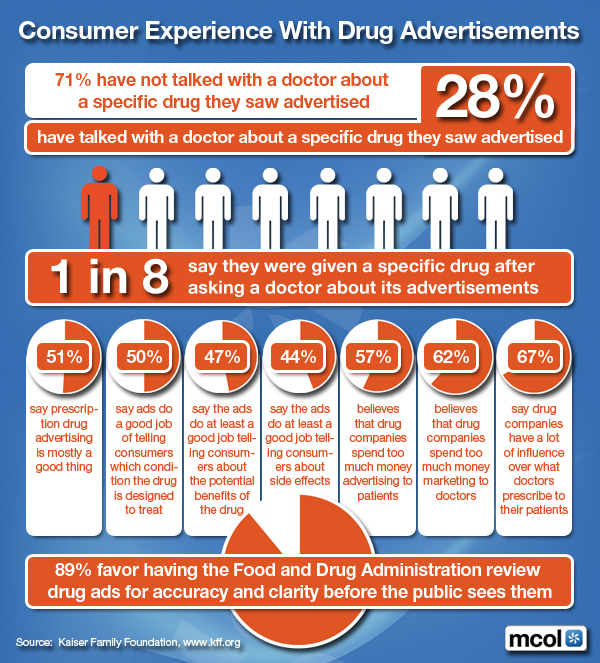
Consumer Experience with Drug Advertisements

Join Our Mailing List

On D-2-C Ads?

By http://www.MCOL.com

***

ImageProxy

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[PRIVATE MEDICAL PRACTICE BUSINESS MANAGEMENT TEXTBOOK – 3rd.  Edition]

Product Details

  [Foreword Dr. Hashem MD PhD] *** [Foreword Dr. Silva MD MBA]

***

Year End Tax Planning for Physicians

Join Our Mailing List

And … Business Owners

By Robert Whirley CPA

[Alpharetta, GA 30009]

As the end of the year approaches, it is a good time to think of planning moves that will help lower your tax bill for this year and possibly the next. Factors that compound the challenge include turbulence in the stock market, overall economic uncertainty, and Congress’s failure to act on a number of important tax breaks that expired at the end of 2014. Some of these tax breaks ultimately may be retroactively reinstated and extended, as they were last year, but Congress may not decide the fate of these tax breaks until the very end of 2015 (or later). These breaks include, for individuals: the option to deduct state and local sales and use taxes instead of state and local income taxes; the above-the-line-deduction for qualified higher education expenses; tax-free IRA distributions for charitable purposes by those age 70- 1/2 or older; and the exclusion for up-to-$2 million of mortgage debt forgiveness on a principal residence. For businesses, tax breaks that expired at the end of last year and may be retroactively reinstated and extended include: 50% bonus first-year depreciation for most new machinery, equipment and software; the $500,000 annual expensing limitation; the research tax credit; and the 15-year writeoff for qualified leasehold improvements, qualified restaurant buildings and improvements, and qualified retail improvements.

Higher-income earners have unique concerns to address when mapping out year-end plans. They must be wary of the 3.8% surtax on certain unearned income and the additional 0.9% Medicare (hospital insurance, or HI) tax. The latter tax applies to individuals for whom the sum of their wages received with respect to employment and their self-employment income is in excess of an unindexed threshold amount ($250,000 for joint filers, $125,000 for married couples filing separately, and $200,000 in any other case).

The surtax is 3.8% of the lesser of: (1) net investment income (NII), or (2) the excess of modified adjusted gross income (MAGI) over an unindexed threshold amount ($250,000 for joint filers or surviving spouses, $125,000 for a married individual filing a separate return, and $200,000 in any other case). As year-end nears, a taxpayer’s approach to minimizing or eliminating the 3.8% surtax will depend on his estimated MAGI and NII for the year. Some taxpayers should consider ways to minimize (e.g., through deferral) additional NII for the balance of the year, others should try to see if they can reduce MAGI other than NII, and other individuals will need to consider ways to minimize both NII and other types of MAGI.

The 0.9% additional Medicare tax also may require year-end actions. Employers must withhold the additional Medicare tax from wages in excess of $200,000 regardless of filing status or other income. Self-employed persons must take it into account in figuring estimated tax. There could be situations where an employee may need to have more withheld toward the end of the year to cover the tax. For example, if an individual earns $200,000 from one employer during the first half of the year and a like amount from another employer during the balance of the year, he would owe the additional Medicare tax, but there would be no withholding by either employer for the additional Medicare tax since wages from each employer don’t exceed $200,000. Also, in determining whether they may need to make adjustments to avoid a penalty for underpayment of estimated tax, individuals also should be mindful that the additional Medicare tax may be overwithheld. This could occur, for example, where only one of two married spouses works and reaches the threshold for the employer to withhold, but the couple’s combined income won’t be high enough to actually cause the tax to be owed.

We have compiled a checklist of additional actions based on current tax rules that may help you save tax dollars if you act before year-end. Not all actions will apply in your particular situation, but you (or a family member) will likely benefit from many of them. We can narrow down the specific actions that you can take once we meet with you to tailor a particular plan. In the meantime, please review the following list and contact us at your earliest convenience so that we can advise you on which tax-saving moves to make. 

***

IRS

***

Year-End Tax Planning Moves for Individuals

  • Realize losses on stock while substantially preserving your investment position. There are several ways this can be done. For example, you can sell the original holding, then buy back the same securities at least 31 days later. It may be advisable for us to meet to discuss year-end trades you should consider making.
  • Postpone income until 2016 and accelerate deductions into 2015 to lower your 2015 tax bill. This strategy may enable you to claim larger deductions, credits, and other tax breaks for 2015 that are phased out over varying levels of adjusted gross income (AGI). These include child tax credits, higher education tax credits, and deductions for student loan interest. Postponing income also is desirable for those taxpayers who anticipate being in a lower tax bracket next year due to changed financial circumstances. Note, however, that in some cases, it may pay to actually accelerate income into 2015. For example, this may be the case where a person’s marginal tax rate is much lower this year than it will be next year or where lower income in 2016 will result in a higher tax credit for an individual who plans to purchase health insurance on a health exchange and is eligible for a premium assistance credit.
  • If you believe a Roth IRA is better than a traditional IRA, consider converting traditional-IRA money invested in beaten-down stocks (or mutual funds) into a Roth IRA if eligible to do so. Keep in mind, however, that such a conversion will increase your AGI for 2015.
  • If you converted assets in a traditional IRA to a Roth IRA earlier in the year and the assets in the Roth IRA account declined in value, you could wind up paying a higher tax than is necessary if you leave things as is. You can back out of the transaction by recharacterizing the conversion—that is, by transferring the converted amount (plus earnings, or minus losses) from the Roth IRA back to a traditional IRA via a trustee-to-trustee transfer. You can later reconvert to a Roth IRA.
  • It may be advantageous to try to arrange with your employer to defer, until 2016, a bonus that may be coming your way.
  • Consider using a credit card to pay deductible expenses before the end of the year. Doing so will increase your 2015 deductions even if you don’t pay your credit card bill until after the end of the year.
  • If you expect to owe state and local income taxes when you file your return next year, consider asking your employer to increase withholding of state and local taxes (or pay estimated tax payments of state and local taxes) before year-end to pull the deduction of those taxes into 2015 if you won’t be subject to the alternative minimum tax (AMT) in 2015.
  • Take an eligible rollover distribution from a qualified retirement plan before the end of 2015 if you are facing a penalty for underpayment of estimated tax and having your employer increase your withholding is unavailable or won’t sufficiently address the problem. Income tax will be withheld from the distribution and will be applied toward the taxes owed for 2015. You can then timely roll over the gross amount of the distribution, i.e., the net amount you received plus the amount of withheld tax, to a traditional IRA. No part of the distribution will be includible in income for 2015, but the withheld tax will be applied pro rata over the full 2015 tax year to reduce previous underpayments of estimated tax.
  • Estimate the effect of any year-end planning moves on the AMT for 2015, keeping in mind that many tax breaks allowed for purposes of calculating regular taxes are disallowed for AMT purposes. These include the deduction for state property taxes on your residence, state income taxes, miscellaneous itemized deductions, and personal exemption deductions. Other deductions, such as for medical expenses of a taxpayer who is at least age 65 or whose spouse is at least 65 as of the close of the tax year, are calculated in a more restrictive way for AMT purposes than for regular tax purposes. If you are subject to the AMT for 2015, or suspect you might be, these types of deductions should not be accelerated.
  • You may be able to save taxes this year and next by applying a bunching strategy to “miscellaneous” itemized deductions, medical expenses and other itemized deductions.
  • You may want to pay contested taxes to be able to deduct them this year while continuing to contest them next year.
  • You may want to settle an insurance or damage claim in order to maximize your casualty loss deduction this year.
  • Take required minimum distributions (RMDs) from your IRA or 401(k) plan (or other employer-sponsored retirement plan). RMDs from IRAs must begin by April 1 of the year following the year you reach age 70- 1/2. That start date also applies to company plans, but non-5% company owners who continue working may defer RMDs until April 1 following the year they retire. Failure to take a required withdrawal can result in a penalty of 50% of the amount of the RMD not withdrawn. If you turned age 70- 1/2 in 2015, you can delay the first required distribution to 2016, but if you do, you will have to take a double distribution in 2016—the amount required for 2015 plus the amount required for 2016. Think twice before delaying 2015 distributions to 2016, as bunching income into 2016 might push you into a higher tax bracket or have a detrimental impact on various income tax deductions that are reduced at higher income levels. However, it could be beneficial to take both distributions in 2016 if you will be in a substantially lower bracket that year.
  • Increase the amount you set aside for next year in your employer’s health flexible spending account (FSA) if you set aside too little for this year.
  • If you can make yourself eligible to make health savings account (HSA) contributions by Dec. 1, 2015, you can make a full year’s worth of deductible HSA contributions for 2015.
  • Make gifts sheltered by the annual gift tax exclusion before the end of the year and thereby save gift and estate taxes. The exclusion applies to gifts of up to $14,000 made in 2015 to each of an unlimited number of individuals. You can’t carry over unused exclusions from one year to the next. The transfers also may save family income taxes where income-earning property is given to family members in lower income tax brackets who are not subject to the kiddie tax.

***

Tax


***

Year-End Tax-Planning Moves for Medical Practices, & Business Owners 

  • Businesses should buy machinery and equipment before year end and, under the generally applicable “half-year convention,” thereby secure a half-year’s worth of depreciation deductions in 2015.
  • Although the business property expensing option is greatly reduced in 2015 (unless retroactively changed by legislation), making expenditures that qualify for this option can still get you thousands of dollars of current deductions that you wouldn’t otherwise get. For tax years beginning in 2015, the expensing limit is $25,000, and the investment-based reduction in the dollar limitation starts to take effect when property placed in service in the tax year exceeds $200,000.
  • Businesses may be able to take advantage of the “de minimis safe harbor election” (also known as the book-tax conformity election) to expense the costs of inexpensive assets and materials and supplies, assuming the costs don’t have to be capitalized under the Code Sec. 263A uniform capitalization (UNICAP) rules. To qualify for the election, the cost of a unit of property can’t exceed $5,000 if the taxpayer has an applicable financial statement (AFS; e.g., a certified audited financial statement along with an independent CPA’s report). If there’s no AFS, the cost of a unit of property can’t exceed $500. Where the UNICAP rules aren’t an issue, purchase such qualifying items before the end of 2015.
  • A corporation should consider accelerating income from 2016 to 2015 if it will be in a higher bracket next year. Conversely, it should consider deferring income until 2016 if it will be in a higher bracket this year.
  • A corporation should consider deferring income until next year if doing so will preserve the corporation’s qualification for the small corporation AMT exemption for 2015. Note that there is never a reason to accelerate income for purposes of the small corporation AMT exemption because if a corporation doesn’t qualify for the exemption for any given tax year, it will not qualify for the exemption for any later tax year.
  • A corporation (other than a “large” corporation) that anticipates a small net operating loss (NOL) for 2015 (and substantial net income in 2016) may find it worthwhile to accelerate just enough of its 2016 income (or to defer just enough of its 2015 deductions) to create a small amount of net income for 2015. This will permit the corporation to base its 2016 estimated tax installments on the relatively small amount of income shown on its 2015 return, rather than having to pay estimated taxes based on 100% of its much larger 2016 taxable income.
  • If your business qualifies for the domestic production activities deduction (DPAD) for its 2015 tax year, consider whether the 50%-of-W-2 wages limitation on that deduction applies. If it does, consider ways to increase 2015 W-2 income, e.g., by bonuses to owner-shareholders whose compensation is allocable to domestic production gross receipts. Note that the limitation applies to amounts paid with respect to employment in calendar year 2015, even if the business has a fiscal year.
  • To reduce 2015 taxable income, if you are a debtor, consider deferring a debt-cancellation event until 2016.
  • To reduce 2015 taxable income, consider disposing of a passive activity in 2015 if doing so will allow you to deduct suspended passive activity losses.
  • If you own an interest in a partnership or S corporation, consider whether you need to increase your basis in the entity so you can deduct a loss from it for this year. These are just some of the year-end steps that can be taken to save taxes. Again, by contacting us, we can tailor a particular plan that will work best for you. We also will need to stay in close touch in the event that Congress revives expired tax breaks to assure that you don’t miss out on any resuscitated tax-saving opportunities.  

***

Tax

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

Front Matter with Foreword by Jason Dyken MD MBA

logos

“BY DOCTORS – FOR DOCTORS – PEER REVIEWED – FIDUCIARY FOCUSED”

***

More Practitioners, Prognosticators and Portfolio Pain

Join Our Mailing List

 “Altitude Sickness,” or Value Asphyxiation?

vitaly[By Vitaliy N. Katsenelson CFA]

“Asphyxiation is a condition in which the body doesn’t receive enough oxygen.”

That’s how I started another column awhile back , in which I explained how the recent U.S. equity market highs have been creating “altitude sickness,” or value asphyxiation, for investors. If you look down from 30,000 feet, the market is trading at a significant premium to its average long-term valuation, especially if you normalize earnings for sky-high profit margins.

The Trench View

The view from the trenches is not much different. I spend a lot of time looking for new stocks, either by screen or by reading or talking to other value investors. We are all having a hard time finding many stocks of interest. In fact, we’ve been doing a lot more selling than buying.

I often get asked a question: Are we in a bubble? Bubble is a word that has been thrown around a lot lately. There may be an academic definition of what a bubble is — probably something to do with valuations at least a few standard deviations from the mean — but I don’t really care what it is. (Only academics believe in normal distributions.)

The Practitioner’s View

From the practitioner’s perspective, a bubbly valuation occurs when the price-earnings ratio of a company is so high that its earnings will have a hard time growing into investors’ expectations. In other words, the stock is so expensive that investors holding it will find it difficult to realize a positive return for a long time (think of Cisco Systems, Microsoft and Sun Microsystems in 2000). There are some bubbly stocks in the market today. Most years you see some, but today there are probably a few more than usual.

We see a lot of overvalued or fully valued stocks. Expectations (valuations) of those stocks have already more than priced in rosy earnings growth scenarios. If these scenarios play out, investors will likely make very little money, as earnings growth will merely offset P/E compression. But here is where it gets interesting: The line between overvalued and bubbly stocks is often very murky. If the economy’s growth is lower than expected or corporate profit margins revert toward the mean (or, in the situation we have today, decline), the return profiles of these stocks will not be substantially different from those of the bubbly ones. Unfortunately for the value-asphyxiated investor, there are a lot of stocks that fall into this overvalued bucket.

It is very hard for investors to remain disciplined and stick to an investment process. Selling overvalued stocks is hard, because every sell decision brings consequent pain as overvalued stocks that are not aware you’ve sold them keep on marching higher. Just as Pavlov’s dog responded to a bell, the pain of selling teaches us not to sell.

More Pain

If that pain were not enough, cash keeps burning a hole in our portfolios. Cash doesn’t rise in value when everything else is rising; thus investors feel forced to buy. When you are forced into a buy or sell decision, the outcome will usually not be good. Forced buy decisions are usually bad buy decisions. Just because a stock looks less bad than the rest of the market doesn’t make it a good stock. Maybe its peer is trading at 23 times earnings and your pick is trading at “only” 19. Such relative logic is dangerous today, because it anchors you to a transitory environment that may or may not be there for you in the future (most likely not).

***

investmentcenter5

***

An Annoying Phase

We are in the most annoying phase of the investing calendar: the month when every market strategist and his dog have to make a prediction as to what the market will do next year. To be right in forecasting, you have to predict often. And market strategists do. In fact, they predict so often that no one remembers how often their predictions worked out. I am not knocking the prognosticators: That is their job. They predict and sound smart doing it — just like it’s the barber’s job to cut your hair and pretend he is concentrating on not cutting off your ear.

It is your job, however, not to pay attention to the predictors. They simply don’t know. They may have a gut feeling, but that feeling is worth as much as you pay for it — very little. To time the market, you have to forecast what the economy will do, which is also very difficult. The Fed has 450 economists working full time on that (half of them are Ph.D.s, but I am not going to hold it against them), and they have an amazingly poor track record. Then you have to figure out how other market participants will respond to the economics news — and that is incredibly difficult. Let’s say you nailed both of these tasks. You still need to predict the multitude of random events — a few of which may be very large black swans — that will show up in the next 12 months. There is a reason why they are called “random.”

Assessment

Though it is dangerous to drink the market’s Kool-Aid and celebrate, it is not time to be gloomy either. There is good news for all of us: Cyclical bull markets are here to absolve us from our “buy” sins. Not every stock in your portfolio is marching in rhythm to its fundamentals. Indeed, this market has lifted many stocks while divorcing them from their weak fundamentals. This absolution is temporary: Take advantage of it.

ABOUT

Vitaliy N. Katsenelson, CFA, is Chief Investment Officer at Investment Management Associates in Denver, Colo. He is the author of Active Value Investing (Wiley 2007) and The Little Book of Sideways Markets (Wiley, 2010).  His books have been translated into eight languages.  Forbes called him – the new Benjamin Graham.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

***

Don’t Forget About Year-End Investment Planning

Join Our Mailing List

danielBy Daniel J. Antokal MBA
[Financial Advisor]

As the year draws to a close, there might be a slew of tasks on your to-do list. One task to consider is setting up a meeting with your financial professional to review your investments. If you take the time to get organized now, it may help you accomplish your long-term goals more efficiently.

Here are some steps that might help:

Evaluate your investment portfolio

During the meeting with your financial professional, review how your overall investment portfolio fared over the past year and determine whether adjustments are needed to keep it on track.

Here are some questions to consider:

  • How did your investments perform during the year? Did they outperform, match, or underperform your expectations?
  • What caused your portfolio to perform the way it did? Was it due to one or multiple factors?
  • Were there any consistencies or anomalies compared to past performance?
  • Does money need to be redirected in order to pursue your short-term and long-term goals?
  • Is your portfolio adequately diversified, and does your existing asset allocation still make sense?

Addressing these issues might help you determine whether your investment strategy needs to change in the coming year.

Aim for balance

During the portfolio review process, look at your current asset allocation among stocks, bonds, and cash alternatives. You might determine that one asset class has outperformed the others and now represents a larger proportion of your portfolio than desired. In this situation, you might want to rebalance your portfolio.

The process of rebalancing typically involves buying and selling securities to restore your portfolio to your targeted asset allocation based on your risk tolerance, investment objectives, and time frame. For example, you might sell some securities in an overweighted asset class and use the proceeds to purchase assets in an underweighted asset class; of course, this could result in a tax liability.

***

statistics

***

Tax losses

If you own taxable investments that have lost money, consider selling shares of losing securities before the end of the year to recognize a tax loss on your tax return. Tax losses, in turn, could be used to offset any tax gains. When attempting to realize a tax loss, remember the wash sale rule, which applies when you sell a security at a loss and repurchase the same security within 30 days of the sale. When this happens, the loss is disallowed for tax purposes.

If you don’t want to sell any of your current investments but want to change your asset allocation over time, you might adjust future investment contributions so that more money is directed to the asset class you want to grow. Once your portfolio’s asset allocation reaches your desired balance, you can revert back to your previous strategy, if desired. Keep in mind that asset allocation and diversification do not guarantee a profit or protect against loss; they are methods used to help manage investment risk.

Your financial professional can help you understand how your investments may be affected by capital gains and other taxes. You can learn more about current tax laws and rates by visiting www.irs.gov.

Set goals for the coming year

After your year-end investment review, you might resolve to increase contributions to an IRA, an employer-sponsored retirement plan, or a college fund next year. With a fresh perspective on where you stand, you may be able to make better choices next year, which could potentially benefit your investment portfolio over the long term.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™ Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

Social Security Update

Join Our Mailing List

Congress to curtail two useful benefits

Rick Kahler MS CFPBy Rick Kahler MS CFP http://www.KahlerFinancial.com

Congress is about to curtail two little-known, but very useful, benefits of Social Security. These are the ability to file-and-suspend and to file a restricted application. At the time of this writing, Congress had not formally passed the bill but it was expected to pass within days.

Background

Remember when Paul Ryan proposed we extend the full retirement age for Social Security from age 67 to 69 over a 40-year time period? The media went ballistic. Senior citizen groups sponsored TV ads of Paul Ryan dumping grandma over the cliff. His proposal never saw the light of day.

Fast forward to the current Bipartisan Budget Act of 2015, a bill that will cost Social Security recipients far more in benefits in the near future than Ryan’s proposal. Yet there has been nowhere near the outcry from the media, either political party, or the President.

Why?

The benefits that the budget bill strips from the Social Security program are little known by the average American and a bit complex, even though they can add up to tens of thousands of dollars of immediate cash benefits for nearly all Social Security recipients.

What Congress passed, and the President says he will sign, ends a benefit called file-and-suspend. This applies to married couples. It allows the higher-earning spouse to file for Social Security at full retirement age (currently 66), but to suspend taking the benefit so it can increase by 8% a year until age 70. This enables the lower-earning spouse to begin receiving spousal benefits.

The legislation will disallow that benefit and restrict the lower-earning spouse from receiving the spousal benefit until the higher-earning spouse actually starts receiving payments. This means if you wait until 70 to take the highest monthly Social Security benefit possible, your spouse will also have to wait until you turn 70 to receive spousal benefits.

e1c4e4b6-7e92-415c-9af3-74c8f31dc42b

Example:

As an example, assume Dr. Tyler’s full retirement age benefit is $3,000 per month. Her spouse Dana, the same age, has a full retirement benefit of $500. Under the current program, Dana could receive three times more, or $1,500 a month, at age 66, even though Tyler suspends her right to begin receiving her monthly benefit. By waiting until age 70, she would see her benefit grow to closer to $4,000 a month. Under this legislation, Dana would have to wait until age 70 to take the $1,500 spousal benefit. This costs the couple $1,500 a month for four years, or $72,000.

The second benefit stripped under this act affects everyone covered under the Social Security program, whether married or not. It is known as filing a restricted application. Currently, when you hit full retirement age and decide to suspend taking your benefit, you have the option to change your mind at any time before age 70 and retroactively receive your benefits.

Example:

This benefit is incredibly valuable in certain cases. Suppose, for example, Dr. Edgar has decided to wait until age 70 to begin receiving benefits but, at age 69, he becomes terminally ill. He could file to retroactively claim all three years of lost benefits. If Edgar’s full benefit amount were $3000 a month, the total retroactive benefit would be $108,000. This option is wiped out under the legislation.

Those currently receiving these benefits will become grandfathered under the legislation and continue to receive them. However, anyone currently qualifying for file-and-suspend benefits but not receiving them has until six months after Congress passes the Budget Act to complete the filing process.

More:

Assessment

While not all Social Security recipients will be affected by these changes, for those who are the impact will be significant.

 Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

    [PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

The Central Banks are at it Again!

Join Our Mailing List
Central banks were at it again – and markets loved it!
Art
 ***
By Arthur Chalekian GEPC [Elite Financial Partners]
 ***
Several weeks ago, European Central Bank (ECB) President Mario Draghi surprised markets when he indicated the ECB’s governing council was considering cutting interest rates and engaging in another round of quantitative easing.
The Economist explained European monetary policy was heavily tilted toward growth before the announcement:
 ***
“The ECB is already delivering a hefty stimulus to the Euro area, following decisions taken between June 2014 and early 2015. It has introduced a negative interest rate, of minus 0.2%, which is charged on deposits left by banks with the ECB. It has also been providing ultra-cheap, long-term funding to banks provided that they improve their lending record to the private sector. And, most important of all, in January it announced a full-blooded program of quantitative easing (QE) – creating money to buy financial assets – which got under way in March with purchases of €60 billion ($68 billion) of mainly public debt each month until at least September 2016.”
***
Despite these hefty measures, recovery in the Euro area has been anemic, and deflation remains a significant issue. According to Draghi, Euro area QE is expected to continue until there is “a sustained adjustment in the path of inflation.” Europe is shooting for 2 percent inflation, just like the United States.
***
The People’s Bank of China (PBOC) eased monetary policy last week, too. On Monday, data showed the Chinese economy grew by 6.9 percent during the third quarter, year-over-year. Projections for future growth remain muted, according to BloombergBusiness. On Friday, the PBOC indicated it was cutting interest rates for the sixth time in 12 months.
***
stock-exchange
 ***
U.S. markets thrilled to the news. The Dow Jones Industrial Average, Standard & Poor’s 500 Index, and NASDAQ were all up more than 2 percent for the week. Many global markets delivered positive returns for the week, as well.
***
Conclusion
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™ Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

 ***

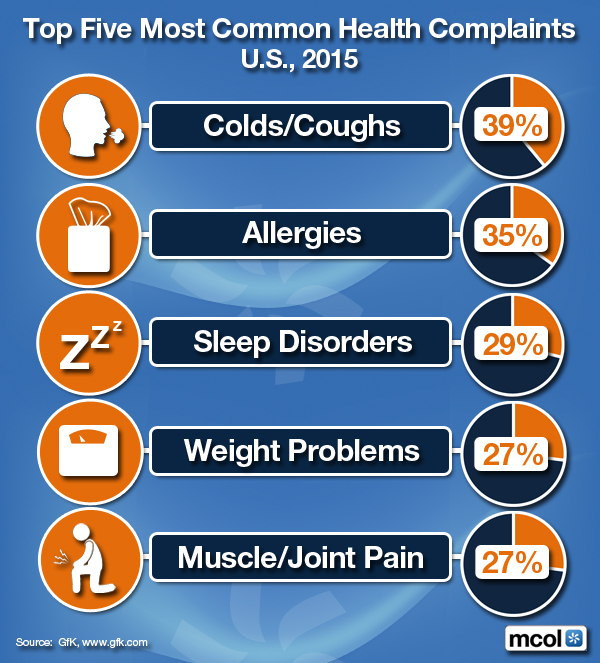
The Most Common Health Complaints in the USA

Join Our Mailing List

The Top  Five [5] Complaints – 2015

By http://www.MCOL.com

ImageProxy

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

Our Brain, Computer Operating Systems and Financial Decision Making

Join Our Mailing List

Our default brain operating system is programmed to make poor financial decisions?

Rick Kahler MS CFPBy Rick Kahler MS CFP® http://www.KahlerFinancial.com

If you’ve ever struggled to learn new software or unravel a computer problem, you know that part of the frustration of dealing with technology is its logic. Computers respond according to their default operating systems. If we want them to do something different, they need to be reprogrammed.

In the same way, the default operating systems of our brains are actually programmed to make poor financial decisions. This is normal. Making good financial decisions actually takes a deliberate reprogramming of your internal operating system. Here is why.

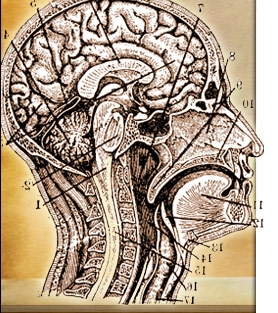
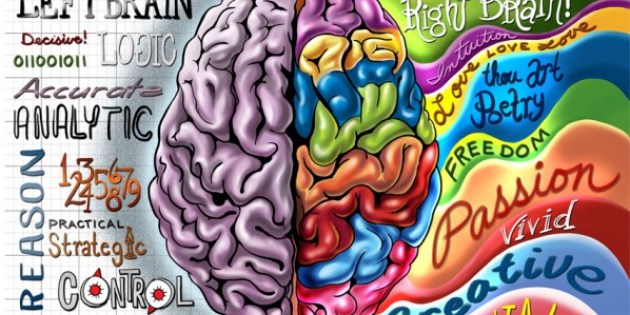
Our brains are divided into three sections: the reptilian brain, the mammalian brain, and the prefrontal cortex.

The reptilian brain is the oldest, most primitive part. In a talk at the Financial Therapy Association’s annual conference in July 2015 in San Jose del Cabo, Mexico, Dr. Ted Klontz explained that the reptilian brain continually scans for threats. It is waiting for death to come walking through the doorway, so it lives in anxiety. Since anything positive is not a threat, it’s oblivious to the positive. It also doesn’t understand the concept of the future, but lives only in this moment.

Left to its own programming, then, of course the reptilian brain might have a problem making monthly contributions to a retirement account. Saving for the future isn’t a concept it even understands. Further, it sees taking money out of the checkbook as a threat because that leaves fewer resources to battle death when it comes through the doorway. Making things even worse, the reptilian brain is nearly impossible to change. The best most of us can do is manage it.

***

Brain view

***

This brings us to the mammalian brain, whose only job is to manage the anxiety of the reptilian brain. It does so in three ways:

  1. Remove the threat (fight),
  2. Run away from the threat (flight),
  3. Get small and disappear to hide from the threat (freeze).

Most of us favor one of these three responses to threats, and according to Dr. Klontz we select our preferred response by the age of six. When the mammalian brain responds, it processes exponentially faster than the thinking part of our brain, the prefrontal cortex. Because of the ease with which the mammalian brain responds to threats, 90% of all decisions—including financial ones—are made here.

With the mammalian brain managing the anxiety of the reptilian brain, we have a more sophisticated response to our potential retirement plan contribution. Some of us will verbally fight and defeat any messenger (article, employer, financial advisor, spouse) that suggests we drain our current resources to send money into a black hole. Others will simply flee the messenger by diverting our attention to the Monday night football game or any task at hand. A portion of us will just freeze into a glassy-eyed stare. Nobody is home.

That leaves us with our only hope, the understanding and thinking part of the brain, the prefrontal cortex. This part of our brain doesn’t fully come on line until the mid-twenties. It functions as the parent of the other two brains, but unfortunately it processes information very slowly and with great effort.

***

brain

***

More:

Assessment

Fortunately, this is the brain that is easiest to change. By training it to become aware when the lower parts of the brain are about to make a hair-trigger decision, we can stop the ensuing action long enough to add logic as well as emotion to the process.

More:

Reprogramming the brain takes time, practice, and using resources like education, mentors, advisors, and counseling. Eventually, wise financial choices like saving for retirement can become the new default programming, even in spite of the reptilian brain.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

***

A primer to tonight’s GOP debate

Join Our Mailing List

Health Entitlements & the Deficit

By Nancy Chockley PhD

NIHCM.org

Congress is poised to pass a budget plan that will raise funding levels for the next two years. While these changes are paid for, the plan does not include structural changes to the health entitlement programs that are a leading driver of our budget deficits and mounting debt.

The GOP presidential candidates are likely to discuss a variety of proposals for structural reforms to these programs during tonight’s debate.

As a primer to this important conversation, this chart story presents essential facts about spending for Medicare, Medicaid and the Affordable Care Act and the impact of these programs on the deficit.

http://www.nihcm.org/health-entitlement-spending-a-growing-threat#one

business-valuation1

See the rest of the story

***

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

On Value Investor Guy Spier

Join Our Mailing List

What I Learned from Value Investor Guy Spier 

By Vitaliy N. Katsenelson CFA

***

A few months ago I was asked by the CFA Institute to give talks to CFA societies in London (October 27), Zurich (October 29) and Frankfurt (November 3). I enjoy giving occasional talks (but only a few a year, otherwise they become a chore). I also love Europe — history, old buildings and cultures, museums, sometimes a mild adventure. But this offer was much more interesting — I was asked to give a joint presentation with Guy Spier.

About  Guy

Guy Spier is a tremendous value investor who happens to be a good friend whose company I truly enjoy. He is the most cosmopolitan person I know. He was born in South Africa, spent his childhood in Iran and Israel, received his bachelor’s degree from Oxford and MBA from Harvard, lived in New York and in 2008 got sick of the New York hedge fund rat race and moved with his family to Zurich. His wife, Lory, is Mexican, so in addition to being fluent in languages of all the above-mentioned countries, he romances in Spanish.

Last year Guy published a book, The Education of a Value Investor: My Transformative Quest for Wealth, Wisdom, and Enlightenment. It is not a traditional investing book. In fact, I’ll say that differently: This is the most untraditional book on investing you’re likely to run into. It is a self-effacing memoir of Guy’s transformation from a Gordon Gekko wannabe who believes that his Ivy League education entitles him to Wall Street riches to a committed follower of Warren Buffett and his sidekick, Charlie Munger.

It must have taken a lot of guts and self-confidence (overcoming a lot of self-doubt) to write this book. To be honest, I am not sure I could have written it. It is one thing to strive for intellectual honesty; it is another to unearth and expose one’s own greed, arrogance and envy. Many of us are trying to hide such character traits in plain sight, never mind telling the world about them in a popular book.

After all, Guy is not writing about a fictional character; he is writing about himself. The humility he displays is what makes the book so effective — you can clearly follow the deliberate transformation of a cockroach (the Wall Street version of a caterpillar) into a butterfly.

This memoir is able to achieve something that many other investments books don’t (including my own): It reveals the real, practical, behavioral side of investing, not the way you read about it in behavioral finance textbooks but the raw emotions every investor experiences.

There are a lot of lessons we can learn from Guy. The first one — and, for me, the most important one — is that environment matters.

***

value

[Eye for Value]

Enter Dan Ariely PhD

Dan Ariely PhD, the well-known behavioral economist, was interviewed on Bloomberg Television and asked, What can one do to lose weight? He said, Start with the environment around you. If you come to work and there is a box of doughnuts on your desk, losing weight is going to be difficult. Also, look in your fridge: All the stuff that is probably not good for your diet is staring you in the face, whereas the fruits and vegetables that are essential to healthy eating are buried in the hard-to-access bottom drawers.

The same applies to investing: We may not notice it, but the environment around us impacts our ability to make good decisions. Guy writes, “We like to think that we change our environment, but the truth is that it changes us. So we have to be extraordinarily careful to choose the right environment — to work with, and even socialize with, the right people.”

I have found that checking the prices of stocks I own throughout the day shrinks my time horizon, impacts my mood and wastes my brain cells as I try to interpret data that have very little information. I am getting better; I am already down checking prices only once a day. My goal is to do it just once every few days.

Guy is ahead of me: He checks them once a week. Recently, I put in price alerts for stocks my firm owns or follows. If a stock price changes more than 10 percent or crosses a certain important (buy or sell) point, I’ll get an e-mail alert.

Guy finds that he isn’t effective when he gets to the office because of external distractions. In his Zurich office he has a quiet room that he calls the library. It doesn’t have phones or computers, and this is where he reads, thinks and naps. Here in Denver, I have a lawn chair (bought at Costco for $50) that I take outside to sit on, put on headphones, and listen to music and read. My friend Chris goes to Starbucks or the local library in the morning for four hours before he goes to his office, and that’s where he does his reading. The key is to figure out what works for you and try not to fight your external environment.

Another lesson I have learned is that misery loves company. I was talking to Guy about his book, and he told me that people who love the book appreciate the fact that he is so honest about the emotions that consume him when he is struggling in the stock market. As investors, we often put on a brave face, but if we aren’t emotionally honest, our opinion of ourselves, our self-worth, may fluctuate with the performance of our portfolio.

Personally, I can really relate to this. When I read Guy’s book the first time (I’ve read it twice), I was going through a tough time with my portfolio. I found this book extremely therapeutic. In fact, I recommended it to a friend of mine who was going through a similar rough patch.

Another lesson:

Surround yourself with the right people. Friendships matter. I’ve been blatantly plagiarizing Guy on this for years. Guy created a conference called VALUEx Zurich, a gathering of like-minded people who get together and share investment ideas. I attended the very first one in 2010, and since then I have hosted a very similar event, VALUEx Vail, every year in June.

Guy has a latticework group of eight investors that meets every quarter and discusses the stock market, the investment process and personal issues. I’ve copied that, too. Four of us got together in Atlanta in October. We visited a few companies and debated stocks, industry trends, diets, women . . . okay, you get the point. That was our first latticework event, but I hope we’ll meet a few times a year.

Attending Guy’s conference in Zurich and organizing VALUEx Vail have resulted in enduring friendships. These conferences allowed me to create a large network of like-minded investors I talk to regularly. Every member of my latticework group I met at VALUEx Vail.

(A short side note: One of the most important things we can do as parents of teenage kids is to make sure they have good friends. That’s paramount. We as parents lose influence on our kids when they become teenagers. Their friends have a disproportionately larger impact on their choices than we do. We can influence the environment around our kids by helping them select friends.)

And then there are thank-you cards. Over the years Guy has written tens of thousands of them. He is indiscriminate about them — at one point he wrote to every employee at a boutique hotel he stayed in. All right, maybe he took it too far that time. But, writing a thank-you card to value investor Mohnish Pabrai changed his life. He attended Pabrai Investment Funds’ annual meeting in Chicago. After the meeting he sent Pabrai a thank-you note. A few months later Pabrai came to New York and invited Guy to dinner. This was the start of the Spier-Pabrai bromance. Thank-you cards work because so few people write them. They leave a lasting impression on the receiver because they say, “I like you. You are important to me.”

***

stock-exchange

[Stock-Exchanges]

Mentors

The last point is, Be yourself. Having mentors is important. For many value investors, Buffett and Munger are our north stars. There are lots of things we can learn from them. But we also have to realize that we must be ourselves, because we are not them. I remember reading a long time ago that Buffett did not do spreadsheets. That impacted me for a few months — I stopped building models and creating spreadsheets. I thought, If Buffett doesn’t do it, I shouldn’t do it either. Wrong.

Buffett is a lot smarter than I am; he is able to analyze companies in his head. He is Buffett. I have found that spreadsheets work for me because they help me think. When Buffett and I look at a company philosophically, we are looking for the same things, but I need a computer to assist me, and he doesn’t.

Mohnish Pabrai owns just a handful of stocks. Guy, on the other hand, knows that he would not be able to be a rational decision maker if he had only a handful of stocks. There will be a significant overlap between Guy’s and Pabrai’s portfolios, but Guy’s will have two or three times as many stocks.

Assessment

Dear ME-P Readers, I spoke with your Editor-in-Chief Dr. Dave Marcinko a few weeks ago, and as you can tell from this ME-P essay, I am a very biased book reviewer. I am not even sure this qualifies as a book review. Despite my biases, I can safely say that The Education of a Value Investor is one of the best books I’ve read in 2015. (I promise you that it is not the only book I’ve read this year.) Before you commit your time and money to this book, watch Guy’s presentation on Talks at Google.

ABOUT

Vitaliy N. Katsenelson, CFA, is Chief Investment Officer at Investment Management Associates in Denver, Colo. He is the author of Active Value Investing (Wiley 2007) and The Little Book of Sideways Markets (Wiley, 2010).  His books have been translated into eight languages.  Forbes called him – the new Benjamin Graham.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

***


Knowing the Difference Between Stock Value and Price

Join Our Mailing List

A Motley Fool Interview

vitaly

ABOUT

Vitaliy N. Katsenelson CFA is Chief Investment Officer at Investment Management Associates in Denver, Colo. He is the author of Active Value Investing (Wiley 2007) and The Little Book of Sideways Markets (Wiley, 2010).  His books were translated into eight languages.  Forbes Magazine called him “The new Benjamin Graham”.  

The Motley Fool,

Our own Editor Dr. Dave Marcinko recently spoke with Vitaliy, as well as The Motley Fool’s James Early and Rana Pritanjali. Vitaliy explained how he helps investors see the difference between a stock’s value and its price, as well how he assesses macroeconomic trends when investing.

Assessment

Plus, Vitaliy predicted the next category Apple will disrupt: the automotive industry.

You can listen and read the full interview here.

PS: You can read Manifesto – The Values of Value Investing, here.

I hope you enjoy it  – Ann Miller RN MHA [Managing Editor]

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™                    Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

Seeking Comments on iMBA Inc’s New Financial Planning and Medical Risk Management Textbooks for Doctors

For DOCTORS Only!

Tell us What You Think?

***

http://www.BusinessofMedicalPractice.com

Join Our Mailing List

***

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

 Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

http://www.CertifiedMedicalPlanner.org

[Education and Certification Program for Financial Advisors]

***

Healthcare Costs During Retirement

Join Our Mailing List

Estimations ….

By http://www.MCOL.com

***

ImageProxy.mvc

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

How quickly market Emotions have changed since August – Worry?

Join Our Mailing List

It’s already priced into the markets … according to some experts!

By Arthur Chalekian GEPC [Elite Financial Partners]

ArtThe Markets UPDATE

***
How quickly emotions have changed since August. Worry? Angst? It’s already priced into the markets, according to some experts.
 
Last week, Barron’s published the results of its Big Money Poll, a biannual survey of professional investors and money managers. A majority of those surveyed (55 percent) were bullish about U.S. markets’ prospects through June 2016, 29 percent were neutral, and 16 percent were bearish. That’s a big shift. Last spring, just 45 percent of those polled were bullish and nearly one-half were neutral. This time around, things are different:
 
“After a wild and crazy summer for U.S. stocks, marked by an 11 percent correction in August, Wall Street’s bulls are showing conviction again…the pros expect stocks to rise by as much as 7 percent through the middle of 2016, propelled by a growing economy and gains in corporate profit. The Big Money investors see fresh value in beaten-up energy stocks and financials, as well as dividend-paying blue chips. And, they don’t expect a likely interest-rate hike – when it comes – to break the bull’s stride for long.”
 
Investors who participated in the American Association of Individual Investors’ October 14 Sentiment Survey weren’t quite so optimistic. The survey showed just 34 percent of investors were bullish, 39 percent were neutral, and 27 percent were bearish. The bulls were down 3 percent from the previous week, and the bears gained a percent. Uncertainty seemed to be the name of the game, though, as the number of investors who held neutral opinions increased by 4 percent.
 
As an interesting side note, the professionals surveyed by Barron’s estimated the number of investors who weren’t sure where markets are headed was much larger – 76 percent!
***
businessmen-384741_640
 ***
Assessment
If you’re a contrarian – an investor who does not subscribe to popular opinion – there are a lot of opinions to consider.
***
Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

***

What is the Glass-Steagall Act?

Join Our Mailing List

[Staff reporters]

According to NEIL IRWIN; it is the 82-Year-Old Banking Law That Stirred a Debate!

What is the Glass-Steagall Act [Banking Act of 1933]?

When people talk about banking, they are talking about two broad classes of activities.

Commercial banking is what happens at your neighborhood branch: You deposit money in a checking or savings account, and the bank uses those deposits to make loans to consumers or small businesses.

Investment banking refers to the kind of banking activity more common on Wall Street, like helping large companies issue stock or bonds in order to fund themselves, and trading securities in hope of making a profit.

The government’s response was the Banking Act of 1933, commonly known as the Glass-Steagall Act (for the bill’s sponsors, Senator Carter Glass of Virginia and Representative Henry Steagall of Alabama), which required that commercial banking and securities activities be separated, not to take place within the same financial institution.

More: The Three Types of Banks

***

Bank

***

More:

Assessment

So, here is a look at why the Democratic presidential candidates Bernie Sanders and Martin O’Malley want to reinstate it.

TERMS: Investment Banking DR. MARCINKO

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

***

The Case for Value Based Medical Care

Join Our Mailing List

Migrating from Volume to … Value

By http://www.MCOL.com

***

ImageProxy

***

Assessment

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[PRIVATE MEDICAL PRACTICE BUSINESS MANAGEMENT TEXTBOOK – 3rd.  Edition]

Product Details

  [Foreword Dr. Hashem MD PhD] *** [Foreword Dr. Silva MD MBA]

***

FREE! In Swedish Medicine

Join Our Mailing List

An Interesting Innovation

dan-snapshot

[By Dan Ariely PhD]

I recently learned of an interesting innovation in medical pricing coming from Sweden.

This pamphlet from the healthcare authority states (translated):

“If you have a respiratory problem and you don’t take antibiotics for it during your first visit to the doctor, you have the right to a second visit within five days free of charge”.

Read more about this approach here …

FREE! In Swedish Medicine

More:

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

***

198174

***

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

Are the ME-P and Ashley Madison Related?

Join Our Mailing List

On Ransom-Ware, Black-Hat Hackers, the Gullible, Guilty … and Personal Cyber Security

A-Special ME-P Report

*** 

DEM white shirt

By Dr. David E. Marcinko MBA MBBS [Hon]

[Publisher-in-Chief]

Your Ashley Madison Account
[Paul recommends to read this email]‏
But … don’t fall for it!

I just received this email message from sharingservices@aol.com: In this time of medical information and financial advisory data cyber security breaches, here is a warning about personal security, too!

If it can happen to me, it can happen to anyone!

*********************************************************************************************************

Unfortunately your data was leaked in the recent hacking of Ashley Madison and I know have your information. I have also used your user profile to find your Facebook page, using this I can now message all of your friends and family members.

If you would like to prevent me from sharing this dirt info with all of your friends and family members (and perhaps even your employers too?) then you need to send 1 bitcoin to the following BTC address.

Bitcoin Address:
1AEJiZFnELwRZVjmVSvDSwUaXNZy4X9bQN

You may be wondering why should you and what will prevent other people from doing the same, in short you now know to change your privacy settings in Facebook so no one can view your friends/family list. So go ahead and update that now (I have a copy if you don’t pay) to stop any future emails like this.

You can buy bitcoin using online exchanges easily. If the bitcoin is not paid within 3 days of 23 Sep 2015 then my system will automatically message all of your friends and family members. The bitcoin address is unique to you.

Consider how expensive a divorce lawyer is. If you are no longer in a committed relationship then think about how this will affect your social standing amongst family and friends. What will your friends and family think about you?

Sincerely,
Paul

***

hackers

*******************************************************************************************************************

An Object lesson to all ME-P readers and subscribers

After review, I noted the following faults with this blast message:

* No sender last name.
* Sender blast email service
* Multiple email addresses
* Poor grammar
* I do not have – or ever had – a Facebook account
* I do not have – or ever had – an AM account

Assessment

Note any other “give-aways“? Don’t fall for this ploy. And, don’t be Gullible or GuiltyForewarned is forearmed.

More:

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Product DetailsProduct DetailsProduct Details

Product Details

Product DetailsProduct Details

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

R U A Genius?


Join Our Mailing List

Well – Are You?

[By staff reporters]

Assessment

Or – just average?

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Sponsors Welcomed

Credible sponsors and like-minded advertisers are always welcomed.

Advertising Info:

all together

Investors are allowed to change their minds

Join Our Mailing List 
The Markets
Art

By Arthur Chalekian GEPC

[Financial Consultant]

***

They’re investors. They’re allowed to change their minds.
*** 
Just a few weeks ago, on September 17, the Federal Reserve Open Market Committee (FOMC) decided to leave the fed funds rate unchanged. In part, this was because, “Recent global economic and financial developments may restrain economic activity somewhat and are likely to put further downward pressure on inflation in the near term.”
 
The next day, September 18, stock markets tumbled. By the time September was over, many markets had closed on their worst quarter in four years, according to the BBC. The Dow Jones Industrial Average fell by almost 8 percent, Britain’s FTSE 100 was down 7 percent, Germany’s Dax was off by almost 12 percent, and the Shanghai Composite lost more than 24 percent.
 
Last week, on Thursday, the minutes of the FOMC meeting were released. Investors’ response was quite different. Barron’s reported many believe a rate hike during 2015 is less likely than it once was, and that reinvigorated investor optimism:
 
“Going into Friday’s session, global equity markets’ valuations were enriched by some $2.5 trillion, according to Bloomberg calculations. As for U.S. stocks, Wilshire Associates reckons that they tacked on 3.44 percent, or approximately $800 billion, over the full week, based on the gain in the Wilshire 5000 index, their biggest weekly gain in nearly 12 months.”
 
Why does the same news elicit two very different responses? There are many reasons. Foremost among them is the fact a lot of elements influence markets – investor confidence, company valuations, central bank actions, automated trading, and many others.
***
Stock_Market
***
Assessment
 
What does last week’s upward push mean? One analyst cited by Barron’s suggested we’re seeing a bear market rally, but only time will tell.
***
Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

How Companies Value Body Parts?

Join Our Mailing List
A ProPublica Price Check
By Lena Groeger and Michael Grabell
   ***
             

        ProPublica

                                                                      ***

Injured workers are entitled to compensation for permanent disabilities under state workers’ comp laws.

More:

***

body

Price Check: How Companies Value Body Parts

***

But – Texas has long allowed companies to opt out and write their own benefit plans.

More:

Assessment

Benefits for the same body part can differ dramatically depending on which company you work for.

Related Story »

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

 ***

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

Medicine: A Lesson In Efficient Markets

Join Our Mailing List

MEDICINE: A Lesson In Efficient Markets

dan-snapshot

[By Dan Ariely PhD] http://danariely.com

The market for medicine is incredibly interesting. Almost every day we learn something new about a treatment that we thought would work but does not, or about a treatment that we didn’t think would work but does.

Beyond the particular fascination, I think that the medicine market can also teach us important lessons about rationality … read more:

Medicine: A Lesson In Efficient Markets

More:

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

***

medical-cartoon

***

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[PRIVATE MEDICAL PRACTICE BUSINESS MANAGEMENT TEXTBOOK – 3rd.  Edition]

Product Details

http://www.BusinessofMedicalPractice.com

  [Foreword Dr. Hashem MD PhD] *** [Foreword Dr. Silva MD MBA]

***

It’s open enrollment season for health insurance – Now What!

Join Our Mailing List

How do I compare my health insurance options during open enrollment?

Daniel J. Antokal MBA
[Financial Advisor]

daniel

The decisions you make during open enrollment season regarding health insurance are especially important, since you generally must stick with the options you choose until the next open enrollment season, unless you experience a “qualifying” event such as marriage or the birth of a child. As a result, you should take the time to carefully review the types of plans offered by your employer and consider all the costs associated with each plan.

With most health insurance plans, your employer will pay a portion of the premium and require you to pay the remainder through payroll deductions. When comparing different plans, keep in mind that even though a plan with a lower premium may seem like the most attractive option, it could have higher potential out-of-pocket costs.

You’ll want to review the copayments, deductibles, and coinsurance associated with each plan. This is an important step because these costs can greatly affect what you end up paying out-of-pocket.

When reviewing the costs of each plan, consider the following:

  • Does the plan have an individual or family deductible? If so, what is the amount that will have to be satisfied before your insurance coverage kicks in?
  • Are there copayments? If so what amounts are charged for doctor visits, specialists, hospital visits, and prescription drugs?
  • Will you have to pay any coinsurance once you’ve satisfied the deductible?

Specific features

You should also assess each plan’s coverage and specific features. For example, are there coverage exclusions or limitations that apply? Which expenses are fully or partially covered? Do you have the option to go to doctors who are outside your plan’s provider network? Does the plan offer additional types of coverage for vision, dental, or prescription drugs?

***

healthcare

***

Assessment

In the end, when reviewing your options, you’ll want to balance the coverage and features offered under each plan against the plan’s overall cost to determine which plan offers you the best value for your money. 

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[PHYSICIAN FOCUSED FINANCIAL PLANNING AND RISK MANAGEMENT COMPANION TEXTBOOK SET]

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

Finally – Why the Healthcare.gov Site Failed?

Join Our Mailing List

No … Really!

By Robert E.H. Khoo MD FRCS(C) FACS

http://www.colondoc.com

***

health care gov

Why the Healthcare.gov Site Failed

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Product Details

***

EHR Meaningful Use Rules Finalized

Join Our Mailing List 

The CMS Modifications

[By staff reporters]

Source: Joseph Goedert, Health Data Management [10/7/15]
***
Centers for Medicare and Medicaid Services
***
The Centers for Medicare and Medicaid Services has issued a 752-page final rule covering three components of the electronic health records meaningful use program. The rule finalizes modifications to Stages 1 and 2; the 2015 edition of electronic health records certification criteria; and Stage 3 of meaningful use.
Modifications
Under the modifications to Stages 1 and 2, eligible professionals have 10 meaningful use objectives, down from 18 previously. In Stage 3, there are 8 objectives for eligible professionals and hospitals, and more than 60 percent of measures require interoperability.
Assessment
The entire rule is available here.
***
MD with eHR
***
Conclusion
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

EHRs in the News – GAG!

Join Our Mailing List

A Recent Round-Up

1-darrellpruitt[By D. Kellus Pruitt DDS]

“Feds push forward with controversial health rule – The Obama administration is moving ahead with controversial new rules that require doctors to switch to electronic health records or face fees, resisting calls from both parties to delay implementation.”

By Sarah Ferris for The Hill, October 6, 2015

http://thehill.com/policy/healthcare/256120-feds-push-forward-with-controversial-health-it-rule?utm_content=buffer9cd4b&utm_medium=social&utm_source=twitter.com&utm_campaign=buffer

“The Gag Clause is Killing Us – Doctors are barred from discussing safety glitches in software…  And what if doctors — your doctor — is unable to make problems with EHR programs public, due to a so-called ‘gag clause’ written into the contract with the software company, which forbids sharing and publishing, in any form, of potentially dangerous flaws in the IT systems? This is already happening.”

By Deirdre Reilly for HealthZette, October 6, 2015

http://www.lifezette.com/healthzette/gag-clause-is-killing-us/

 “Hackers target Australian health sector, selling records for A$1,000 – Hackers are targeting the Australian health sector, with fully populated digital health records sold on the black market for up to A$1,000 each [$720 US].”

By Beverley Head for ComputerWeekly.com, October 7, 2015

http://www.computerweekly.com/news/4500254986/Hackers-target-Australian-health-sector-selling-records-for-A1000 

 “Electronic health records software often written without doctors’ input – The reason why many doctors find electronic health records (EHR) difficult to use might be that the software wasn’t properly tested, researchers suggests.”

By Kathryn Doyle for Reuters, October 7, 2015

http://www.reuters.com/article/2015/10/07/us-health-software-ehr-idUSKCN0S11OY20151007

 “EHRs provide long-term savings, convenience.”

(no byline), American Dental Association, ADA News, December 6, 2013

http://www.ada.org/en/publications/ada-news/2013-archive/december/ehrs-provide-long-term-savings-convenience

 ***EHR

***

More:

  1. The Percentage of Office-Based Doctors with EHRs
  2. Do Nurses like EHRs?
  3. EHRs – Still Not Ready For Prime Time
  4. The “Price” of eHRs

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[HOSPITAL OPERATIONS, ORGANIZATIONAL BEHAVIOR, HIT AND FINANCIAL MANAGEMENT COMPANION TEXTBOOK SET]

Product DetailsProduct Details

[Foreword Dr. Phillips MD JD MBA LLM] *** [Foreword Dr. Nash MD MBA FACP]

***

The third quarter for 2015 was a REAL humdinger!

 Join Our Mailing List
The Markets – Update
Art

By Arthur Chalekian GEPC

[Financial Consultant]

Well, the third quarter for 2015 was a REAL humdinger!
                                            ***
It began with the first International Monetary Fund (IMF) default by a developed country (Greece) and finished with Hurricane Joaquin possibly headed toward the east coast. In between, China’s stock market tumbled, the Federal Reserve tried to interpret conflicting signals, and trade growth slowed globally. After such a stressful quarter, we may see an uptick in the quantity of alcoholic beverages consumed per person around the world. That number had declined (along with economic growth in China) between 2012 and 2014, according to The Economist.
***
No Grexit – for now
Despite defaulting on its IMF loan, rejecting a multi-billion-euro bailout plan, and closing its banks for more than two weeks, Greece was not forced out of the Eurozone. Instead, Europe cooked up a deal that left the IMF unhappy and analysts shaking their heads. The Economist reported the new deal for Greece was an exercise in wishful thinking. The problem is the deal relies on “the same old recipe of austerity and implausible assumptions. The IMF is supposed to be financing part of the bailout. Even it thinks the deal makes no sense.” It’s a recipe we’re familiar with in the United States: When in doubt, defer the problem to the future.
***
A downturn in China
Despite reports from the Chinese government that it hit its economic growth target (7 percent) on the nose during the first two quarters of the year, The Economist was skeptical about the veracity of those claims. During the first quarter.
***
“Growth in industrial production was the weakest since the depths of the financial crisis; the property market, a pillar of the economy, crumbled. China reported real growth (i.e., after accounting for inflation) of 7 percent year-on-year in the first quarter, but nominal growth of just 5.8 percent.”
***
That statistical sleight of hand implies China experienced deflation early in the year. It did not.
On a related note, from mid-June through the end of the third quarter, the Shenzhen Stock Exchange Composite Index fell from 3,140 to about 1,716, according to BloombergBusiness. That’s about a 45 percent decline in value.
***
Red light, green light at the Federal Reserve
Green light: employment numbers. Red light: consumer prices, inflation expectations, wages, and global growth. Late in the quarter, the Federal Reserve decided not to begin tightening monetary policy.
According to Reuters, voting members of the Federal Open Market Committee (FOMC) decided uncertainty in global markets had the potential to negatively affect domestic economic strength. They may have been right. The Wall Street Journal reported, although unemployment remained at 5.1 percent, just 142,000 jobs were added in September. That was significantly below economists’ expectations that 200,000 jobs would be created. The Journal suggested the labor market has downshifted after 18 months of solid jobs creation.
***
Global trade in the doldrums
The global economy isn’t as robust as many expected it to be. According to the Business Standard, the World Trade Organization (WTO) lowered its forecast for global trade growth during 2015 from 3.3 percent to 2.8 percent. Falling demand for imports in developing nations and low commodity prices are translating into less global trade. Expectations are trade growth will be 3.9 percent in 2016, which could help support global economic growth.
***
Coming Change
America’s share of the global economy is potent. Our country accounts for 16 percent (after being adjusted for currency differences) of the world’s gross domestic product (GDP) and 12 percent of merchandise trade.
Again, according to The Economist, we dominate “the brainiest and most complex parts of the global economy.” Our presence is strong in social media, cloud computing, venture capital, and finance. In addition, the dollar is the world’s dominant currency. While the view from the top is pleasing, we may not be there forever. The Economist explained:
***
“In the first change in the world economic order since 1920-45, when America overtook Britain, [America’s] dominance is now being eroded. As a share of world GDP, America and China (including Hong Kong) are neck and neck at 16 percent and 17 percent respectively, measured at purchasing-power parity. At market exchange rates, a fair gap remains with America at 23 percent and China at 14 percent … But any reordering of the world economy’s architecture will not be as fast or decisive as it was last time…the Middle Kingdom is a middle-income country with immature financial markets and without the rule of law. The absence of democracy, too, may be a serious drawback.”
***
It may be hard to believe, in light of recent economic and market events in China, but change is on its way. Regardless, the influence of the United States should continue to be powerful well into the future.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

Front Matter with Foreword by Jason Dyken MD MBA

logos

“BY DOCTORS – FOR DOCTORS – PEER REVIEWED – FIDUCIARY FOCUSED”

***

About DocGraph.Org

Join Our Mailing List

Discover, Create and Analyze Open Healthcare Data
[By staff reporters]
 ***
DocGraph is a community composed of data journalists, scientists, and advocates; with three core iniatives:

I. Community Collaboration 

The DocGraph community includes academics, journalists, doctors, entrepreneurs, statisticians and more. Our members have used DocGraph datasets to restructure provider networks, teach classes, start companies, and report on quality metrics. We welcome anyone with passion for healthcare improvement to join us.

If you write about healthcare data and would like to be featured on our blog, or if you are a data scientist interested in publishing research using DocGraph data, please give us a holler too!

II. Open Healthcare Data Advocacy 

Our efforts led to the first national Provider Referral data release by the US government. The original “DocGraph Data” has helped researchers, journalists, and companies around the nation to provide data-backed healthcare solutions.

We continue to work with federal, state, private, non-profit, and public entities to create and open healthcare datasets. We believe the release of reliable and current data is vital to the improvement of the healthcare system.

III. The DocGraph Alliance 

The DocGraph Alliance is a group of organizations committed to supporting data journalism and data science community efforts.

Its community mission is to encourage an ecosystem of innovators to collaborate and share tools and research methodologies around open healthcare datasets.Support from the Alliance members means the DocGraph Journal can continue providing support for the growing community of data scientists focused on leveraging initiatives of transparency in healthcare.

***

gears

***

Assessment

Visit http://www.docgraph.org today. And, for the premier analytical software built on DocGraph data, visit CareSet.com

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

New Tools for A Healthy Future

Join Our Mailing List

By Terri D. Wright, PhD, MPH                   

***

ImageProxy

***

APHA’s Policy Center Creates Tools for A Healthy Future

DEAR DAVID – The central challenge of the American Public Health Association is to create the healthiest nation in one generation. APHA’s Center for Public Health Policy was established almost 10 years ago to bring together analytical public health expertise and infuse the public health field with expert materials and tools in response to this challenge.

The Center embraces the public health issues that threaten population health. Our work is done through national and state partnerships and by leveraging resources across multiple sectors, including government, philanthropy and non-profit. Fundamental to all that we do: strategies to ensure health equity for all.

We invite you to learn about our work and stay abreast of our progress on producing resources for our members and constituents. The following priorities represent our core work to create a healthy nation:

  • Assuring health equity for all.
  • Promoting systems transformation to integrate public health and health care and improve population health.
  • Improving the natural and built environments to support health and create environmental justice.

We will keep you updated on our priority issues and encourage you to connect with our team.

We invite your feedback as we embark on this journey – phpolicycenter@apha.org

Sincerely,
Terri D Wright Signature

***

[HOSPITAL OPERATIONS, ORGANIZATIONAL [BEHAVIOR AND FINANCIAL MANAGEMENT COMPANION TEXTBOOK SET]

Product DetailsProduct Details

[Foreword Dr. Phillips MD JD MBA LLM] *** [Foreword Dr. Nash MD MBA FACP]

***

How Your Hospital Can Avoid Nomination as a Great Place to Work 

Join Our Mailing List

Are hospitals ranked according to employee happiness?

By Robert EH Khoo MD FRCS FACS  http://www.colondoc.com

SOAR

Earlier this month I read a Wall Street Journal article about Zeynep Ton’s Good Jobs Index. Who is Zeynep Ton? She is a professor at the Massachusetts Institute of Technology’s Sloan School of Management who has ranked retailers on employee happiness. This was so positive. It was good to hear about businesses concerned about employee happiness and not just about profits and shareholders.

Two weeks later I was dismayed to read about the bruising work environment at Amazon in the New York Times. The article described a work environment toxic to workers overseen by a CEO who has blind to this view.

I was curious. I work in a hospital. Are hospitals ranked according to employee happiness? My health system is recognized as a Great Place to Work and the Fortune 100 Best Companies to Work For.

Last year I left a hospital that was an ideal model of health care in the President’s eyes. Time Magazine had published two articles about that hospital. Yet my experience there as an employee was closer to the abusive atmosphere the New York Times detailed about Amazon.

I imagine that my old workplace could continue avoiding accolades from its employees by following these 14 steps:

***

Hospital with paper MRs

How Your Hospital Can Avoid A Nomination as a Great Place to Work 

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[HOSPITAL OPERATIONS, ORGANIZATIONAL BEHAVIOR AND FINANCIAL MANAGEMENT COMPANION TEXTBOOK SET]

Product DetailsProduct Details

[Foreword Dr. Phillips MD JD MBA LLM] *** [Foreword Dr. Nash MD MBA FACP]

***

An MD’s Venture Back to Microsoft Windows 10

Join Our Mailing List

A Review

By Robert E.H. Khoo MD FRCS(C) FACS

http://www.colondoc.com.

***

disruptive

***

My Venture Back to Microsoft – a Review of Windows 10

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

Racial Disparities in Health Insurance Coverage

Join Our Mailing List

For 2013

By http://www.MCOL.com

***

ImageProxy

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

The Economic Impact of UnHealthy Bio-Metrics

Join Our Mailing List

For 20102 – 2014

http://www.MCOL.com

***

ImageProxy

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[HEALTH INSURANCE, MANAGED CARE, ECONOMICS, FINANCE AND HEALTH INFORMATION TECHNOLOGY COMPANION DICTIONARY SET]

      Product DetailsProduct DetailsProduct Details

[Mike Stahl PhD MBA] *** [Foreword Dr.Mata MD CIS] *** [Dr. Getzen PhD]

***

Ben Bernanke: Buy One Suit, Get Three Free

Join Our Mailing List

Linear thinking is dangerous
vitaly[By Vitaliy Katsenelson, CFA]

Linear thinking is dangerous. It is the easiest form of reasoning, lying on the path of least resistance. The simpler the path, the more readily people will march along it. Linear arguments are easy to make, as they require the least amount of evidence — past data points with a straight line drawn through them.However, the larger the crowd that follows the wrong line of reasoning, the more people pile in, and the greater the consequences if they are proved wrong.

A lot of things in nature, and thus in investing, are not linear. A past trend may or may not persist into the future. Events don’t happen in a vacuum; they are observed, studied and capitalized on — which in the case of investing may preclude a company’s future from resembling its past. As I write this, I think of successful companies whose achievements attracted competition, which then marginalized them.

Some things are inherently nonlinear, their behavior reminiscent of a pendulum’s: The further they swing in one direction, the harder they’ll go in the opposite direction. It is very dangerous to default to linearity with such nonlinear phenomena, as the more confident we become in the swing (the more linearity we observe), the closer we are to the pendulum’s reversing course.

Price-earnings ratios often follow a pendulum behavior. If you look at high-quality dividend-paying stocks — the Coca-Colas and Procter & Gambles of the world — they are now changing hands at more than 20 times earnings. Their recent performance has driven linear thinkers to pile into them, expecting more of the same in the future. Don’t! These stocks were beneficiaries of a swing in the P/E pendulum as it went from low to average and then to above-average levels.

Pattern recognition is an important contributor to success in investing. Mark Twain once said that history doesn’t repeat itself, but it rhymes. If you can identify a rhyme (that is, see a pattern) relating to the current situation, then you can develop a framework to analyze and forecast it. But what if the current situation is very different — if it doesn’t rhyme with anything in the past? This is where the ability to draw parallels becomes helpful. It allows you to overlay rhymes (patterns) from other companies, industries or even fields. Building analogous frameworks is a cure for linear thinking; it helps us see nonlinearity and facilitates the creation of nonlinear mental models.

Then there is pseudolinearity: things that seem to be linear but are forced into linearity by extrinsic factors. This was a subtopic of my presentation at the Valuex Vail investing conference in June. I drew a parallel between two entities that suddenly looked analogous: Jos. A. Bank Clothiers, a Hampstead, Maryland–based retailer of men’s apparel, and the Federal Reserve.

***
rote

***

Jos. A. Bank

Jos. A. Bank has always been a very promotional retailer. It would jack up prices, then run sales for consumers happy to be deceived — a typical American retail tale. But sometime in 2008, Jos. A. Bank went promotional on steroids. You could not watch CNBC for an hour without seeing one of its ads. The company started out by encouraging you to buy one suit and get one free. Then you got two free suits. Finally, it started giving away Android phones with suit purchases. For a while this past March, Jos. A. Bank offered consumers the opportunity to buy one suit and get three free.

There are several problems with the strategy: It does not emphasize the quality of the suits or the company’s great service, and the ads aren’t helping to build a brand but are intended just to pimp sales at Jos. A. Bank, as if it were a grocery store with USDA choice beef on sale.

This brings us to the latest quarter. Jos. A. Bank’s same-store sales dropped 8 percent, but what really piqued my interest was this explanation by its CEO, R. Neal Black, during its earnings call in June: “Since 2008, at the beginning of the financial crisis and the recession, the overall sales picture has been one of volatility, and strong promotional activity has been consistently and effectively driving our sales increases. This strategy was designed with 18 to 24 months of effectiveness in mind, and we stuck with it for more than 60 months since — as the economy remained weak. Now the strategy has become less effective.”

What Jos. A. Bank has really been doing since the financial crisis is running its own version of quantitative easing. The company had a temporary strategy that was supposed to get people into its stores during the recession — much like the Fed’s original QE, which was designed to provide liquidity in a time of crisis — but the recovery that ensued was not to Jos. A. Bank’s liking. So just as the Fed implemented QE2, and then QE3 when the economy did not improve to its satisfaction, the retailer followed with more QE.

It is understandable why Jos. A. Bank’s management did what it did. The company was being responsible to its employees — it didn’t want to close stores or have layoffs — and it had to report quarterly to shareholders. The focus shifted from building a long-term sustainable franchise to using short-term measures to grow earnings the next quarter and the quarter after that.

There are many lessons that one can draw from the parallels between Jos. A. Bank’s behavior and the Fed’s handling of our economy. First, it is very hard to challenge someone who has a linear argument. Let’s say that a year ago you talked to Jos. A. Bank’s management and raised the question of the sustainability of their advertising strategy. They’d have pointed to four years of success, and they’d have been right, at least up to that moment. They would have had four years of data points and a bulletproof linear argument, and you would have had your common sense and little else.

***
suit-869380__180

***

Ben Bernanke

Right now Ben Bernanke looks like a genius. He can show you all the data points in the recovery, but so could Jos. A. Bank, and this leads us to a second lesson: Pain is postponable, but it is cumulative. During Jos. A. Bank’s quarterly call, its CEO also said: “The decline in traffic is because existing customers are returning slightly less frequently. . . . It makes sense when you consider the saturating effect of our intense promotional activity over the past several years.”

With every sale Jos. A. Bank stole its future purchases, because when you buy one suit and get three for free, you may not need to buy another one for a while.But there is also a snowball effect that you cannot ignore: Every ad chipped away at the company’s brand. Now when you show someone that you wear a Jos. A. Bank suit, they don’t think about its quality, just that you have two or three more suits in your closet.

There is a cost to our recovery — a bloated Federal Reserve balance sheet and our addiction to low interest rates. Of course, we spread that addiction globally.

According to Hugh Hendry, founding partner and CIO of London-based hedge fund firm Eclectica Asset Management, rising U.S. bond yields have driven global yields higher. “In Brazil for instance, the biggest emerging debt market, no company has been able to raise debt abroad since mid-May as borrowing costs soared to a four-year high in June, at 7.1 percent,” he wrote in a recent investment letter.

The Fed is betting on George Soros’ theory of reflexivity, in which people’s biases and actions can change the economy: Instead of the wagon being towed by the horse, the wagon, in expectation that it will be towed by the horse, starts moving on its own, thereby motivating the horse to start towing the wagon.Lower interest rates drive people to riskier assets, and as asset values go up, people feel confident and spend money, and the economy grows. But this policy puts us on very shaky ground, because reflexivity cuts both ways: If asset prices start to decline, confidence declines — and so will the economy. Now there are a lot more savers owning riskier assets than they otherwise would have, and their wealth is at risk of getting wiped out.

The third lesson from the parallels between the Fed and Jos. A. Bank: We are in the midst of a game of musical chairs, and when the music stops, no one wants to be left standing around holding risky assets. Everyone is focused on the Fed’s tapering, and they are right to do so. Just as we saw with Jos. A. Bank, economic promotions cannot go on forever. With every sale the company had to increase the ante, giving away more and more to get people to come into its stores. The Fed may continue to buy Treasuries and mortgage securities, but the purchases will be less and less effective. And the music may stop on its own, without the Fed doing anything about it.

Last, pseudolinearity eventually leads to high uncertainty and thus lower valuations. Put yourself in the shoes of an investor analyzing Jos. A. Bank today. Before buying the stock, you’d have to answer the following questions: What is the company’s earnings power? How much did its promotional strategy damage the brand? And how much in future sales did that strategy steal?

Assessment

In the wake of Jos. A. Bank’s own five-year, nonstop version of QE, it is difficult to answer these questions with confidence. The company’s earnings power is uncertain, and investors will be willing to pay less for a dollar of uncertain earnings, thus resulting in a lower P/E. At some point, when U.S. economic activity weakens, investors will have to answer similar questions about the U.S. and global economies. And as they look for answers, they’ll be putting a lower P/E on U.S. stocks.

ABOUT

Vitaliy N. Katsenelson CFA is Chief Investment Officer at Investment Management Associates in Denver, Colo. He is the author of Active Value Investing (Wiley 2007) and The Little Book of Sideways Markets (Wiley, 2010).  His books were translated into eight languages.  Forbes Magazine called him “The new Benjamin Graham”.  

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[WHERE LEARNING IS A plus+]

Career Development, Products and Services

“The informed voice of a new generation of fiduciary advisors for healthcare”

CMP logo

http://www.CertifiedMedicalPlanner.org 

 Our New Text – “Take a Peek Inside – Now Available

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

                              logos

“BY DOCTORS – FOR DOCTORS – PEER REVIEWED – FIDUCIARY FOCUSED”

***

Got a Beef With Your EHR?

Join Our Mailing List

So – Go Tell the Feds; Already!

[Staff reporters]

Are you a doctor or medical provider unhappy with your electronic health records system, or unable to share health data because of the actions of other organizations?

Or, are you a healthcare consumer who can’t access your EHRs? The feds want to hear from you.

The Office of the National Coordinator for Health Information Technology has a new online complaint website, healthit.gov/healthitcomplaints. It is the first formal complaint process that ONC has had throughout the journey to EHR meaningful use.

***

Source: Joseph Goedert, Health Data Management [9/18/15]

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

[PRIVATE MEDICAL PRACTICE BUSINESS MANAGEMENT TEXTBOOK – 3rd.  Edition]

Product Details

  [Foreword Dr. Hashem MD PhD] *** [Foreword Dr. Silva MD MBA]

***

On Socially Responsible Investing

Join Our Mailing List

Balancing profits, people and the planet

Rick Kahler MS CFP

By Rick Kahler MS CFP®  http://www.KahlerFinancial.com

Balancing profits, people, and the planet can be tricky. Many physicians and other investors prefer to put their funds into companies that not only make money, but that also reflect the investors’ values. Some take this concept, often described as “socially conscious” or “socially responsible” investing, very seriously. There are also financial advisors who specialize in this niche.

Yet investing in companies whose values align with your own is not as simple as it may seem.

Business owners and corporate executives

In my experience with business owners and corporate executives, most of them take an interest in bettering the people who work with them, the planet, and their own lives. They run their companies with integrity. They don’t break the law. They respect their customers and don’t take advantage of them, but give them fair value in exchange for their money. They offer compensation and working conditions that will attract and retain good employees. Ultimately, they understand that ethical business practices are not only the right thing to do, but the best way to run profitable businesses.

But, how do you as an investor know whether a company is bettering  people and the planet while it is making a profit? One method is to choose companies in which to invest by using some type of socially responsible screening. Such screening looks to exclude companies producing products that harm people or the earth, or companies judged to have poor corporate cultures.

The challenges

One challenge with using such screens is that we don’t all have the same definitions of what may be socially or morally offensive. Investor A may not want to own stock in oil or mining companies. Investor B may be concerned about goods produced in unsafe working conditions. Investor C may not want to support companies that sell tobacco or alcohol.

A second challenge is that companies change. They may expand, diversify, or merge with other companies until it’s difficult to pinpoint their values, products, and company culture. A company may sell a lot of great products that do a lot of good for people, but have one division that produces a product some investors may find offensive. And it’s even harder to screen for companies that have good cultures—especially since there’s no clear definition of a “good” culture.

Choices

Investors can choose mutual funds that include only socially responsible companies, but any such fund is almost guaranteed to include companies that you would otherwise exclude.

If you are serious about investing only in companies that support your values, it’s essential to research them before you invest and monitor them regularly to ensure their practices or products don’t change. You also may find it necessary to give companies or SRI funds a little leeway—settling for perhaps 95% compliance with your values rather than insisting on 100%.

But sadly, even if you could invest your money in the shares of companies that totally support your values, doing so may not have much impact on that company, its people, or the planet. One reason for this is that your investment is likely to be a miniscule fraction of the company’s stock.

In addition, most often when we invest in stocks, we do not buy shares directly from the company. We buy shares, through a stock exchange, that are being sold by other investors. The profits or losses involved in trading those stocks accrue to the third-party buyers and sellers. They don’t directly affect the company’s bottom line.

***

gv

***

Assessment

For most small investors, making a difference through socially responsible investing may be an illusory goal. Its only real impact may be to help us feel better about ourselves.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[WHERE LEARNING IS A plus+]

Career Development, Products and Services

“The informed voice of a new generation of fiduciary advisors for healthcare”

CMP logo

http://www.CertifiedMedicalPlanner.org 

 Our New Text – “Take a Peek Inside – Now Available

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

Front Matter with Foreword by Jason Dyken MD MBA

logos

“BY DOCTORS – FOR DOCTORS – PEER REVIEWED – FIDUCIARY FOCUSED”

***

APHA – National Preparedness Month

Join Our Mailing List

AMERICAN PUBLIC HEALTH ASSOCIATION [APHA]

Prepare for Disasters with Get Ready’s 2016 Calendar

***

Ready, Pet, Go! Prepare for disasters with Get Ready’s 2016 calendar
Emergency preparedness tips brought to you by cute animals? The wild winners of Ready, Pet, Go!, APHA’s Get Ready Photo Contest, have got you covered.
 ***
To celebrate National Preparedness Month, APHA’s Get Ready campaign has released its 2016APHA's Ready, Pet, Go! Get Ready Calendar calendar featuring adorable animals and tips to keep you and your loved ones safe during disasters. Each month features a different animal sharing helpful safety advice, including protecting yourself from disease, where to take shelter during a storm and what to include in your emergency stockpile.
***
***
Check out the winning photos in our animal photo gallery and share them with your friends and family on Facebook and Twitter. And while you’re there, browse some of our favorite runners-up photos and vote for your favorite!
***
For more emergency preparedness resources you can use in your community or organization, visit the Get Ready website.
***

Get Ready logo   APHA logo

APHA’s Get Ready campaign helps Americans prepare themselves, their families and their communities for all disasters and hazards, including pandemic flu, infectious disease, natural disasters and other emergencies.

***

Product DetailsProduct Details

[Foreword Dr. Phillips MD JD MBA LLM] *** [Foreword Dr. Nash MD MBA FACP]

***

The Future of Doctors

Join Our Mailing List

The Future of Doctors

By Robert E.H. Khoo, M.D., F.R.C.S.(C), F.A.C.S.

http://www.colondoc.com

More:

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com
OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

[PRIVATE MEDICAL PRACTICE BUSINESS MANAGEMENT TEXTBOOK – 3rd.  Edition]

Product Details

  [Foreword Dr. Hashem MD PhD] *** [Foreword Dr. Silva MD MBA]

***

[HOSPITAL OPERATIONS, ORGANIZATIONAL BEHAVIOR AND FINANCIAL MANAGEMENT COMPANION TEXTBOOK SET]

Product DetailsProduct Details

[Foreword Dr. Phillips MD JD MBA LLM] *** [Foreword Dr. Nash MD MBA FACP]

***

About “Comments” on the Medical Executive-Post

Join Our Mailing List

One of Just Many Ways to Interact with Us

By Ann Miller RN MHA

[Executive-Director]

If you are not reading our subscriber “comments”, you are not getting all you can from each Medical Executive-Post. And, if you are not reading the links in each post, you are not getting all you can from the ME-P.

Industry Specificity

Then, purchase our textbooks, white-papers, handbooks, dictionaries and CDs for deeper integrated and peer-reviewed industry specificity.

Consulting Too!

And, we are now scheduling private consultations, events and corporate engagements, too. Online and on-ground seminars and private appointments are also available! But for now, read and learn from the comments  tab. It’s fast, free and secure!

Conclusion

So, there are several ways to interact with the ME-P, and more are scheduled in the future.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Product DetailsProduct DetailsProduct Details

Product Details

Product DetailsProduct Details

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***


Revelations on Consumer Driven Healthcare Plans

Join Our Mailing List

A 2015 Snapshot for HSAs

By http://www.MCOL.com

***

ImageProxy

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***

Career Development, Products and Services

“The informed voice of a new generation of fiduciary advisors for healthcare”

CMP logo

http://www.CertifiedMedicalPlanner.org 

 Our New Text – “Take a Peek Inside – Now Available

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners(TM)

logos

“BY DOCTORS – FOR DOCTORS – PEER REVIEWED – FIDUCIARY FOCUSED”

***