On Investing Risk Tolerance

Determining Risk Tolerance

By Rick Kahler CFP®

If you are new to investing, or if you aren’t sure how much risk you are taking in your current portfolio, it may be helpful to spend a little time to determine your risk tolerance.

A good place to start is by taking a few risk tolerance surveys. A variety of free assessments are available online; three examples are at Vanguard, Schwab, and Morningstar.

Examples:

I like surveys that express your risk in terms of downside volatility, or how much loss you could tolerate. Most will express the downside in terms of how far your portfolio would have to go down over a 12-month period before you would jump out.

Unless you only look at your portfolio once a year (which I highly recommend), you most likely won’t tend to think of a decline in your investments as being over a 12-month period. Because we all “anchor” on the highest value, it’s more typical to compare a portfolio’s peak value to its lowest point. You may want to ask yourself how far would the markets need to drop from their highs before you would want to get out “before it’s all gone.” It’s important to understand that the peak to trough drop will usually be much higher than the annual drop. For example, in 2008-2009 the peak to bottom drop in some portfolios was 40% when the 12-month drop was closer to 20%.

What is the right number for you?

So, as the Sleep Number bed commercials ask, what is the right number for you?

If your 12-month tolerance is a 15% drop, you will need to be in a very conservative portfolio, perhaps something like an allocation of 25% in equities and 75% in fixed income investments like bonds. If your tolerance is 25%, a 50/50 allocation may fit. For a tolerance of 35%, maybe a 75/25 allocation will be comfortable.

Don’t take these numbers as gospel. There are many, many variables that will determine what is right for you. I use these simply to give you a context that the less of a drop you can stomach in your portfolio before selling out, the lower your allocation needs to be to equities and the higher your allocation needs to be to fixed income.

If your answer to the question of how much risk you are taking in your investment portfolio is, “I have no clue,” now is the perfect time to get a clue. Why? We are in the ninth year of a bull market in stocks, the third longest in history. Also, 22 out of 23 of the last bear markets bottomed in the first two years of the Presidential cycle.

******

If you find yourself taking too much risk in your portfolio, lighten up on equities and increase your allocation to bonds. Lightening up doesn’t mean selling out of equities. It may mean shifting a 70/30 allocation to a 60/40 or a 50/50. Maybe it means adding some asset classes or investment strategies that do well when stocks drop. Sometimes a slight tweak can do a great deal to keep you in the market when the economy looks to be in a death spiral.

The time to do that tweaking is before the stock market crashes (goes into a bear market), not after. As the six months from September 2008 to February 2009 reminded us, bear markets develop very quickly.

Assessment

The important thing is to take action today to become aware of the risk that is in your portfolio and assess whether you need to make a change.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™


Take the Physician-Focused FINANCIAL PLAN “Challenge”

Do You Have “What it Takes”?

Book Marcinko

DEM 2

By Professor David E. Marcinko MBBS DPM MBA MEd CMP®

Institute of Medical Business Advisors, Inc.

mba

www.CertifiedMedicalPlanner.org

cmp-logo16

My History

More than 15 years ago I crafted a comprehensive holistic financial plan for a young doctor colleague who was born in 1959. In fact, he was not even a medical student at the time; so “canned off-the-shelf plans”, computer generated software or generic spread sheets were not a viable creation option. It was all a granular, detailed, specific and cognitive work-product. Today, he is a board-certified internist.

So, in 2017, it is right and just to take a look back and see how well, or poorly, we’ve fared.

Now, I appreciate more than most how financial planning is a “process”; and not an isolated event. Yet, all sorts of “advisors” and “consultants” create and charge hefty fees for same, and on-going monitoring, every day.

The ME-P Challenge

Nevertheless, I challenge all you mid-career or senior financial planners /advisors to this competition; regardless of degree, certification or designation.

“Show me your financial plan” – AND – “I’ll show you my financial plan”

Here Comes the Judge

Then, our community of ME-P readers, subscribers, visitors and “judges” will decide the winner.

The contest is open to any financial advisor, planner, consultant, wealth manager, CFP®, CFA, insurance agent, CPA or CLU, ChFC, or stock-broker, etc., who is not afraid of transparency in his or her work product and purported expertise.

Of Financial Certifications and Designations

*** [Creating and Evaluating a physician focused financial plan]
***

Assessment

So, just send in a copy of any “blinded” physician-focused financial plan that is about 15 years old. We will post for all to see and review …. warts and all … including my own; three part mega-plan!

The winner will receive bragging rights, academic swagger, and expert promotion to our entire ME-P ecosystem and network of medical, business, law and graduate school communities; as well as physicians, nurses, healthcare executives and allied health care professionals.

An informed sought-after and lucrative sector – indeed!

IOW: Free publicity and positive “new-wave” PR – PRICELESS!

Of course, as an educator and professor of health economics and finance, we are pleased to present you with the deep medical business knowledge and detailed financial,managerial and accounting techniques used, with some real-life “tips and pearls” developed over the last two decades of R&D, right here:

MORE: Comprehensive Financial Planning Strategies for Doctors[Best Practices from Leading Consultants and Certified Medical Planners™]

MORE: Risk Management Liability Insurance, and Asset Protection Strategies for Doctors and Advisors [Best Practices from Leading Consultants and Certified Medical Planners™]

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

***
Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™           8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

PART 1: My Sample Financial Plan I [Data gathering, goals and objectives]

PART 2: My Sample Financial Plan II [Data Analytics, Creation and Crafting]

PART 3: Request here: MarcinkoAdvisors@msn.com [Stress Testing and Completion]

***
← Back

Thank you for your response. ✨

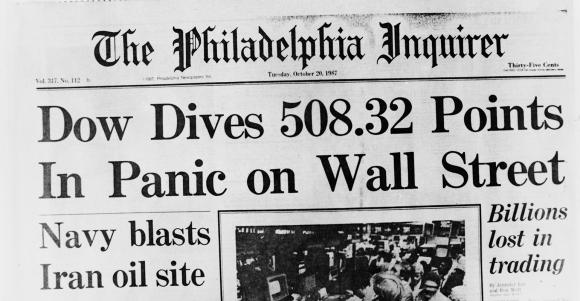
Remembering the Stock-Market “Crash” of 1987

It was 30 years ago … today!

***

https://en.wikipedia.org/wiki/Black_Monday_(1987)

***

Three reasons the next crash may be worse than 1987

http://www.marketwatch.com/story/three-reasons-the-next-crash-may-be-worse-than-1987s-2017-10-18

***

Thirty years ago this week, Wall Street slid into the abyss

https://www.msn.com/en-us/money/markets/thirty-years-ago-this-week-wall-street-slid-into-the-abyss/ar-AAtI5va?li=BBnbfcN

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

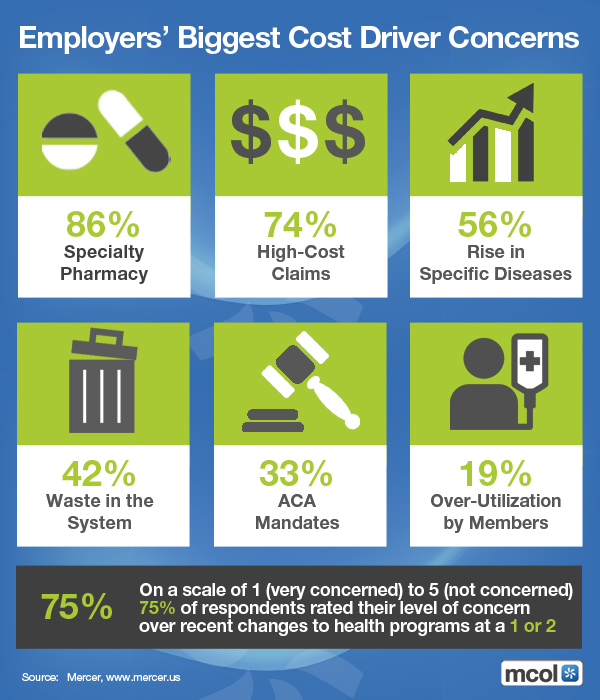
Employer’s Biggest Healthcare Cost Driver Concerns

Health Cost Driver Concerns

By http://www.MCOL.com

***

***
Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.lll


On Retirement Planning Risks

How Much Risk?

By Rick Kahler CFP®

If I asked you how much risk you are taking with the investments in your retirement plan, what would you say? My guess is nine out of ten people couldn’t answer that question in a meaningful way. Answers like “A lot,” “Just right,” or “not much,” may as well be “I have no clue.”

Risk tolerance

We typically think of risk levels in terms of “risk tolerance.” This is the appropriate portfolio risk that a person would be most comfortable taking with their investments. While investment advisors are required to assess your risk tolerance and you can measure it yourself on various internet sites, determining what risk you are comfortable with is more of an art than a science. It depends on the investment return you need to produce an acceptable retirement income and the asset allocation that will give you that return, and it is a delicate balance between emotions and financial reality.

When markets are rising, everyone is comfortable with their risk tolerance. I have known retirees who had their entire retirement portfolio in a handful of small company growth stocks—a powder keg of investment risk by any definition of risk.

Yet they were entirely comfortable with that risk, because the stocks they were in “always went up.” Anyone with a stock that “always goes up” either hasn’t held the stock during a bear market or only looks at their brokerage statements once every five years.

Uncomfortable!

To find out what comfort really means when it comes to risk tolerance, it helps to define “uncomfortable.” While risk tolerance tests will ask you how far must your portfolio drop before you freak out and sell, the best way to find this out is when markets are in a free fall.

If you stay in the markets long enough to see them turn around and rise again, your risk tolerance was probably comfortable. If you sell out, it’s a pretty good indication your risk tolerance was not as great as you or your advisor thought. Unfortunately, selling out at a market bottom is a very costly way to find out the risk you had in your portfolio was “uncomfortable.”

A decade 

If you have been investing for over 10 years, finding your risk tolerance may be simple.

1. Think back to 2008-2009. Did you stay in the markets or get out?
2. Look at old statements and find out what percentage of your investments was in equities (owning things) and what percentage was in fixed income investments (loaning money through CD’s, money markets, and bonds).
3. Express this as a fraction with your equity percentage first and your bond percentage last. If you were 66% in equities and 34% in fixed income your asset allocation was 66/34.
4. If you stayed in the markets, your allocation was probably “comfortable.” If you got out, it was certainly “uncomfortable.”

***

***
If your allocation was 70/30 and you stayed in the market, maintaining that allocation should serve you well. Maybe you could even increase the equity portion to 75/25 or 80/20 and still be comfortable.

Conversely, if your allocation was 70/30 and you sold out or reduced the percentage you held in equities, your allocation clearly offered an uncomfortably high level of risk. You will need to reduce the equities in your portfolio. This is especially true if you got back into your old allocation, or something even riskier, to “make up time.” You may well be taking too much risk and setting yourself up for failure all over again. You will need to reassess

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.

***

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

Wi-Fi security is wide open to hackers

A flaw in the WPA2 protocol

[By MIT Technology Review]

Researchers have discovered a serious flaw in the WPA2 protocol that secures almost every modern Wi-Fi network. The vulnerability could allow hackers to inject malware into websites, or spy on people by reading information that was previously assumed to be encrypted.

The researchers say that “any correct implementation of WPA2 is likely affected,” with Android, Apple, and Windows software all said to be vulnerable. Security updates should fix the issue—when they’re ready to install.

***
https://www.krackattacks.com/?utm_source=MIT+Technology+Review&utm_campaign=6d93d8c040-The_Download&utm_medium=email&utm_term=0_997ed6f472-6d93d8c040-154253973

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

***

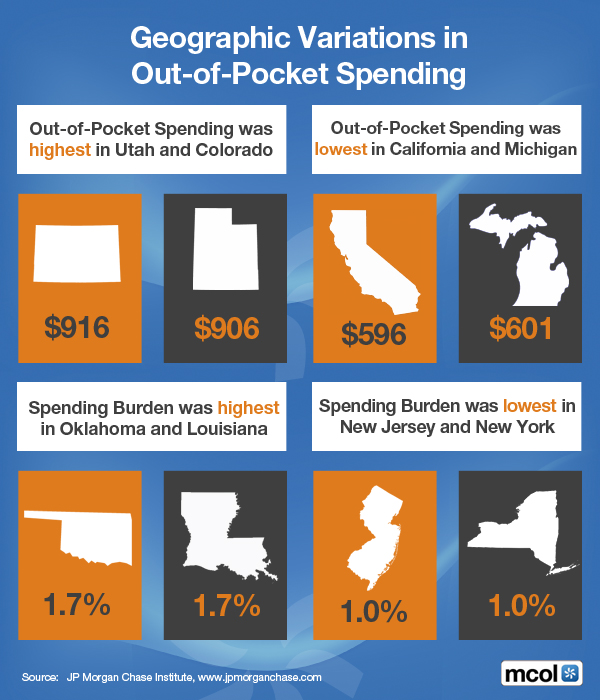
Geographic Variations in Out-of-Pocket Spending

In Healthcare

By http://www.MCOL.com

***

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.

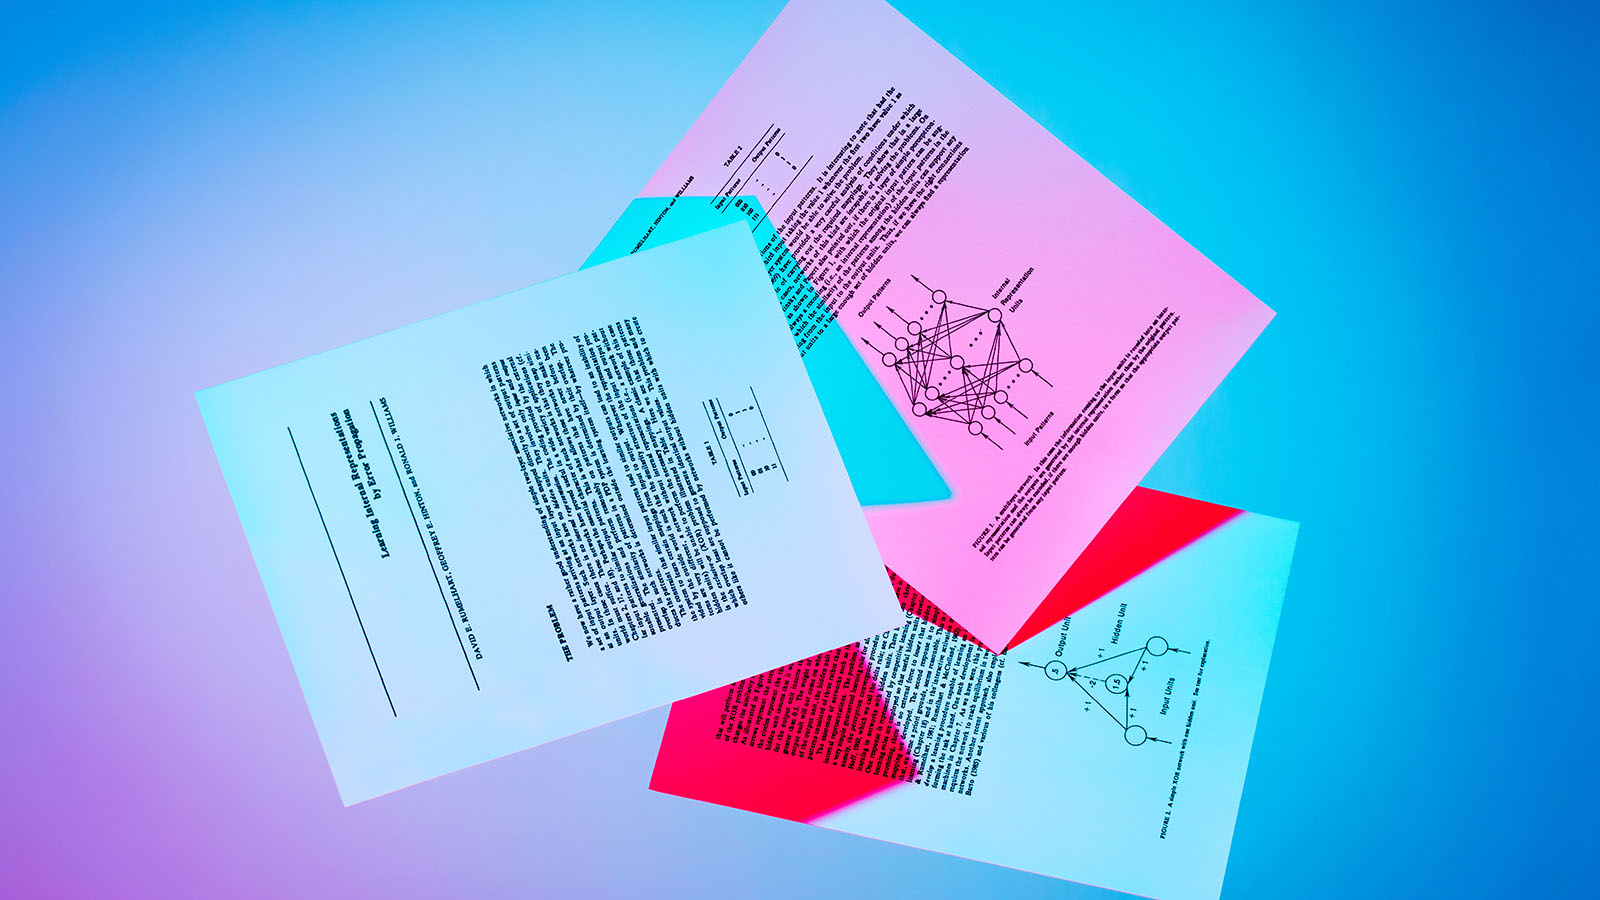
It’s time to put humans at the center of A.I.

More on Artificial Intelligence
By MIT Technology Rerview

“To make more helpful and useful machines, we’ve got to bring back the contextual understanding,” says Fei-Fei Li, chief scientist of Google Cloud, in an interview with MIT Technology Review.

***

***

Read why she wants to inject some humanity into AI

https://www.technologyreview.com/s/609060/put-humans-at-the-center-of-ai/?utm_source=MIT+Technology+Review&utm_campaign=f21f8e4086-The_Download&utm_medium=email&utm_term=0_997ed6f472-f21f8e4086-154253973

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.

Is money more instinctual than cognitive?

On Financial Therapy

By Rick Kahler MS CFP®

My research in psychology, along with 35 years of experience working with people and their finances, suggests that how we handle money is more instinctual than cognitive.

It’s more a factor of our brains’ hard-wiring than it is learned intelligence. Apparently, some people are just wired to do money well and others are not.

This can sound like a complete copout. The idea that you either have the money gene or you don’t seems simplistic. Yet I believe there is some truth to it.

R&D

Researcher and educator Russ Hudson finds that two centuries of data suggest every human being has three basic instincts that are necessary for survival: social (for getting along with others), sexual (for extending ourselves through generations), and self-preservation (for maintaining our physical life and functioning).

For most of us, these three are not equally balanced. One tends to be dominant, a second supports the dominant one, and the third and weakest one typically creates a blind spot. The dominant and weakest instincts give us the most trouble.

Evidence supports the idea that those with a dominant instinct of self-preservation tend to instinctually be successful savers. They are the people who find it relatively easy to, in the words of the late Dick Wagner, “Spend less, save more, and don’t do anything stupid.”

This doesn’t mean they have a good relationship with money; that they sleep peacefully at night, don’t worry about money, or are not obsessed with money. It doesn’t mean they are happy. But it does mean they tend to be frugal, which is the common denominator of accumulating wealth. They understand instinctually that you can’t spend more than you receive if you are going to thrive and prosper financially. Living life on the edge or focusing on the welfare of others is instinctually foreign to them.

******

On the other hand

Someone with a dominant social or sexual instinct may be living hand to mouth, but be blissfully happy doing so. What’s instinctually foreign to them is learning to manage money prudently and take care of themselves financially.

As Jonathan Clements recently wrote in his HumbleDollar blog, “Why is change so difficult? Improving behavior is toughest when it means bucking our hardwired instincts. Intellectually, we may know we should exercise more, lose weight and save more—and yet our instincts keep telling us to stay on the couch, eat Cheez Doodles and shop online.” That’s why more financial education or discipline isn’t enough to motivate most Americans toward finding financial wellness.

For those who don’t have self-preservation as the dominant instinct, the enormity of learning to practice more self-preserving financial habits can feel depressing and hopeless. Yet it is certainly possible. It just isn’t going to be easy.

Idea

One approach that may be helpful is to get assistance and support from others. Clements says he has come to believe the best thing to do is tell friends about your financial goals like saving money for a down payment on a home, paying off a debt, or increasing your retirement plan contributions. This can help motivate you to commit to following through.

Announcing an intention to friends with the hope that the shame of not following through will motivate you to create a new behavior may work for a few. Yet for most, it probably won’t help to change a hard-wired instinct.

Assessment

A better idea might be finding and reporting  to an accountability partner who would kindly, without scolding or shaming, help motivate you to establish a habit.

Even better may be engaging a financial therapist to help you with the hard work of cultivating new instinctual behaviors.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.

***
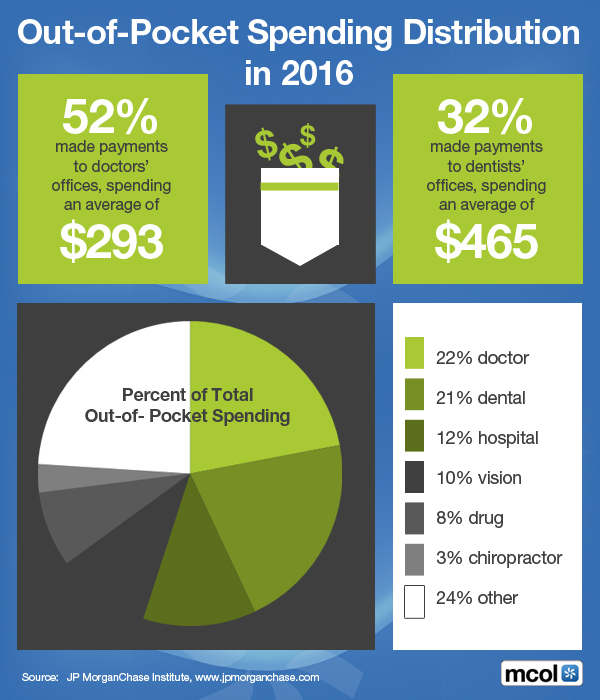
Out-of-Pocket Medical Spending Distribution

In 2016

By http://www.MCOL.com

***

***
Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.

Should Algorithms and Robots Mimic Empathy?

Should Algorithms and Robots Mimic Empathy?

By Bertalan Meskó MD PhD

Robots telling jokes and chatbots acting as life coaches sound astounding and terrifying at the same time. Extensive research is going on lately in the field of applying human features, emotions, gestures, and reactions to digital technology; and it raises thousands of questions.

Three Questions:

  • Could not only smart, but emotional algorithms or robots appear also in healthcare soon?
  • Would there be a place or need for them?
  • How would it impact the patient-doctor relationship or social interactions in general?

http://medicalfuturist.com/algorithms-robots-mimic-empathy/?utm_source=The+Medical+Futurist+Newsletter&utm_campaign=2da4036681-Newsletter_2014_07_177_17_2014&utm_medium=email&utm_term=0_efd6a3cd08-2da4036681-399696053

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.

***

On Consumer DNA Testing

Two states still resist consumer DNA testing

[By MIT Technology Review]

Earlier this month, 55,000 football fans were to receive a giveaway at a Baltimore Ravens game: not a T-shirt or a beer koozie, but a free DNA test. Ultimately, though, Maryland laws nixed the stunt.

Ronni Sandroff explains why.

***
https://www.consumerreports.org/cro/news/2010/09/who-owns-your-dna/index.htm

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

Subscribe: MEDICAL EXECUTIVE POST for curated news, essays, opinions and analysis from the public health, economics, finance, marketing, I.T, business and policy management ecosystem.

***
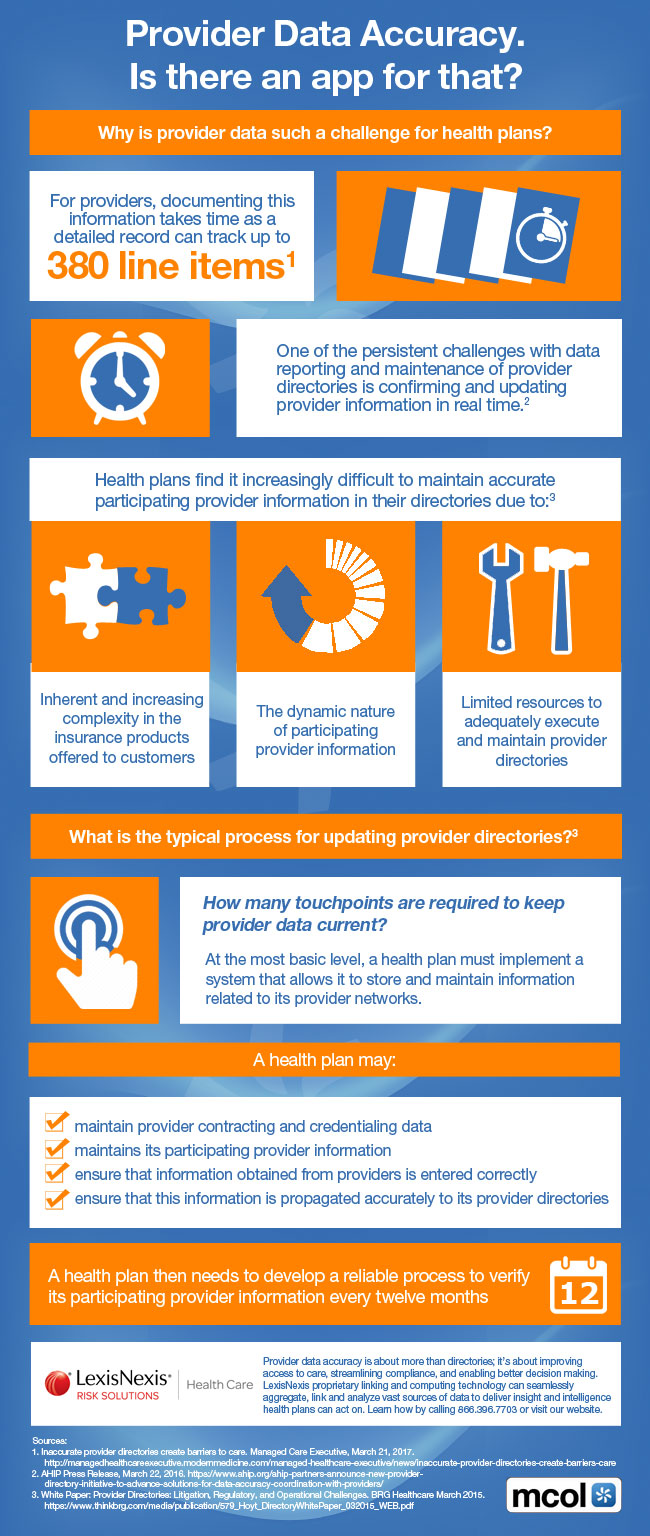
On Medical Data Provider Accuracy

Is there an app for that?

http://www.MCOL.com

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

***
When a Drug Coupon Helps You but Hurts Others

When a Drug Coupon Helps You but Hurts Others

***

When a Drug Coupon Helps You but Hurts Others

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

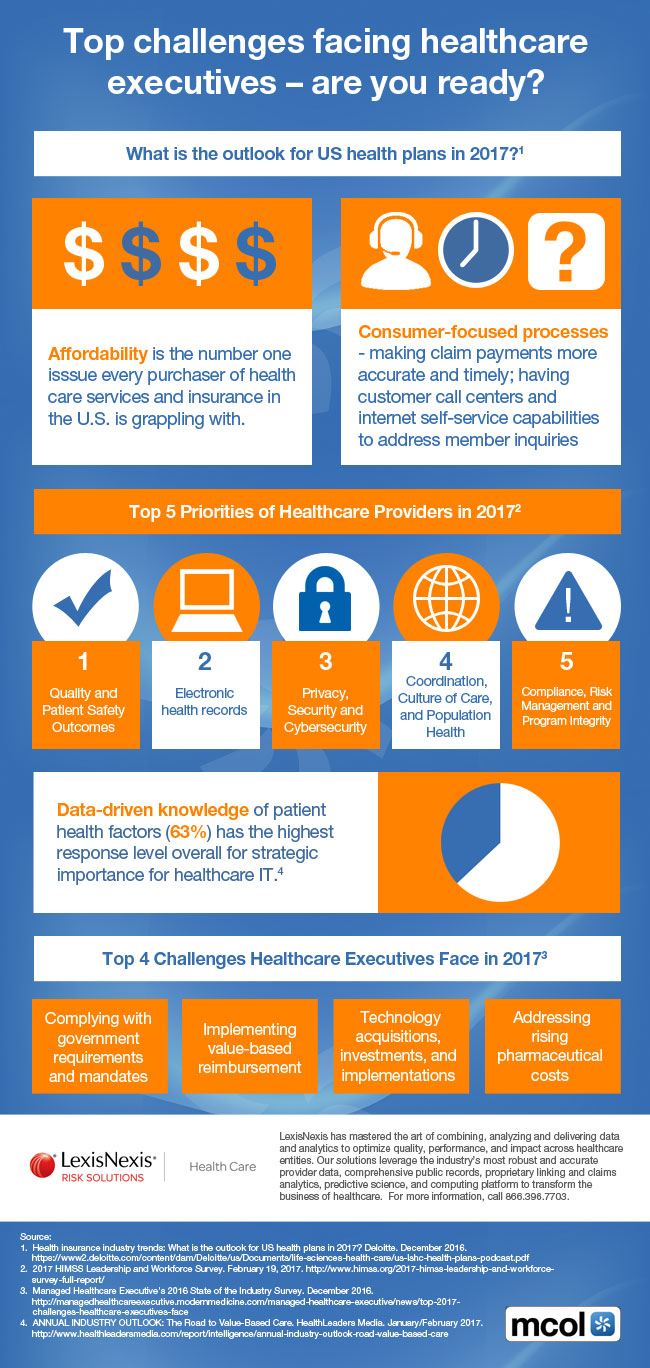
Top Challenges Facing Healthcare Executives Today

Join Our Mailing List 

Are you ready in 2017?

http://www.MCOL.com

***
***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***
Can blockchains set the Web free?

Join Our Mailing List

Really!

By MIT Technology News

Growing numbers of technologists want to reinvent the Web, to counter dominance of firms like Facebook and Google. They say the tech inside digital currencies could transform the way we share data.

Our own Mike Orcutt wonders if they’re right


 ***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

When You are Not a Financial Numbers Cruncher?

“When I see big numbers in an article, my brain just skips over them”

By Rick Kahler MS CFP®

If you are not a natural number cruncher, you may be like one of my clients who says, “When I see big numbers in an article, my brain just skips over them.” Unfortunately, skipping over numbers can lead to serious misunderstandings.

Here are three questions to ask that can help you clarify those big numbers:

1. What’s the time period? The reported cost or savings of something is completely irrelevant unless you know the length of time over which it is calculated.

For example, the August 11 Wall Street Journal included this headline: “U.S. Is Overhauling Its Nuclear Arsenal.” A secondary headline below read, “A $1 trillion revamp begun under Obama is under way as tensions rise with North Korea.”

It would be reasonable to assume this means an up-front cost of $1 trillion, which might strike you as outrageous, especially if you know the total U.S. annual budget is around $4 trillion. Yet reading the article would make clear that the $1 trillion price tag is over 30 years. This breaks down to an expense of $33 billion a year, roughly six percent of the $550 billion annual defense budget. A headline reading, “6% of annual defense budget to be spent modernizing the nuclear arsenal,” is less likely to make the hairs on your neck stand up in horror.

It’s no different than my saying I plan to spend $100,000 fixing up my house, which has a market value of $200,000. If you assume I’ll spend this immediately, it sounds shocking. But over 30 years it comes to $3,330 a year, which is a reasonable amount to spend on annual maintenance.

This tactic of lumping together multiple year’s expenditures is frequently employed when someone wants to make an expense or a savings seem far larger than it really is.

2. Does the number include interest? If I said the average home in Rapid City, SD, cost $648,679, local residents who know the average home price is around $200,000 might call me a liar. Yet the cost of mortgage interest over 30 years on that $200,000 house brings the total to $648,679. This larger number might seem deceptive, because our society refers to the cost of something based on today’s cash price, not in terms of the total initial cost plus interest.

3. Did you read the whole article carefully? If you speed read and miss the minutia, numbers can be misleading. In recent weeks, the Rapid City Journal has published several articles on the controversial issue of remodeling or replacing the city’s civic center. A July 9th article cited the cost of a new civic center as $182 million; on the second page the cost of a previous proposal for a civic center that was defeated in a public vote was listed as $180 million. A quick read would make it appear the new proposal would cost $2 million more than the previous proposal.

A closer read would show that the $182 million for the new center included interest over 30 years, while the $180 million number for the former included no interest. With interest, the cost of the previous proposal would have been $340 million to $420 million, numbers which did appear elsewhere in the article. If we compare actual cost without interest, the estimated cost of the new proposal is around $100 million to $130 million, which is $50 million to $80 million less than the $180 million cost of the previous proposal.

Assessment

You don’t have to be a “numbers person” to understand big numbers in media reports. You just need (with the help of a calculator, if necessary) to read carefully.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

***
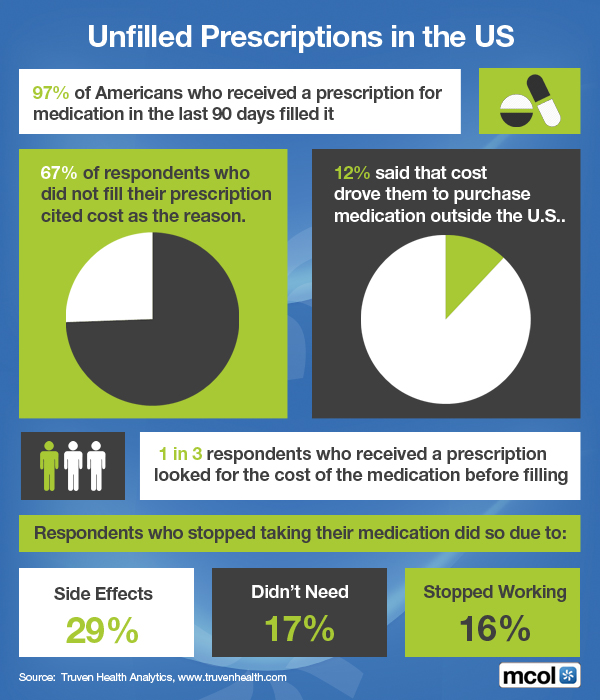
On Unfilled RXs in the USA

Respondents Poll

By http://www.MCOL.com

***
***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

***
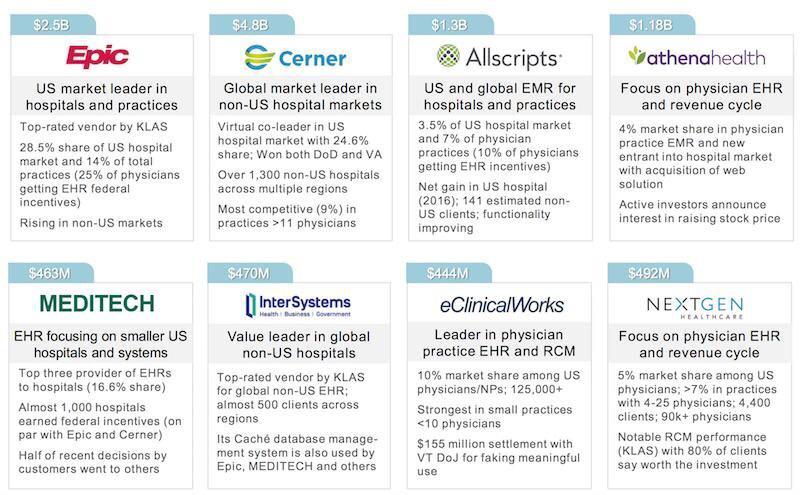
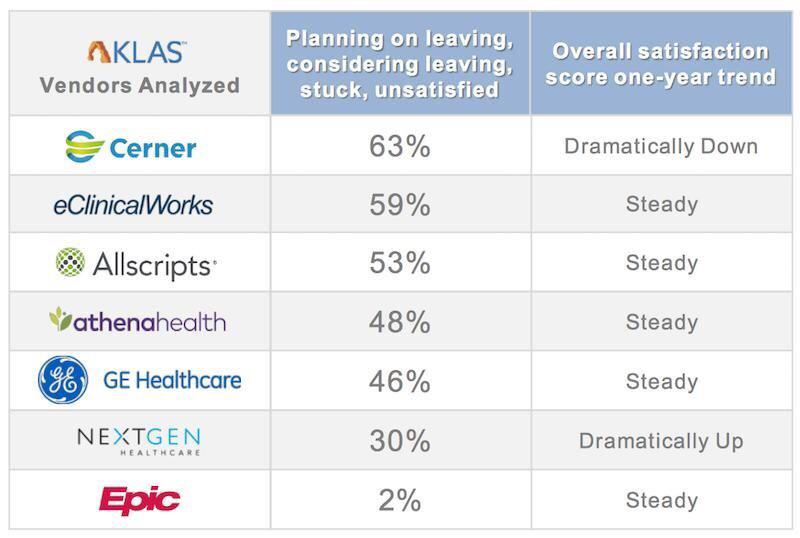
Update on EHR Rankings

Top Vendors

By http://www.MCOL.com and KLAS

******

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements.

Contact: MarcinkoAdvisors@msn.com

***

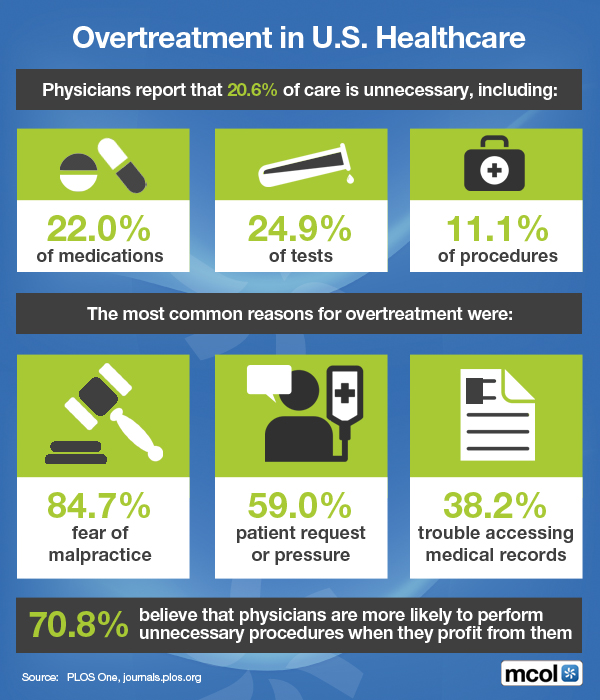
On Overtreatment in US Healthcare

Twenty Percent may be Unnecessary?

By http://www.MCOL.com

***
***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***

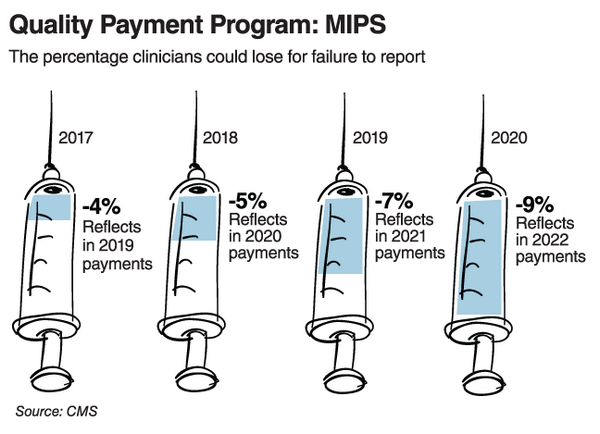
A MIPS: Quality Payment Program Report

Percentage Clinicians Might Lose for Failure to Report

By CMS

***

***
Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***

The EQUIFAX hack; and me!

About the  massive computer hack

By Rick Kahler MS CFP®

The massive computer hack of Equifax, one of the three largest US credit reporting agencies, exposed the Social Security numbers, names, and contact information for up to 143 million of us.

How should you respond?

A lot of conflicting advice is floating around; here is what I am doing and what I would recommend:

  1. Go to EquifaxSecurity2017.com and enter your last name and the last six digits of your Social Security number to find out whether you are one of those potentially affected by the breach. There is a question on how accurate this is; one person entered their name as “test” and number as 123456, and was told they were affected by the breach.
  2. Consider (also through EquifaxSecurity2017.com) enrolling in Equifax’s free one-year credit monitoring service. Starting this process put me on a waiting list to actually sign up; I have until November 7 to complete the enrollment. I will wait to sign up until more is known. The fine print of that offer initially appeared to require waiving your right to join a class action lawsuit against the company. The website now reads: “In response to consumer inquiries, we have made it clear that the arbitration clause and class action waiver included in the Equifax and TrustedID Premier terms of use does not apply to this cybersecurity incident.”
  3. Monitor your bank accounts, credit card statements, and other financial information carefully for the next year. Immediately report any suspicious transactions.
  4. Do not rush out and buy identity theft insurance. The big winners out of this mess will be insurance companies that sell this protection, as millions will take out new policies. I do not plan to be one of them, as my opinion that identity theft insurance is of limited value has not changed.
  5. If a check of your Social Security number through Equifax’s website shows your information has potentially been compromised, you could consider canceling credit cards or closing bank accounts that may not protect you against fraud. However, most major credit cards and financial institutions will cover successful fraudulent attempts to use your account.
  6. Consider placing a free fraud alert on your account with the three major credit bureaus to warn creditors to verify your identity before issuing credit in your name. If you contact one agency, it is required to notify the others. You can also put a freeze on your credit, which blocks anyone (including you) from accessing your credit reports without your permission.
  7. Unfortunately, one of the best actions to take is one that none of us can easily do: change our Social Security numbers. It is possible to change one as a result of identity theft, but the application process requires evidence of serious ongoing problems.
  8. Consider contacting your Senators and Representatives to raise the issue of whether it’s time to discuss more flexibility around Social Security numbers. The good news is that elected officials may well be among the millions of us in this boat.

While Equifax has handled this debacle poorly (it took them a month to disclose it), they are not the only company that will suffer serious consequences. I see banks and credit card companies, who ultimately pay the tab for identity theft, as the biggest losers.

Assessment

This data breach potentially involves many people who have followed recommended strategies, such as using strong online passwords and guarding credit cards and account numbers, to protect against identity theft. I recommend following the Equifax story as it unfolds in the media, as it may have an impact on how you should safeguard your data in the future. 

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***


Non-Profit CEO Compensation Update

Percentage contribution amounts

By Snopes 

NOTE: Not independently verified by us. Continue reading

Dental EHRs are Coming to an End?

Dental EHRs are Coming to an End

By Darrell Pruitt DDS


The reckless third-party push for adoption of increasingly dangerous dental EHR systems is the most harmful scam in the history of dentistry.

But it’s almost over, Doc. Equifax was hacked.

“If a company like Equifax can make significant investments, have every incentive to keep the most sensitive kind of information secure, but still experience a breach … it stands to reason that our playbook needs a revision,”

Josh Mayfield: [Platform Specialist at Firemon Immediate Insight]. (See: “Equifax, U.S. consumers alike will struggle to overcome massive hack” By Tim Johnson for Mcclatchy, September 8, 2017).

Http://www.mcclatchydc.com/news/nation-world/national/national-security/article172078982.html

Why should anyone assume electronic dental records are any more secure than Equifax records?

Not only do digital health records subject Americans to increasing risk of medical identity theft – which can be lethal – but they are increasingly more expensive than paper dental records.

What’s more, electronic dental records offer dental patients NO TANGIBLE BENEFITS:  When is the last time you witnessed a practice advertise the benefits of digital records? On the other hand, you may have also noticed the appearance of paper files in the backgrounds of promotional photos.

A decade ago, I tried to persuade American Dental Association leadership to consider de-identification of dentists’ primary dental records. After all, if identities are unavailable, they simply cannot be stolen. ADA leadership summarily discarded the idea in favor of full disk encryption – which dentists summarily rejected in favor of luck …. And so here we are, Doc. “First, do no harm.”

***
***

Dental EHR vendors simply will not survive transparency without fundamental changes in how patients’ welfare is guarded – which will further increase their cost and liability.

The future is obvious, yet I am the only dentist in the nation openly warning of the inevitable collapse of the electronic dental record industry. Unlike physicians, who treat four to five times as many patients a day and depend on quick interoperability with other physicians, dentists can safely return to paper. They won’t like the inconvenience of carbon paper, but following the Equifax breach of almost half of the nation’s consumers – virtually every one of them mad as hell – dentists will have no choice. Ehrs have become too costly.

Assessment

This week, a dentist on Facebook who tried but failed to defend the censorship habits of a popular dental consultant said I was on a “one-man crusade.” I don’t think he meant it in the good way. I ask you to remember that remark for future reference.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

 Product DetailsProduct Details

***
 

What the heck is an Initial Coin Offering anyway?

 Wither the I.C.O.

By MIT Technology Review

bitcoin

You may have heard a buzz surrounding the new fundraising tool known as an ICO, which is how many new blockchain startups are raising cash.

But for those of you who are too embarrassed to ask, let us tell you what they’re all about.

 Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***
 

Bitcoins for Retirement?

 In a Balanced Portfolio?

By Rick Kahler CFP®

A reader recently sent me the following email: “As you know, there are ‘market experts’ pitching bitcoins as an ‘investment’. Has a Huge YTD gain. I’d bet a lot of your readers would like to know if a bitcoin position has a place in a balanced financial portfolio.”

I always appreciate hearing from readers, especially when they challenge me with topics I would normally not have considered. Bitcoins are not something to which I’ve paid serious attention.

How they Work

First, let me explain that a Bitcoin is a type of digital currency which is traded person to person. It is not backed by a government or considered legal tender. While Bitcoin is one of the earliest and most widely known digital currency systems, it is not the only one that is available. These are sometimes called “altcoin,” “virtual currency,” or crypto-currency.”

Unlike government-created currencies where a central bank controls the creation of the currency, Bitcoins are uncontrolled or tracked by any government. This allows people to send or receive money across borders freely, with none of the restrictions, tracking, or caps that are normally placed on transactions by governments.

A digital money system has an inherent problem common to all money systems. How do you keep the currency, especially one that is entirely digital, from being counterfeited? What stops someone from creating Bitcoins or selling the same Bitcoin multiple times?

The solution is a type of open source, public ledger that tracks every Bitcoin transaction from the beginning of Bitcoin time. It makes it virtually impossible to cheat. The creation of new Bitcoins is controlled via a process called mining. Only a limited number of new Bitcoins are allowed into the system annually, similar to how the precious metal supply gradually expands annually based on the mining of new metal.

The market in trading Bitcoins is probably as “free” as a currency market can get. The price of Bitcoins is based on supply and demand. Since Bitcoin was only created in 2009, it has less than a decade of performance to evaluate, but throughout its short history the price has fluctuated wildly. For example, it reached $31 in July of 2011, then dropped back to $2 by that December. In November of 2013 it hit a high of $1,242. The following month, the price dropped to $600, rebounded, crashed, and eventually stabilized to a range of $650 to $800.

The reader who asked me about Bitcoin was certainly right about its impressive 2017 year-to-date performance. On January 1, 2017, a Bitcoin sold for $496.90. As of August 19 it closed at $4,109.10, nearly a ten-fold increase in just eight months.

***
***

Operating History

An article on Investopedia offers a good overview of Bitcoin‘s operation and history.

It also describes some of the risks to evaluate before considering it as an investment. These include the relative novelty and lack of track record of digital currency, the possibilities for hacking and fraud, the uncertainties of future regulation, and the competition of other developing virtual currency systems. It also points out that Bitcoin transactions are similar to dealing with cash. They are “permanent and irreversible,” with “no third party or a payment processor, as in the case of a debit or credit card – hence, no source of protection or appeal if there is a problem.”

Assessment

While I like the libertarian freedom of the idea of a currency uncontrolled by government intervention, I don’t consider owning such a currency an investment. I do consider buying or selling digital currencies like Bitcoin a speculation. Like other speculative investments, these do not belong in any retirement portfolio. 

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

On Social Determinants Of Heath [SDOH]

Eight Data Sources from the CDC

Join Our Mailing List

1. Chronic Disease Indicators – https://www.cdc.gov/cdi/index.html
2. Community Health Status Indicators (CHSI 2015) –http://wwwn.cdc.gov/CommunityHealth/
3. Health Indicators Warehouse – http://www.healthindicators.gov/
4. Interactive Atlas of Heart Disease and Stroke – http://nccd.cdc.gov/dhdspatlas/
5. National Center for HIV/AIDS, Viral Hepatitis, STD, & TB Prevention Atlas – https://www.cdc.gov/nchhstp/atlas/index.htm
6. National Environmental Public Health Tracking Network – http://ephtracking.cdc.gov/showHome.action
7. The Social Vulnerability Index – http://svi.cdc.gov/
8. Vulnerable Populations Footprint Tool – http://www.communitycommons.org/chna/

MORE: https://www.goinvo.com/vision/determinants-of-health/

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct DetailsProduct Details

***
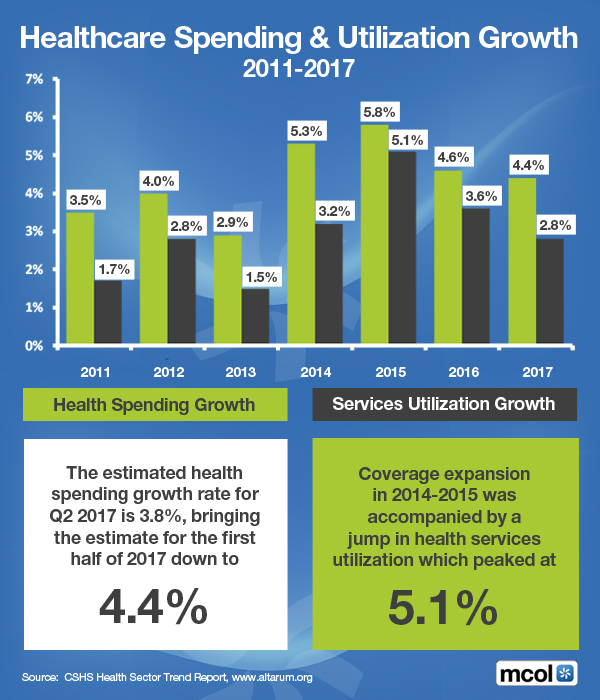
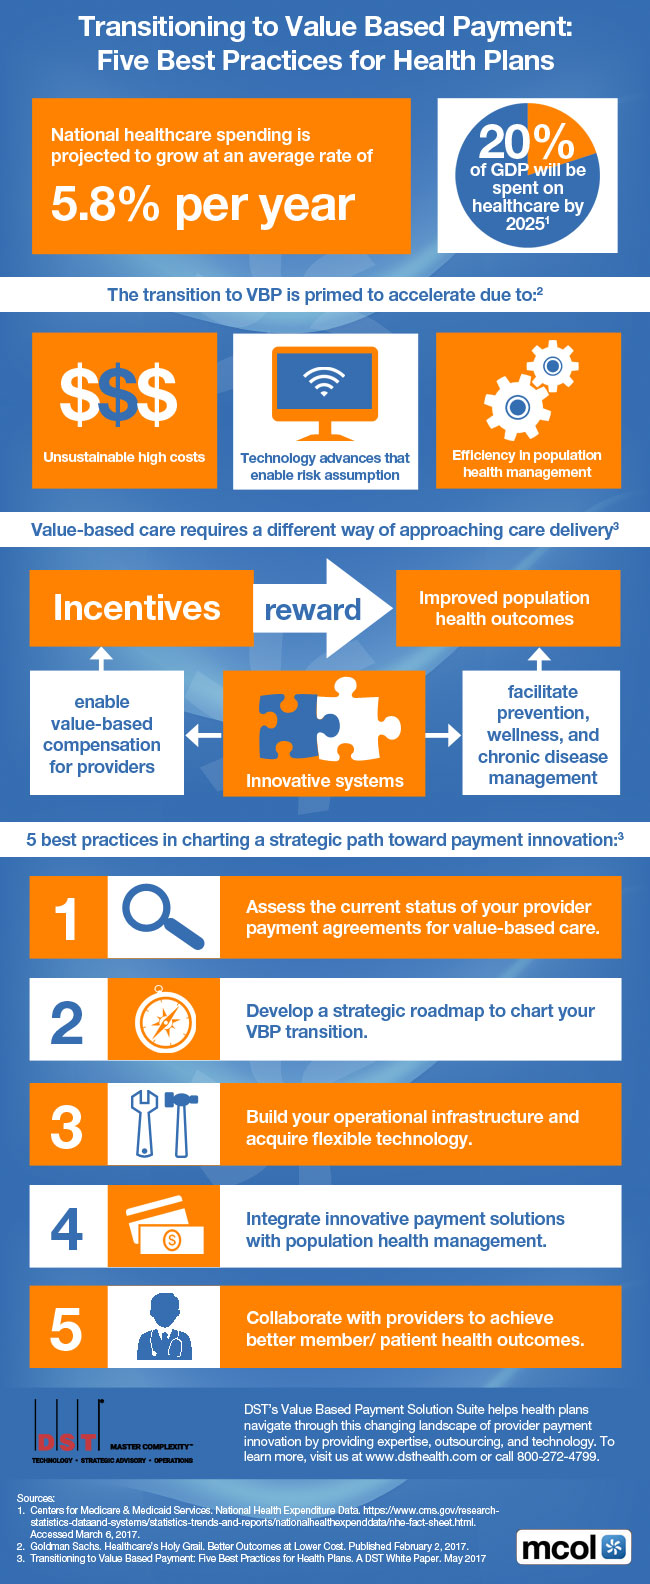
Healthcare Spending and Utilization Growth

Circa 2011-2017

http://www.MCOL.com

***

***
Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***

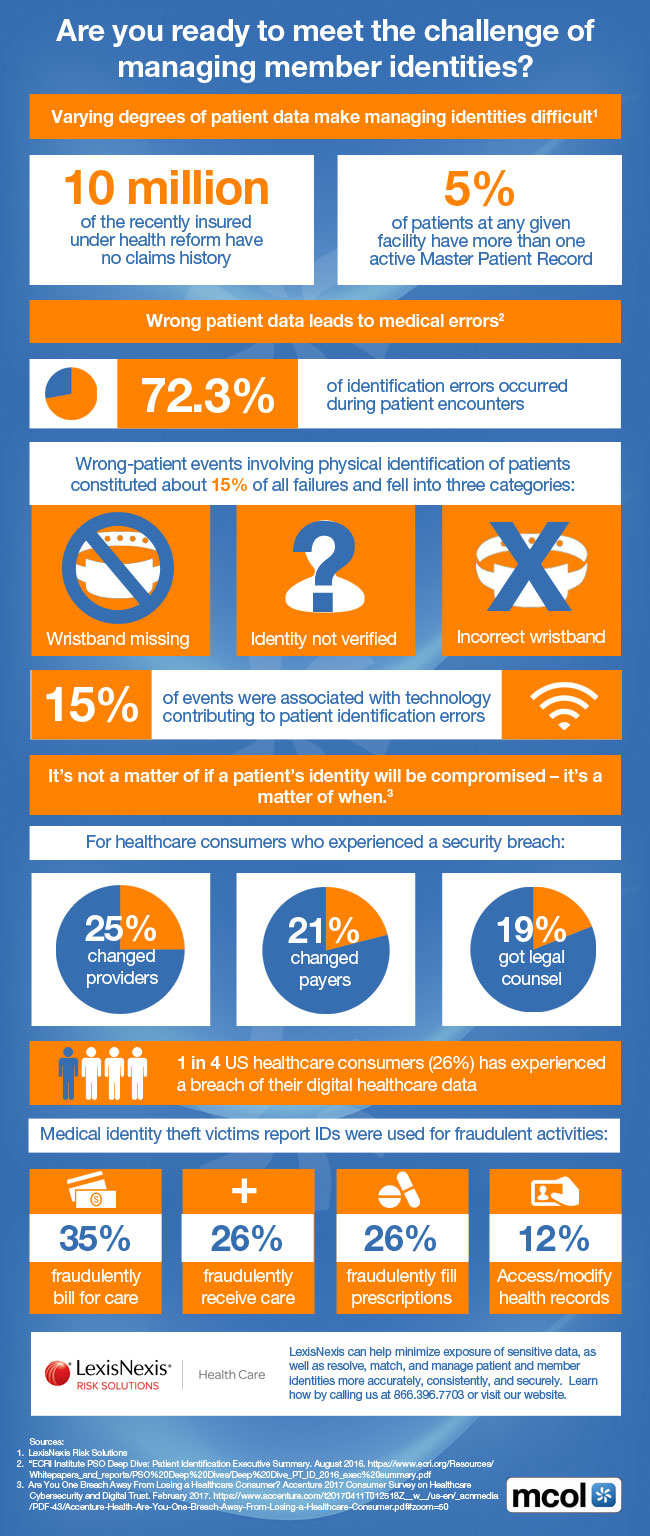
Are you ready to secure patient data?

Join Our Mailing List

The Challenge of Managing Member Identities

By http://www.MCOL.com

***

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

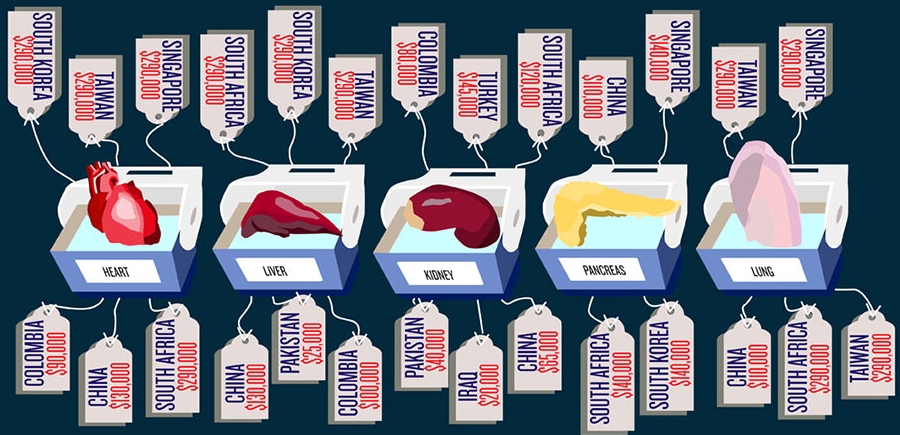
On Organ Harvesting

The Financial and Human Side

By staff reporters

NOTE: We recently received this anonymous message and post it for your critical analysis. No proof or disproof of authenticity is offered. It has been checked for viruses and other malicious miscreants.

Dear ME-P Friends,

Sorry for disturbing you, but we really need your support. We have put up a petition on our website infouncensoredchina.net It’s against the forcible removal of organs from innocent practitioners of Falun Gong in China. Please sign this plea. We need your voice to stop these crimes against humankind.

Feeding your family by selling a kidney?

We have read and heard about poor people in cities and country sides who, in order to pay off family debts are taken advantage of by illegal agents.

In one of the readers’ correspondence columns in the International Herald Tribune, a man in Chennai offered to sell his kidney in order to feed his family. That man was driven by the needs of life. He was jobless, and his wife and three kids were hungry.

This case touched the hearts of a lot of people such that, in the end, he did not have to sell his kidney, because a wealthy individual helped him by offering him some money and an employment.

In other situations, a kidney “sale” may occur for mutual benefit. The effort to save a person with kidney failure becomes the focus, not the process of selling the organ. The situations in these two cases conjure a strong sense of compassion and support. This is completely different from the anomaly to which Falun Gong practitioners in China are subjected. A cruel form of killing people for their organs is taking place on a huge scale in China, a circumstance far from humanity.

Before the Chinese government cracked down on the peaceful meditation practice on July 20, 1999, at least 70 million people were practicing Falun Gong around the country. Falun Dafa followers who live by the principles of truthfulness, kindness and forbearance, were victimized by former president Jiang Zemin, who could not accept the growing popularity of the practice. Since Jiang banned Falun Dafa over 16 years ago, practitioners have been systematically imprisoned tortured, and killed for their organs.

***

***

Assessment

There is substantial evidence stating that Chinese transplantation centers, as well as the police departments, military, and judicial systems, are making large monetary profits by taking the lives of healthy, innocent people, namely Falun Gong practitioners and other prisoners of conscience.

More information about these crimes can be found on the website.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Join Our Mailing List 


On the Department of Labor “Fiduciary Rule”

Join Our Mailing List

Rick Kahler MS CFP

By Rick Kahler MSFS CFP®

Both fee-only financial planning firms and companies that sell financial products are beginning to see some unintended consequences from the recent Department of Labor fiduciary rule.

The rule requires that all financial advisors who deal with an investor’s retirement accounts, including those who sell products, be held to a fiduciary standard. In the past, only RIA’s who are regulated by the SEC were held to such a standard.

The DoL intended the rule to discourage financial salespeople from placing high fee and commission products in retirement accounts. For fee-only advisers, one unintended consequence is an increase in documentation and paperwork, which increases the cost of doing business.

Another unintended consequence that could actually end up hurting consumers may be on the issue of churning.

Churning

Churning describes a broker excessively and needlessly making a lot of trades in a client’s account to generate extra commissions. FINRA, the agency that oversees the sale of financial products, has long discouraged churning, though often the practice only comes to light when a consumer files a complaint.

Still, regulators’ success in discouraging churning has given rise to fee-based brokerage and wrap accounts. These accounts do not compensate brokers on the number and frequency of transactions, but on an ongoing management or advisory fee. It can be a flat fee or one that is determined by a percentage of the assets in the account. This mode of compensation takes away a broker’s incentive to churn accounts. That has to be a good thing, right? Well, not necessarily, if you are a regulator.

***

dol

***

Now, according to financial planner and writer Michael Kitces, the regulators are concerned they have been “too successful” in motivating brokers to charge management fees. Kitces notes the new DoL fiduciary rule will continue to spur a massive shift towards various forms of fee-based brokerage and advisory accounts, giving rise to an emerging new problem: reverse churning.

Reverse Churning

He says reverse churning “is where an advisor charges an ongoing investment management fee … but fails to provide any substantive ongoing investment services.” The broker places a consumer in an investment, collects the annual fee, and never touches the account again. Regulators are worried that brokers have gone from too much activity (churning) to not enough (reverse churning).

With the rise in popularity of passive investing, there is growing interest in the use of ETFs, index funds, and other passive investment vehicles. Passive investing is often framed as a “leave it and forget it” strategy that needs little attention. A lot of research validates that a passive investment strategy is usually superior to an active strategy with more buying and selling of securities.

Kitces notes that while the regulatory concern about reverse churning is appropriate, it “raises troubling concerns when paired with the growing popularity of using index funds, ETFs, and passive investment approaches. How is an advisor supposed to justify an ongoing advisory fee when the right thing for the client to do might really be to do nothing? And what if the bulk of the advisor’s AUM fee is actually for other non-investment (i.e., financial planning) services, paired together with an otherwise passive investment portfolio?”

Assessment

Regulators will probably need to address the difference between reverse churning and implementing a prudent passive investment strategy. That won’t happen before there is a lot of confusion that demands clarification. In the meanwhile, fee-only advisors who embrace a passive investment strategy will have to add another layer of busywork by documenting what they actively do for clients on an ongoing basis. Clearly, this will be easier for fiduciary advisors who also provide financial planning than for those who only provide investment advice. 

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

 Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

WEGO Health Nominates the ME-P as “Best- in-Show” Blog

Join Our Mailing List 

WEGO Nomination 2017

By the WEGO Health Team

Dear Dr. David Edward Marcinko MBA,

Congratulations on your nominations for a WEGO health activist award.

We wanted to let you know that you’ve been nominated for the WEGO health activist award –

This nomination will appear on your nominee profile – feel free to update your personal bio if needed and share this new achievement with your family, friends, patients, students and clients community.

******

Assessment

And, your ME-P readers, visitors and subscribers can view your entire profile; here.

Congratulations!

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

On Living Wills

Death is Inevitable

By Rick Kahler CFP®

As inevitable as death is, given the way we avoid planning for it we seem to believe we will evade it if we don’t talk about it. Two-thirds of Americans don’t have a will or a health care advanced directive.

Financial planners like myself often preach that everyone must have both. However, there are exceptions to most rules, as well as times that the best preparation in the world goes awry.

No will

Here are some scenarios where you may not need a will.

First, you have no minor children and you don’t own anything of value or that you want to bequeath to someone.

Second, you do have assets, but all of them are transferable without a will. These include retirement accounts, annuities, assets like homes or bank accounts that are owned jointly, and assets like brokerage accounts or real estate that will Transfer on Death (TOD) to a named beneficiary.

Health care advanced directives

What about a health care advanced directive (HCAD)? This is any document that gives instructions or appoints someone to give direction about your health care. Living wills and Health Care Durable Powers of Attorney are two of the most popular HCADs.

Many people think you must use a state-provided form for a HCAD to be effective. According to the Commission of Law & Aging, most states do not require a form but do require your HCAD to be properly signed and witnessed. It’s best to have your directive drawn by an attorney, as most forms are too general or include generic options that may not apply to your needs or wishes.

Another myth is the notion that HCADs are legally binding on health care providers and their institutions. They are not. An advanced directive just gives healthcare providers immunity if they follow your instructions. The healthcare providers can refuse to comply with your directive. This is especially true in an emergency situation where the attending EMS must attempt to resuscitate you and get you to a hospital. In some states, if you and your doctor have signed a special form and you wear a special identification bracelet the attending EMS may choose not to resuscitate you.

Also, just giving your directive to your doctor is no guarantee that the directive will show up in your medical records. You, or your proxy, must check with each institution you visit or are transferred to and be sure it’s on file.

Some people fear that naming a health care agent means that you give up your right to make health care decisions. That is not true. A person retains the right to make all their own healthcare decisions unless they become incompetent.

Many people don’t do directives because they think they must understand all the choices and be crystal clear about their wishes. This is not necessarily the case. If nothing else, a directive appoints a person you trust to make decisions. And as with any legal document, you may always change your directive when you wish.

If all your relatives who can legally make healthcare decisions for you agree, you may not need an HCAD to stop treatment near the end of life. Still, a living will can make the decision less difficult. It becomes very important in the event your closest relatives disagree on what is best for you.

***

Not today – DEATH!

***

Like any good estate planning, the best strategy for both wills and HCADs is to focus on what you would like to happen today, rather than anticipating events and circumstances into the future. Then, as well as communicating your wishes verbally, put your thoughts in writing and provide copies to your doctors and loved ones. 

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

On “Financial Advisor” Salesmen and Saleswomen

UGH! Financial Services still not a real Profession


By Dr. David Edward Marcinko MBA MEd Certified Medical Planner™

http://www.CertifiedMedicalPlanner.org

Introduction

A few weeks ago I received the following unsolicited email job exhortation:

Dear David,

Our xxx/ooo office is currently hiring “Financial Advisors” with Series 7 and 63 Certifications. The minimum requirements include: high school diploma or GED equivalent, 6+ months of experience in customer service and experience in a sales environment. We offer paid training and access to full benefits.

Learn more about this position and apply today: xxx/ooo

***    *** 

Assessment

GED; a very high credentials bar, indeed!

NOTE: My friend and colleague, the late great Dick Wagner JD CFP™ who wrote extensively about financial planning as a “profession”, would be mortified.  

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

VOTE: Dr. David E. Marcinko WEGO HEALTH AWARDS 2017

Join Our Mailing List

By Ann Miller RN MHA

[Executive Director for the Institute of Medical Business Advisors, Inc]

After launching and blogging on the http://www.MedicalExecutivePost.com for 11 years, and receiving over 2,000 nominations, the 2017 WEGO HEALTH AWARDS endorsements are now OPEN! It’s time to take a moment and endorse those who you think best represent each category.

An endorsement is essentially your vote and is very important to the WEGO Best-in-Show Blog Health Awards this cycle!

And so, we humbly ask you to vote for our founding publisher Dave Marcinko

dem-2

Dr. David Edward Marcinko MBA MEd CMP®

[Abbreviated Biography]

Distinguished Professor, Endowed Chairman and Wall Street physician executive Dr. David Edward Marcinko MBBS DPM MBA MEd BSc CPHQ® CMP® is originally from Loyola University MD, Temple University in Philadelphia and the Milton S. Hershey Medical Center in PA; Oglethorpe University, and Atlanta Hospital & Medical Center in GA; and Aachen City University Hospital, Koln-Germany. He is one of the most innovative global thought leaders in health care business and entrepreneurship today.

Dr. Marcinko is a board certified physician, surgical fellow, hospital medical staff Vice President, public and population health advocate, and Chief Executive & Education Officer with more than 400 published papers; 5,150 op-ed pieces and over 135+ domestic/international presentations to his credit; including the top 10 biggest pharmaceutical companies and financial services firms in the nation. He is also a best-selling Amazon author with 30 published text books in four languages [National Institute of Health, Library of Congress and Library of Medicine.

Dr. Marcinko is a Managerial Healthcare Accountant and past Editor-in-Chief of the respected quarterly print “Journal of Health Care Finance“, and a former Certified Financial Planner® who was named “Health Economist of the Year” in 2010, by PM magazine. He is a Federal and State court approved expert witness featured in hundreds of peer reviewed medical, business, management and trade publications [AMA, ADA, APMA, AAOS, Physicians Practice, Investment Advisor, Physician’s Money Digest and MD News]. As a licensed insurance agent, RIA and SEC registered affiliate, Dr. Marcinko is Founding Dean of the fiduciary focused CERTIFIED MEDICAL PLANNER® chartered designation education program: http://www.CertifiedMedicalPlanner.org

He is also the Editor-in-Chief of the print, and online, HEALTH DICTIONARY SERIES® WIKE project: http://www.HealthDictionarySeries.org AND co-founder of the board certification, re-certification and state licensure education, preparation & Computer Based Testing [CBT] firm, FARC, Inc: http://PodiatryPrep.org

Dr. Marcinko’s professional memberships include: ASHE, AHIMA, ACHE, ACME, ACPE, MGMA, FMMA and HIMSS. Dr. Marcinko is a MSFT Beta tester, Google Scholar, “H” Index favorite and one of LinkedIn’s “Top Cited Voices”.

Presently, Professor Marcinko is “ex-officio”, and R&D Scholar-on-Sabbatical, for iMBA, Inc. His current grant-funded book, and WIKI styled cloud sourced project-in-progress in public health economics, is: http://www.HobsonsChoiceMedicine.com

Click Here to Endorse

wego

THANK YOU!

***

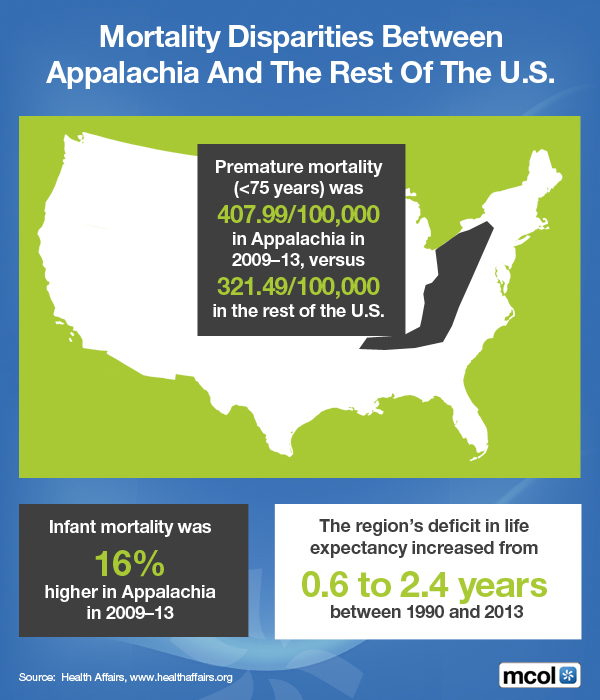
Mortality Disparities Between Appalachia and the Rest of the USA

For the Period 2009-2013

By http://www.MCOL.com

***

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***

On Veterinary Physicians

Join Our Mailing List

“Want a kitten? It’s free”

Rick Kahler MS CFP®

This is an offer I would turn down in a heartbeat. My lack of enthusiasm for cats would far outweigh my frugal appreciation of getting something for nothing.

Even the most ardent cat lover, though, would be wise to think twice before accepting a free kitten. Just as there is no such thing as a free lunch, there is absolutely no such thing as a free pet. I don’t care how “free” the initial cost of any pet is, there will be a cost to owning it. For most pets, the expense of ongoing maintenance is so substantial that the initial cost of the pet becomes insignificant.

A Story

My family once inherited a “free” pet, Sammy the Salamander. He lived the life of Riley for the next 7 years, with a continuous supply of fresh crickets, water, and mulch. At $2 a week, our total cost over his lifetime was $700. Fortunately, he passed peacefully under his rock, so there were no vet costs.

I once had a retired client, with an annual income of $60,000, who opted for medical intervention when her 12-year-old cat was diagnosed with cancer. Her vet bill for surgery and medication came to $12,000. The cat died shortly afterward, but the blow to her standard of living lasted for years while she paid off the debt. I don’t know how much, if anything, she paid for the cat originally. What I can tell you is the initial cost of the cat paled in comparison to its life-long upkeep.

Vet bills can end up to be a significant cost for any pet. According to a July 2017 survey of 1,000 pet owners by Ask.Vet, 40% of pet owners spend more than $500 a year at the vet. The site suggest one reason is that pet owners often ignore their pet’s wellness until a crisis materializes. Maybe annual physicals are as important for pets as they are for people. Of course, in this regard, many people don’t take any better care of themselves than they do of their pets.

***

427_1

***

Survey

According to a second survey of 500 dog and/or cat owners by LendEDU, dogs cost their owners an estimated total of just over $2,000 per year while cats averaged just over $1,000. Those who owned only dogs said they would spend over $10,000 to save a dog with a life-threatening condition. Cat-only people were willing to spend about $3,500. Those with both dogs and cats would spend over $10,000 for either one.

Ironically, the Ask.Vet survey found that the highest vet bills come from the smallest pets, with a gerbil being the most expensive. Eighty percent of gerbil owners surveyed spent more than $500 a year on vet bills. Mouse owners were close behind at 79%. Rounding out the top ten were alpacas (75%), goats (72%), chinchillas (70%), sheep (67%), hedgehogs (67%), guinea pigs (64%), pot-bellied pigs (63%), and finally frogs (60%).

Frogs, really? Who would spend $500 a year on vet bills for a frog? I guess the same person that would spend $500 on a gerbil.

I was surprised that the top ten list didn’t include some of the most common pets like dogs, cats, and horses. The survey found that the five pets with the lowest vet bills, in order from top to bottom, were dogs, cats, fish, birds, and turtles.

Assessment

I think the message here is clear. Before you take on any kind of pet, consider whether you can afford the care it will need. And if someone offers you a free gerbil or a free turtle, go for the turtle. 

Editor’s Note: This is the first ME-P on the topic. Continue reading

University Alum Founded Start-Ups

National Universities

[By staff reporters]

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***

SoftBank’s big plan for a smarter internet is brilliant

Enter the Singularity of A.I.

[By Vitaliy Katsenelson CFA]

Masayoshi Son doesn’t do anything small nor does he do things in a simple way.

SoftBank’s big plan for a smarter internet is brilliant

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™    8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

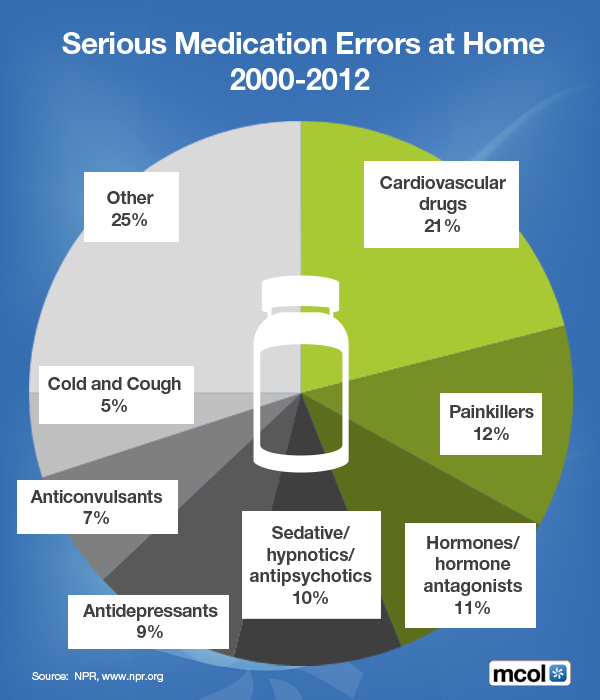
On Serious Medication Errors at Home

Circa 2000-2012

By http://www.MCOL.com

***

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***

Doctor Shortage Under Obamacare?

 Join Our Mailing List

 Fears Put to Rest

By AUSTIN FRAKT PhD

The demand for primary care doctors has gone up as more people have gotten health care coverage …. But so has appointment availability.

Doctor Shortage Under Obamacare? Fears Are Put to Rest

 Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

 Product DetailsProduct Details

***

Healthcare Technology in the News

Join Our Mailing List

By Staff Reporters

Healthcare consumers show mounting interest in virtual, on-demand care
Fierce Healthcare, August 14, 2017

Transforming the mHealth Experience With Digital Health Assistants
HIT Consultant, August 14, 2017

Google buys smartphone health monitoring startup Senosis
Pharma Phorum, August 14, 2017

Could Trump’s Opioid Emergency Boost Telemedicine, mHealth Use?
mHealth Intelligence, August 11, 2017

Trump Administration Takes on VA Telehealth Opportunities
The Natonal Law Review, August 11, 2017

More and more businesses are offering telehealth services as an employee benefit
MedCity News, August 9, 2017

VR Glasses Give Doctors a New mHealth Tool to Treat Concussions
mHealth Intelligence, July 31, 2017

New Senate bill seeks to reduce restrictions on telemedicine use
MobiHealth News, July 31, 2017

The allure of health care for tech giants
Axios, July 20, 2017

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***

America’s embarrassing digital divide

Join Our Mailing List

An FCC rule change could falsely obscure America’s embarrassing digital divide

[By MIT Technology Review]

FCC chairman Ajit Pai has a theory. He reckons that Internet access on a phone is as good as high-speed broadband access at home.

Now he’s looking into changing his agency’s guidelines, so that places in the U.S. with decent mobile coverage are deemed “connected,” even if broadband access is a no-go. If enacted, the sleight of hand could shrink America’s embarrassing digital divide, but would leave rural folks with tight data caps, low speeds, and less hope for ever getting broadband.

***

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***


On Naming Beneficiaries

Estate  Planning

By Jason Dyken, MD MBA

[Dyken Wealth Strategies]

Dear David,

It’s not uncommon for people to assume that having a will in place is enough to ensure their assets will pass to their named beneficiaries in the manner they desire. However, certain financial assets, including 401(k) and IRA retirement accounts, as well as life insurance policies bypass a will or trust.

One benefit is that when the account owner dies, the assets go directly to the beneficiaries named on the accounts, bypassing the probate process. However, because these beneficiary designations override your will, they need to be carefully coordinated with your overall estate plan.

Some of the most common mistakes people make in regard to beneficiary designations include:

  • Forgetting to update named beneficiaries in the event of divorce. If your previous spouse is still listed as the beneficiary on your retirement account or life insurance policy at the time of your death, the assets will go to your ex, regardless of whether he or she is a named beneficiary in your will.
  • Naming minor children as beneficiaries or contingent beneficiaries. In the event you and your spouse predecease your children, they could directly inherit large sums of money from retirement accounts or life insurance policies—assets that are not governed by stipulations you may have included in your will or trust documents. Avoid leaving assets to minors outright. If you do, a court will appoint someone to look after the funds which can be a time consuming and expensive process.
  • Using beneficiary forms that don’t allow your assets to pass “per stirpes,” or equally among the branches of a family. For example, let’s say you name your three adult children as the beneficiaries of your IRA. If one of them predeceases you, you might want that child’s share to go to his or her children. However, many standard beneficiary forms don’t include per stirpes provisions and only allow per capita provisions where your two remaining adult children would share the assets. In certain cases, you can ask to include non-standard language to the beneficiary form, but make sure the financial services company actually has the capabilities in place to manage per stirpes distributions first.

***

***

Assessment

An estate planning attorney or financial advisor with experience in estate and legacy planning can help ensure your beneficiary designations are up-to-date and aligned with your wishes and preferences.

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

On Mental Health Gender and Racial Disparities

USA Adults in 2015

http://www.MCOL.com

***

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Product DetailsProduct Details

***

Royal College of General Practitioners Recommends: “Comprehensive Financial Planning Strategies for Doctors and Advisors”

 Join Our Mailing List

Comprehensive Financial Planning Strategies for Doctors and Advisors

RECOMMENDATION

***

rcgp-logo

Drawing on the expertise of multi-degreed doctors, and multi-certified financial advisors, Comprehensive Financial Planning Strategies for Doctors and Advisors [Best Practices from Leading Consultants and Certified Medical Planners™] will shape the industry landscape for the next generation as the current ecosystem strives to keep pace.

Traditional generic products and sales-driven advice will yield to a new breed of deeply informed financial advisor or Certified Medical Planner™.

The profession is set to be transformed by “cognitive-disruptors” that will significantly impact the $2.8 trillion healthcare marketplace for those financial consultants serving this challenging sector. There will be winners and losers.

The text, which contains 24 chapters and champions healthcare providers while informing financial advisors, is divided into four sections compete with glossary of terms, Certified Medical Planner™ curriculum content, and related information sources.

cmp

http://www.CertifiedMedicalPlanner.org

1. For ALL medical providers and financial industry practitioners
2. For NEW medical providers and financial industry practitioners
3. For MID-CAREER medical providers and financial industry practitioners
4. For MATURE medical providers and financial industry practitioners

Using an engaging style, the book is filled with authoritative guidance and healthcare-centered discussions, providing the tools and techniques to create a personalized financial plan using professional advice.

Comprehensive coverage includes topics likes behavioral finance, modern portfolio theory, the capital asset pricing model, and arbitrage pricing theory; as well as insider insights on commercial real estate; high frequency trading platforms and robo-advisors; the Patriot and Sarbanes–Oxley Acts; hospital endowment fund management, ethical wills, giving, and legacy planning; and divorce and other special situations.

The result is a codified “must-have” book, for all health industry participants, and those seeking advice from the growing cadre of financial consultants and Certified Medical Planners™ who seek to “do well by doing good,” dispensing granular physician-centric financial advice:

Omnia pro medicus-clientis

  Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

DR. DAVID EDWARD MARCINKO MBA CMP™

ISBN Number: 9781482240283

Number of pages: 744

Publisher: CRC Press

reward

AWARDS

***

Why Amazon will NOT kill this business!

Why Amazon Will Not Kill This Business

By Vitaliy Katsenelson CFA

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

Transitioning to Value Based Medical Care Payments

Five Best Practices for Health Plans

http://www.MCOL.com

***

***

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™8Comprehensive Financial Planning Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***

Health Information Technology [EMR] Update

2014 to 2017


By D. Kellus Pruitt DDS

Three years ago

“When Patients Fear EHR – When patients believe paper medical records are safer and more private than electronic ones, their health can suffer. Many members of the public mistakenly believe electronic health records (ehrs) are less secure than paper files. Magnified by misinformation and political distortion of facts, an unnecessary fear has taken root in the minds of many consumers — often with serious consequences.” 

-Mansur Hasib

Cybersecurity Professional – Author and Speaker in commentary for informationweek, July 28, 2014

Http://www.informationweek.com/healthcare/electronic-health-records/when-patients-fear-ehr/a/d-id/1297519

This week 

“Doctors claim medical records system puts patient safety at risk – PROBLEMS with Queensland Health’s electronic medical record system are angering health workers, with fed-up senior doctors circulating a document slamming the technology and those in charge of it.”

-Kara Vickery and Janelle Miles – The Courier-Mail, July 25, 2017.

Http://www.couriermail.com.au/news/queensland/doctors-claim-medical-records-system-puts-patient-safety-at-risk/news-story/dc18cb388552eb4d179629c298a28408

“300,000 records breached in ransomware attack on Pennsylvania health system – The breach on Women’s Health Care Group of Pennsylvania was discovered in May, but hackers had unauthorized access to the system as early as January.”

-Jessica Davis – Health Care IT News, July 26, 2017

Http://www.healthcareitnews.com/news/300000-records-breached-ransomware-attack-pennsylvania-health-system

“HIPAA Data Breaches, Cyber Attacks Reported by 47% of Orgs – KPMG found that there was a 10 percentage point increase in reported HIPAA data breaches or cyber attacks from 2015 to 2017.”

-Elizabeth Snell – Health IT Security, July 27, 2017

Https://healthitsecurity.com/news/hipaa-data-breaches-cyber-attacks-reported-by-47-of-orgs

“Doctors frustrated that electronic records steal time from patients – Dr. Rebekah Gardner has to make a choice each time she sees a patient in her Rhode Island office: she can scroll computer screens and click boxes, or she can focus on the patient and take home the computer work.”

-Ronnie Cohen – Reuters, July 28, 2017

Http://www.reuters.com/article/us-health-records-electronics-iduskbn1ad2gt

“Plastic Surgery Associates data breach: Patients’ records, payment card details possibly compromised – The company said it discovered that some of its systems were infected with ransomware in February.”

-Hyacinth Mascarenhas – International Business Times, July 29, 2017

Http://www.ibtimes.co.uk/plastic-surgery-associates-data-breach-patients-records-payment-card-details-possibly-compromised-1632555

Conclusion

Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, urls and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.

Speaker: If you need a moderator or speaker for an upcoming event, Dr. David E. Marcinko; MBA – Publisher-in-Chief of the Medical Executive-Post – is available for seminar or speaking engagements. Contact: MarcinkoAdvisors@msn.com

OUR OTHER PRINT BOOKS AND RELATED INFORMATION SOURCES:

Risk Management, Liability Insurance, and Asset Protection Strategies for Doctors and Advisors: Best Practices from Leading Consultants and Certified Medical Planners™

***