BOARD CERTIFICATION EXAM STUDY GUIDES Lower Extremity Trauma
[Click on Image to Enlarge]
ME-P Free Advertising Consultation
The “Medical Executive-Post” is about connecting doctors, health care executives and modern consulting advisors. It’s about free-enterprise, business, practice, policy, personal financial planning and wealth building capitalism. We have an attitude that’s independent, outspoken, intelligent and so Next-Gen; often edgy, usually controversial. And, our consultants “got fly”, just like U. Read it! Write it! Post it! “Medical Executive-Post”. Call or email us for your FREE advertising and sales consultation TODAY [678.779.8597] E-mail: MarcinkoAdvisors1738@outlook.com
Medical & Surgical e-Consent Forms
ePodiatryConsentForms.com
iMBA Inc., OFFICES
Suite #5901 Wilbanks Drive, Norcross, Georgia, 30092 USA [1.678.779.8597]. Our location is real and we are now virtually enabled to assist new long distance clients and out-of-town colleagues.
ME-P Publishing
SEEKING INDUSTRY INFO PARTNERS?
If you want the opportunity to work with leading health care industry insiders, innovators and watchers, the “ME-P” may be right for you? We are unbiased and operate at the nexus of theoretical and applied R&D. Collaborate with us and you’ll put your brand in front of a smart & tightly focused demographic; one at the forefront of our emerging healthcare free marketplace of informed and professional “movers and shakers.” Our Ad Rate Card is available upon request [678-779-8597].
Psychiatry is the branch of medicine concerned with prevention, diagnosis and treatment of mental disorders. Its domain includes disorders of thought, emotion, intellect and conduct. The overall prevalence of psychiatric illness is one-fourth to one-third of the total population, and 30-60% of general hospital patients. A percentage of patients may thus be expected to display a variety of mental difficulties associated with, or independent from, their primary complaints.
For example, in 1984, Marcinko documented a report that stated that one-third of all surgical patients encountered difficulty with psychological adjustments before and after surgery. Therefore, understanding human behavior can contribute to the medical practitioner’s success
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on October 16, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
In September, the Consumer Price Index for All Urban Consumers rose 0.6 percent, seasonally adjusted (SA), and rose 3.7 percent over the year, not seasonally adjusted (NSA). The index for all items less food and energy rose 0.3 percent in September (SA), up 2.6 percent over the year (NSA).
Next Release
The Consumer Price Index for October 2026 is scheduled to be released on November 10, 2026, at 8:30 A.M. Eastern Time.
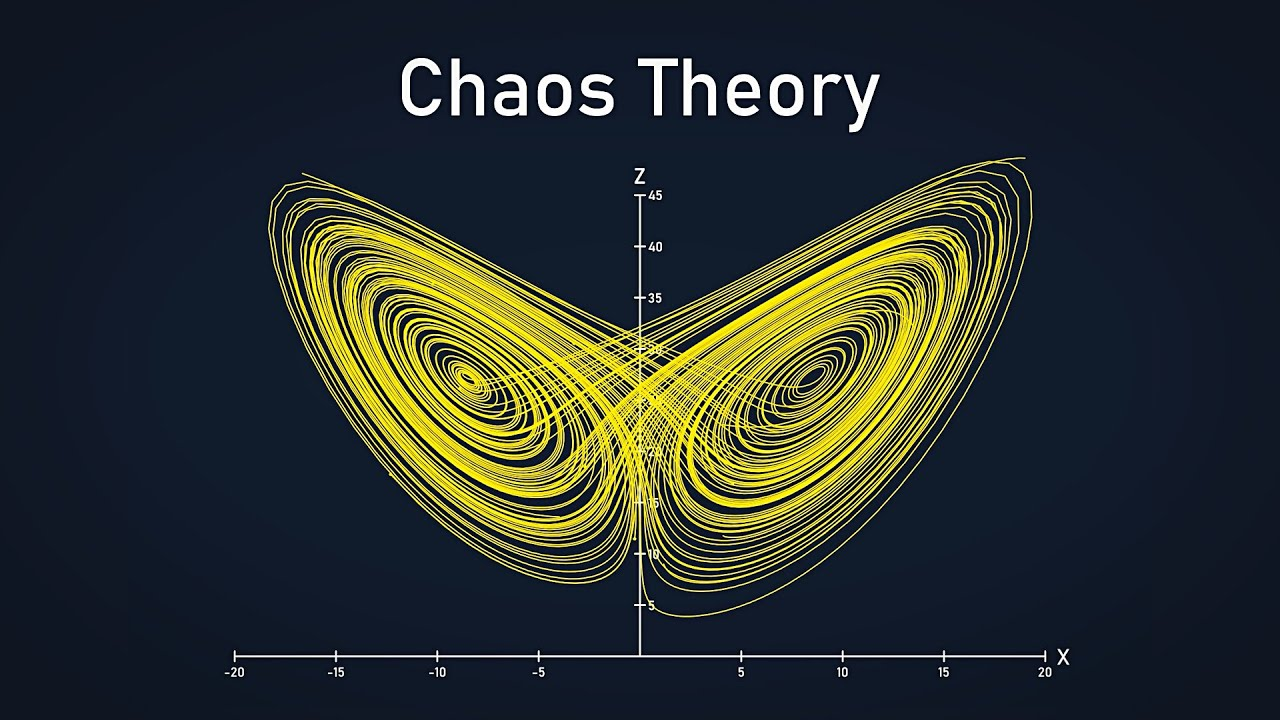
Chaos theory in microeconomics is ultimately a way of seeing markets not as tidy, predictable machines but as living systems where small actions by individual agents can cascade into large, unexpected outcomes. Microeconomics traditionally focuses on how consumers, firms, and workers make decisions under constraints. It often assumes rational behavior, smooth curves, and stable equilibria. Chaos theory disrupts that picture. It argues that even when individuals follow simple, deterministic rules, their interactions can produce nonlinear, unstable, and highly sensitive dynamics. In other words, micro-level decisions can generate macro-level unpredictability.
The foundation of chaos theory is sensitivity to initial conditions—the idea that tiny differences at the start can lead to dramatically different outcomes later. In microeconomics, this plays out in markets where individual choices interact through feedback loops. A slight change in consumer preference, a small shift in a firm’s pricing strategy, or a minor adjustment in expectations can ripple outward. These ripples can amplify, collide, and transform into large market movements. The classic supply-and-demand diagram suggests smooth adjustments, but real markets often behave more like turbulent ecosystems.
Consider consumer behavior. Traditional microeconomic models assume stable preferences and predictable responses to price changes. Chaos theory suggests something more dynamic. Preferences evolve, are influenced by social networks, and can shift suddenly. A small trend—say, a handful of consumers adopting a new product—can explode into widespread demand if social feedback loops kick in. Conversely, a tiny reputational shock can collapse demand. These nonlinear patterns resemble chaotic systems where outcomes depend heavily on initial conditions and interactions rather than simple price signals.
Firms also operate within chaotic dynamics. A slight change in cost structure, a small innovation, or a minor strategic adjustment can set off competitive cascades. One firm’s price cut may trigger retaliatory cuts, shifting the entire market equilibrium. A small technological improvement can destabilize established industries. Chaos theory helps explain why industries sometimes experience sudden shakeups, why dominant firms can fall quickly, and why competitive landscapes evolve unpredictably. Even when firms behave rationally, their interactions can produce chaotic outcomes.
Market competition itself often resembles a chaotic system. In models where firms repeatedly adjust prices or quantities based on competitors’ actions, the resulting dynamics can oscillate, diverge, or behave unpredictably. Instead of converging to a stable equilibrium, markets may cycle endlessly or shift abruptly. Chaos theory shows that even simple strategic rules—like adjusting output based on last period’s profits—can generate complex patterns. This challenges the assumption that markets naturally gravitate toward stability.
Chaos theory also reshapes how economists think about supply chains. Microeconomics traditionally treats supply chains as linear sequences of production. In reality, they are networks of interdependent agents. A small disruption at one node—a delayed shipment, a minor shortage, a slight increase in demand—can propagate through the network. These ripples can amplify, producing large swings in inventory, pricing, and production. The “bullwhip effect,” where small changes in consumer demand cause large fluctuations upstream, is a classic example of chaotic dynamics in microeconomic systems.
Expectations play a central role in microeconomic chaos. Individuals and firms make decisions based not only on current conditions but on beliefs about the future. These beliefs are influenced by limited information, heuristics, and social cues. A small rumor or a slight shift in sentiment can alter expectations, which then alter behavior. This feedback loop can generate chaotic patterns in markets. For example, a minor concern about future prices can trigger hoarding, which then drives actual price increases. Chaos theory helps explain why expectations-driven markets—like housing, cryptocurrency, or collectibles—often behave unpredictably.
Labor markets also exhibit chaotic dynamics. A small change in hiring practices, a slight shift in worker preferences, or a minor technological adjustment can reshape job flows. Workers respond to wages, working conditions, and expectations, while firms respond to productivity, costs, and competition. These interactions can produce nonlinear outcomes: sudden shortages, rapid wage spikes, or unexpected declines in labor participation. Chaos theory highlights how sensitive labor markets are to small changes and how difficult it is to predict their evolution.
Even bargaining and negotiation reflect chaotic principles. In microeconomic models of bargaining, small differences in information, timing, or expectations can lead to vastly different outcomes. Chaos theory suggests that negotiation dynamics may not converge smoothly but may jump between equilibria depending on subtle shifts in strategy. This helps explain why seemingly minor details—tone, timing, or framing—can dramatically influence economic outcomes in real-world negotiations.
***
***
Chaos theory also intersects with behavioral microeconomics. Human decision-making is nonlinear, emotional, and context-dependent. Small psychological triggers can produce large changes in behavior. When millions of individuals behave this way simultaneously, the aggregate effects can be chaotic. Herd behavior, fads, and sudden shifts in sentiment all reflect nonlinear micro-level dynamics. Chaos theory provides a framework for understanding why markets sometimes behave irrationally and why small nudges can produce large outcomes.
Ultimately, chaos theory in microeconomics is not about rejecting traditional models. It is about enriching them. It acknowledges that individual agents operate within complex networks of interactions, feedback loops, and evolving expectations. It teaches that micro-level decisions can produce macro-level unpredictability and that stability is often an illusion. Chaos theory encourages economists to embrace complexity, recognize the limits of prediction, and design policies and strategies that are robust to uncertainty.
In practice, this perspective fosters humility and creativity. It reminds us that markets are not mechanical systems but dynamic human environments. It encourages economists, policymakers, and businesses to pay attention to small details, subtle signals, and emerging patterns. Chaos theory does not offer simple answers, but it provides a powerful lens for understanding why microeconomic systems behave the way they do—and why small actions can matter enormously.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
The cost of medical education in the United States has climbed to a level that forces students, families, and even institutions to confront uncomfortable questions about who can realistically pursue a career in medicine. While the profession carries prestige, purpose, and the promise of financial stability, the path to becoming a physician is increasingly defined by staggering tuition bills, years of lost income, and long‑term debt obligations that shape graduates’ lives for decades. The price tag has grown so large that it is no longer just an economic issue; it is reshaping the demographics, motivations, and mental health of future physicians, and ultimately influencing the healthcare system itself.
Medical school tuition alone often exceeds what many Americans earn in a year. Students routinely face annual costs that can surpass $60,000 to $70,000, and that figure does not include housing, food, transportation, exam fees, or the cost of applying to residency programs. When the full journey is tallied—undergraduate education, medical school, and the years of training that follow—many new physicians emerge with debt loads well above $200,000. Some carry balances closer to $300,000. These numbers are not abstract; they shape every decision a student makes, from where they apply to school to what specialty they choose.
The financial pressure begins even before medical school acceptance. The application process itself is expensive. Prospective students pay for standardized tests, primary applications, secondary applications, and travel for interviews. For many, this phase alone costs several thousand dollars. Students from lower‑income backgrounds often struggle to compete in this early stage, not because of academic ability, but because the financial barrier is already too high. The pipeline narrows before training even begins.
Once enrolled, the intensity of medical education makes it nearly impossible for students to work part‑time to offset costs. The curriculum demands long hours, constant studying, and clinical responsibilities that leave little room for supplemental income. As a result, most students rely heavily on loans. Interest accumulates quickly, and because medical school lasts four years—followed by residency training that can stretch from three to seven years—many graduates watch their balances grow even as they work full‑time caring for patients.
The burden of debt influences career choices in ways that ripple across the healthcare system. Students who might otherwise pursue lower‑paying specialties such as primary care, pediatrics, or psychiatry often feel compelled to choose fields with higher salaries to manage their financial obligations. This dynamic contributes to shortages in essential specialties and exacerbates disparities in access to care. The country needs more primary care physicians, yet the economics of medical education push students away from these roles. In this way, the cost of training does not just affect individuals; it shapes national healthcare outcomes.
The psychological toll is equally significant. Medical school is already known for its demanding workload and high stress levels, but financial anxiety adds another layer of pressure. Students worry about every dollar they borrow, every interest payment, and every future bill. This chronic stress can affect academic performance, personal relationships, and mental health. For some, the weight of debt becomes a defining feature of their medical journey, overshadowing the excitement and purpose that initially drew them to the profession.
The high cost also affects diversity within medicine. Students from wealthy families can navigate the financial landscape more easily, while those from lower‑income backgrounds face barriers that are often insurmountable. This creates a profession that does not fully reflect the population it serves. Diverse physicians bring cultural insight, language skills, and lived experiences that improve patient care. When the cost of education limits who can enter the field, the entire healthcare system loses these valuable perspectives.
***
***
Institutions often justify high tuition by pointing to the expense of running medical programs. Teaching hospitals, laboratories, simulation centers, and faculty salaries require substantial funding. While these costs are real, the escalation of tuition has outpaced inflation and income growth for decades. Students are left wondering whether the financial structure of medical education is sustainable or whether it is drifting toward a crisis that will eventually force reform.
Despite these challenges, many students continue to pursue medicine because they feel called to the work. They want to heal, to serve, and to contribute to society in a meaningful way. But passion alone cannot erase the financial realities. The question is not whether medical education should be rigorous or resource‑intensive—it must be both. The question is whether the current model is fair, accessible, and aligned with the nation’s healthcare needs.
The high cost of medical education is more than a personal burden; it is a systemic issue with far‑reaching consequences. It shapes who becomes a doctor, what specialties they choose, where they practice, and how they experience their training. It influences the availability of care in underserved communities and contributes to workforce shortages in critical fields. Addressing this challenge will require creativity, commitment, and a willingness to rethink long‑standing assumptions about how physicians are trained.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Financial Relativity as a Perspective-Based Framework
At its core, financial relativity argues that value, risk, and opportunity are not fixed properties. They change based on the observer’s circumstances. A pension fund with a 40‑year horizon experiences volatility as background noise; a day trader experiences the same volatility as existential threat. A government views inflation as a macroeconomic variable; a household views it as a direct assault on purchasing power. The underlying reality is the same, but the interpretation—and the resulting decisions—are relative.
This relativity of perspective explains why financial debates often feel circular. Two people can look at the same data and reach opposite conclusions because their frames of reference differ. The theory suggests that instead of searching for universal financial truths, we should analyze the observer’s position first. Only then does the behavior of markets make sense.
Time as the Central Variable
In physics, relativity reshapes our understanding of time. In finance, time is the most important dimension. Every financial decision—investing, borrowing, saving, hedging—depends on how much time the observer has and how they perceive it.
Short-term observers (traders, speculators, leveraged investors) experience markets as chaotic, fast-moving, and dominated by noise.
Long-term observers (retirement savers, endowments, sovereign wealth funds) experience markets as slow-moving systems governed by cycles, mean reversion, and structural trends.
The same asset can be “risky” in one frame and “safe” in another. A volatile stock may be dangerous for a trader but ideal for a long-term investor who sees volatility as the price of future growth. Financial relativity argues that time doesn’t just influence risk—it defines it.
Relativity of Risk and Reward
Traditional finance treats risk as measurable and objective. The theory of financial relativity challenges this by asserting that risk is always relative to goals, constraints, and psychology.
For example:
A retiree holding cash sees risk in market downturns.
A young investor holding cash sees risk in inflation eroding future wealth.
A corporation sees risk in credit spreads and refinancing windows.
A policymaker sees risk in systemic instability.
Each observer is correct within their own frame. Financial relativity helps explain why universal risk metrics—like volatility or beta—often fail to capture lived financial experience. They measure movement, not meaning.
***
***
Incentives as Gravitational Forces
In relativity, gravity bends space-time. In finance, incentives bend behavior. They shape how individuals and institutions interpret information, allocate capital, and respond to uncertainty.
Analysts paid for short-term performance emphasize quarterly results.
CEOs compensated with stock options emphasize share price.
Regulators emphasize stability.
Venture capitalists emphasize growth.
These incentive structures create “financial gravity wells” that pull decisions in predictable directions. The theory of financial relativity argues that markets cannot be understood without mapping these incentive fields. They distort financial space just as gravity distorts physical space.
Information and the Observer Effect
Financial relativity also incorporates an observer effect: the act of observing or acting on information changes the system itself. Markets react to expectations, forecasts, and sentiment. A rumor can move prices; a central bank statement can reshape global capital flows. Information is not passive—it is an active force.
This explains why markets often behave irrationally or overshoot fundamentals. Observers influence the system, and the system influences observers, creating feedback loops that resemble the curvature of space-time.
Relativity of Value
Value is often treated as intrinsic, but financial relativity argues that value is contextual. It depends on:
liquidity needs
tax considerations
regulatory constraints
alternative opportunities
personal or institutional priorities
A bond yielding 4% may be unattractive to a hedge fund but essential to an insurance company. A startup may be worthless to a bank but priceless to a venture capitalist. Value is not a universal constant; it is relative to the observer’s world.
Implications for Financial Decision-Making
The theory of financial relativity encourages a shift in thinking:
Understand your frame of reference. Your time horizon, incentives, constraints, and goals define what is risky or valuable.
Recognize that others operate in different frames. Market movements often reflect conflicting perspectives rather than irrationality.
Avoid universal prescriptions. What is “good” or “bad” financially depends on who you are and what you need.
Embrace dynamic interpretation. As your circumstances change, your financial truths should change with them.
Conclusion
The theory of financial relativity is a conceptual framework that treats financial behavior, market dynamics, and economic outcomes as dependent on the observer’s position, incentives, and time horizon—much like Einstein’s relativity treats measurements of space and time as dependent on the observer’s frame of reference. It isn’t a formal academic doctrine, but it’s a powerful way to understand why markets behave differently for different participants, why risk is never absolute, and why financial truths often shift depending on who is looking and when.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Robert E. Hall and Michael Woodford win Nobel memorial prize in economics
American economists Robert E. Hall and Michael Woodford won the 2026 Nobel Memorial Prize in Economic Sciences for research that has helped governments and central banks manage economic shocks and stabilise economies during crises.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on October 12, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
Monday, October 12th 2026
Today is a federal/bank holiday in observance of Columbus Day.
U.S. equity, options, and futures markets will be open but it’s a non-settlement day.
All trades placed on Friday, October 9th 2026, will settle on Tuesday, October 13th, 2026.
All fixed income and bond markets will be closed.
Requests to move money received after the standard cut-off times on Friday, October 9th 2026, will not be processed until Tuesday, October 13th 2026.
Global Markets
All Canadian markets will be closed in observance of Canadian Thanksgiving. Dually listed Canadian stocks will trade in the U.S. markets on Monday, October 12th 2026.
Posted on October 11, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
The Treasury Department and IRS have finalized regulations regarding the deduction of up to $10,000 in personal car loan interest by individuals for tax years 2025 through 2028. This includes regulations on information returns required to be filed by a lender or other person engage in a trade or business who receives $600 or more of qualified interest during the calendar year.
The final regulations adopt the proposed regulations published in January 2026 (NPRM REG-113515-25) with some changes in response to public comments.
Classic Definition: Research from Ernst-Young [Nikhil Lele and Yang Shim] uncovered a chasm between how consumer patients think they’re doing financially, and the actual state of their finances. Even more striking, their study suggested that improving consumers’ financial health will become one of the top imperatives in reframing consumer financial services.
Modern Circumstance: For example, the study asked consumers to rate their own financial health, and 83 percent rated themselves “good,” “very good” or “excellent.” Now, contrast this figure with what is known about their actual situation:
60 percent of Americans say they are financially stressed.
56 percent of Americans have less than $10,000 saved for retirement.
40 million American families have no retirement savings at all.
40 percent of Americans are not prepared to meet a $400 short-term emergency.
Paradox Example: Fortunately, even though the vast majority of consumers rate themselves as financially healthy, the study found that most still want to improve. Importantly for health economists, the attractive 25-34 and 35-49 year-old age groups were most likely to be extremely or very interested in improving their financial and economic health.
Paradox Example: Massively affluent consumer patients are even more interested in improving this paradox than their mass market counterparts.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on October 9, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
STOCKHOLM — Scientists Henri B. Kagan and Kenso Soai just won the Nobel Prize in chemistry for untangling mysterious mirror images in molecules, a discovery that has been used to develop countless drugs and transformed modern medicine.
Human Relations Theory is an important approach to management that emphasizes the role of people, social relationships, communication, and employee satisfaction in an organization. It developed as a reaction to earlier management theories that mainly focused on productivity, efficiency, rules, and financial incentives. One of the most important contributors to this approach was Elton Mayo, an Australian-born psychologist and sociologist who became closely associated with the Human Relations Movement. Mayo argued that workers are not simply economic beings motivated by money; they are also influenced by social relationships, recognition, group belonging, morale, and the attitudes of managers.
Elton Mayo’s ideas became particularly influential through the Hawthorne Studies, conducted at the Western Electric Company’s Hawthorne Works in Chicago during the 1920s and early 1930s. These studies helped draw attention to the importance of informal groups and human factors in the workplace. Human Relations Theory subsequently became an important foundation for modern organizational behavior and management.
Meaning of Human Relations Theory
Human Relations Theory refers to an approach to management that recognizes employees as social and psychological beings. According to this approach, organizational performance depends not only on physical working conditions and financial rewards but also on how employees feel about their work and their relationships with colleagues and supervisors.
Traditional management approaches tended to view employees primarily in terms of productivity and economic rewards. Human Relations Theory introduced a different perspective. It suggested that employees have social needs, such as the need for friendship, recognition, acceptance, respect, and a sense of belonging. When these needs are addressed, employees may develop greater commitment to their work and organization.
The theory therefore emphasizes the importance of communication, leadership, teamwork, employee participation, morale, and informal social groups. Managers are encouraged to understand employees and create working environments in which people feel valued and respected.
Elton Mayo and the Hawthorne Studies
Elton Mayo’s contribution to management is strongly associated with the Hawthorne Studies. The studies were initially designed to examine whether changes in physical working conditions affected worker productivity. Researchers examined factors such as lighting, working hours, rest periods, and other workplace conditions.
An important observation emerged from these experiments: changes in productivity could not always be explained simply by physical conditions. Workers’ attitudes, relationships, group behavior, and the attention they received from researchers appeared to influence their behavior.
Mayo and his colleagues concluded that workers were influenced by social factors within the workplace. Employees formed informal groups, developed their own standards of acceptable behavior, and responded to group expectations. This demonstrated that organizations contain both formal structures, created by management, and informal structures, created naturally through relationships among employees.
The Hawthorne Studies therefore helped shift attention from purely mechanical explanations of productivity toward the social and psychological aspects of work.
Main Principles of Human Relations Theory
One of the central principles of Human Relations Theory is that employees are social beings. People seek interaction with others and want to feel that they belong to a group. A workplace that ignores these needs may experience dissatisfaction and poor cooperation.
Another important principle is the importance of informal groups. Employees naturally form friendships and social groups, and these groups can influence attitudes and productivity. Informal group norms may sometimes be more influential than formal organizational rules.
Employee morale is also important. When workers feel respected, recognized, and valued, they may show greater enthusiasm toward their responsibilities. Managers therefore need to consider employee satisfaction alongside productivity.
The theory also emphasizes communication. Open and effective communication between managers and employees can reduce misunderstandings and improve cooperation. Employees are more likely to feel involved when managers listen to their opinions and explain organizational decisions.
Another principle is participative management. Employees can contribute useful knowledge about their jobs and working conditions. Giving workers opportunities to express their views can strengthen their sense of involvement and responsibility.
Finally, Human Relations Theory stresses the importance of leadership and supervision. Managers are not merely controllers of work; they also influence employee attitudes and relationships. Supportive leadership can encourage cooperation, trust, and commitment.
***
***
Importance of Human Relations Theory
Human Relations Theory made a significant contribution to management because it broadened the understanding of employee motivation. It showed that productivity cannot be understood entirely through wages, physical conditions, or formal rules. Human emotions and social relationships can also affect workplace behavior.
The theory also influenced the development of modern approaches to organizational behavior. Contemporary organizations pay attention to teamwork, employee engagement, organizational culture, leadership, communication, and workplace relationships. These areas reflect many of the concerns first emphasized by the Human Relations Movement.
The theory also changed the role of managers. Instead of seeing management only as the process of planning, organizing, and controlling work, it encouraged managers to develop interpersonal skills. A manager is expected to communicate effectively, understand employees, resolve conflicts, encourage teamwork, and create a positive working environment.
Furthermore, the theory highlighted the importance of informal organization. Every workplace has relationships and social networks that exist alongside its official hierarchy. Understanding these informal relationships can help managers improve cooperation and address workplace problems.
Criticism of Human Relations Theory
Although Human Relations Theory made important contributions, it has also been criticized. One criticism is that it may place too much emphasis on social relationships while giving insufficient attention to economic and structural factors. Employees are influenced by wages, job security, working conditions, career opportunities, and organizational policies as well as social relationships.
Another criticism concerns the interpretation of the Hawthorne Studies. Later scholars questioned some of the conclusions traditionally associated with the experiments and argued that the relationship between attention, workplace conditions, and productivity was more complicated than early accounts suggested.
The theory can also be criticized for assuming that greater employee satisfaction will automatically result in higher productivity. A satisfied employee is not necessarily a highly productive employee. Productivity can depend on technology, skills, resources, organizational structure, incentives, and many other factors.
Despite these limitations, Human Relations Theory remains significant because it introduced a more human-centered perspective into management.
Conclusion
Elton Mayo and the Human Relations Movement played an important role in changing the way organizations understand employees. Through the Hawthorne Studies, Mayo drew attention to the influence of social relationships, informal groups, communication, morale, and leadership on workplace behavior. His work challenged the idea that employees could be understood only through economic incentives and physical working conditions.
Human Relations Theory established that organizations are social systems as well as economic and technical systems. Employees have psychological and social needs, and these needs can influence their attitudes and behavior at work. Although the theory has limitations and some of the conclusions drawn from the Hawthorne Studies have been debated, its influence on management remains considerable. Modern ideas about teamwork, employee participation, communication, leadership, organizational culture, and employee engagement continue to reflect the central insight of the Human Relations approach: effective management requires attention not only to work and productivity but also to the people who perform the work.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on October 7, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
****
The Nobel Prize in Physiology or Medicine 2026 was awarded jointly to Karl Deisseroth, Peter Hegemann and Georg Nagel “for their discoveries concerning light-gated ion channels and optogenetics.”
The propensity to pay in healthcare refers to an individual’s willingness and ability to spend money on healthcare services, medicines, treatments, and other health-related needs. It is an important concept because healthcare decisions are influenced not only by medical needs but also by financial circumstances, personal preferences, perceptions of quality, and expectations about future health. Understanding the propensity to pay can help healthcare providers, policymakers, and organizations better understand how people make decisions about accessing and purchasing healthcare.
One of the main factors influencing a person’s propensity to pay is income. Individuals with higher incomes generally have greater financial flexibility and may be more willing to pay for private consultations, specialist services, advanced treatments, preventive care, or shorter waiting times. In contrast, people with lower incomes may postpone treatment, rely more heavily on publicly funded services, or choose less expensive alternatives. However, income alone does not determine healthcare spending. People may prioritize healthcare differently depending on their circumstances and personal values.
The perceived importance of a healthcare service also affects willingness to pay. When individuals believe that a treatment is essential or could significantly improve their health or quality of life, they may be willing to spend more. For example, someone experiencing severe pain may place a higher financial value on immediate treatment than on other types of expenditure. Similarly, parents may be particularly willing to pay for services that they believe will protect the health of their children. Preventive services, however, can be more difficult to value because their benefits may occur in the future rather than immediately.
Trust and perceived quality are also important. Patients are more likely to pay for healthcare when they believe that a provider is competent, trustworthy, and capable of delivering good outcomes. Reputation, communication, professional qualifications, facilities, and previous experiences can all influence this perception. A patient who has confidence in a particular doctor or hospital may be willing to pay more for its services than for an unfamiliar provider. Conversely, poor experiences or concerns about unnecessary treatment can reduce willingness to pay.
***
***
Insurance and the structure of healthcare financing can substantially change individual behavior. When insurance covers a large proportion of healthcare costs, patients may face relatively small direct payments and therefore be less sensitive to the full price of services. Deductibles, copayments, and other forms of cost sharing can increase price sensitivity. At the same time, high out-of-pocket costs may discourage people from seeking necessary care, particularly when their income is limited. Consequently, the relationship between price and healthcare utilization is more complicated than in many ordinary consumer markets.
Cultural, social, and demographic factors can also influence propensity to pay. Age, education, family responsibilities, health status, and attitudes toward medicine may affect healthcare spending decisions. Some individuals may place considerable emphasis on preventive care and wellness, while others may seek medical attention primarily when symptoms become serious. Social expectations can also influence choices, particularly when healthcare decisions involve family members or dependents.
The propensity to pay is also relevant to healthcare businesses. Providers need to understand what patients value when designing services and pricing strategies. Convenience, accessibility, personalized care, technology, and shorter waiting periods may increase the perceived value of a service. Nevertheless, healthcare organizations must balance financial considerations with ethical responsibilities. Unlike many consumer products, healthcare can involve essential services that people cannot reasonably avoid purchasing.
Overall, propensity to pay in healthcare is shaped by a combination of economic, medical, psychological, and social factors. Income and price are important, but willingness to pay also depends on perceived need, expected benefits, trust, quality, insurance coverage, and individual circumstances. Understanding these factors can help healthcare providers design accessible services and help policymakers consider how financing systems affect access to care. Ultimately, examining propensity to pay provides insight into the complex relationship between healthcare needs, financial resources, and individual decision-making.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on October 5, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
WASHINGTON (AP) — U.S. employers added a disappointing 29,000 jobs and the unemployment rate ticked up last month, the government reported Friday, a month before voters go to the polls in pivotal midterm elections at a time of discontent over the high cost of living and the state of the economy.
Hiring dropped from a revised 133,000 in August, the Labor Department said. The unemployment rate rose to a still-low 4.2% from 4.1% in August.
Economists had expected September payrolls to come in around 90,000!
Labor Department revisions also shaved 60,000 jobs off combined July and August payrolls.
The Guyton–Klinger equation, more accurately described as the Guyton–Klinger decision rules, is a set of mathematically defined withdrawal‑rate adjustments designed to guide retirees in determining how much they can safely withdraw from an investment portfolio each year. Unlike fixed‑percentage or inflation‑adjusted withdrawal strategies, the Guyton–Klinger framework introduces a dynamic system that responds to market performance. Its purpose is to preserve the longevity of a retirement portfolio while still allowing the retiree to enjoy a stable, predictable income. The “equation” is not a single formula but a set of interlocking rules that operate like a feedback system. These rules—commonly known as the inflation rule, the capital preservation rule, and the prosperity rule—form a mathematical structure that adjusts withdrawals up or down depending on portfolio conditions.
At its core, the Guyton–Klinger system begins with an initial withdrawal rate, often around 4–5 percent of the portfolio’s starting value. This initial rate is then subjected to annual adjustments based on the rules. The inflation rule governs whether the withdrawal amount should be increased to keep pace with rising prices. Unlike a simple inflation‑adjusted strategy, the Guyton–Klinger method restricts inflation adjustments during years when the portfolio has declined. This creates a built‑in stabilizer: the retiree does not automatically increase spending when the portfolio is under stress. Mathematically, this rule can be expressed as a conditional statement: if the portfolio’s real return for the year is negative, the inflation adjustment is skipped. This conditionality is the first component of the broader Guyton–Klinger equation.
The second component, the capital preservation rule, introduces a lower guardrail. It compares the current withdrawal rate—defined as the withdrawal amount divided by the portfolio’s current value—to the initial withdrawal rate. If the current rate rises too far above the initial rate, typically by more than 20 percent, the rule triggers a spending cut. This can be expressed as a ratio: if (current withdrawal ÷ portfolio value) > (initial withdrawal rate × 1.20), then the withdrawal amount is reduced by a fixed percentage, often 10 percent. This is the mathematical heart of the system: a dynamic ratio that signals when the portfolio is at risk of depletion. The rule ensures that withdrawals do not become unsustainably large relative to the shrinking portfolio.
The third component, the prosperity rule, acts as the counterpart to the capital preservation rule. When the portfolio grows significantly, the retiree is allowed to increase withdrawals. The rule is triggered when the current withdrawal rate falls below a lower guardrail—typically 20 percent below the initial rate. In mathematical terms, if (current withdrawal ÷ portfolio value) < (initial withdrawal rate × 0.80), then the withdrawal amount is increased by a fixed percentage, again often 10 percent. This rule allows retirees to enjoy the benefits of strong market performance without jeopardizing long‑term sustainability.
Together, these rules form a dynamic system that resembles a thermostat. When the portfolio overheats—meaning the withdrawal rate becomes too high relative to the portfolio’s value—the system cools spending. When the portfolio is performing well, the system allows spending to warm up. The inflation rule adds a third dimension by moderating spending increases during downturns. The interplay of these rules is what people often refer to as the “Guyton–Klinger equation,” even though it is more accurately a set of conditional equations.
One of the most important features of the Guyton–Klinger framework is that it balances two competing goals: income stability and portfolio longevity. Retirees typically want predictable income, but they also want assurance that their savings will last. Fixed‑percentage withdrawal strategies can cause income to fluctuate dramatically, while fixed‑inflation strategies can cause withdrawals to become unsustainable. The Guyton–Klinger system attempts to strike a middle ground by allowing adjustments only when necessary and by basing those adjustments on mathematically defined thresholds.
Another key aspect is that the system is forward‑looking but rule‑based. It does not attempt to predict market performance. Instead, it reacts to actual portfolio changes. This makes it adaptable across different market environments. During prolonged bull markets, the prosperity rule allows retirees to increase spending without fear of overshooting. During bear markets, the capital preservation and inflation rules work together to slow spending and protect the portfolio.
The Guyton–Klinger equation also implicitly acknowledges behavioral realities. Retirees often struggle with cutting spending, and the system’s guardrails help make those decisions objective rather than emotional. The rules provide a clear rationale for when spending must be reduced, which can make difficult adjustments easier to accept. Similarly, the prosperity rule encourages retirees to enjoy their savings when conditions allow, countering the tendency to underspend out of fear.
In summary, the Guyton–Klinger equation is a structured, mathematically grounded approach to retirement withdrawals that uses conditional rules to adjust spending based on portfolio performance. It replaces rigid withdrawal strategies with a flexible, responsive system that aims to preserve both income stability and long‑term financial security. By defining clear thresholds for when to increase or decrease withdrawals, the framework offers retirees a disciplined yet adaptable method for navigating the uncertainties of retirement finance.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
The propensity to pay is an important concept in finance that describes the likelihood and willingness of an individual, business, or organization to make a financial payment when it becomes due. It is closely related to financial behavior, creditworthiness, liquidity, and the ability to meet financial obligations. Financial institutions, businesses, and investors consider payment behavior when making decisions about lending, credit management, investment, and risk. Understanding the propensity to pay therefore helps financial decision-makers evaluate whether expected payments are likely to be made on time and in full.
In personal finance, propensity to pay can be influenced by income, employment stability, existing debt, spending habits, savings, and financial priorities. An individual with a stable income and manageable debt is generally more capable of meeting regular obligations such as loan installments, credit card balances, rent, and utility bills. However, the ability to pay does not always guarantee the willingness to pay. A person may have sufficient financial resources but choose to delay a payment because of competing priorities or expectations about future income. This distinction between ability and willingness is important when assessing financial risk.
For businesses, propensity to pay is particularly significant in managing accounts receivable and extending credit to customers. Companies frequently allow customers to purchase goods or services before making payment. While this practice can encourage sales and strengthen business relationships, it also creates the possibility of late or unpaid invoices. Businesses therefore evaluate customers’ previous payment records, financial condition, industry circumstances, and credit terms. A strong propensity to pay can support more flexible credit arrangements, whereas uncertainty about payment behavior may lead a company to require deposits, shorter payment periods, or additional security.
Banks and other financial institutions also rely heavily on payment behavior when assessing borrowers. Credit scores, repayment histories, debt-to-income ratios, and other financial information can help lenders estimate the probability that borrowers will meet their obligations. A borrower who has consistently made payments on time may be viewed as presenting less repayment risk than someone with a history of missed or late payments. These assessments influence lending decisions, interest rates, credit limits, and other terms. In this way, propensity to pay is an important component of credit risk management.
Economic conditions can also affect propensity to pay. During periods of economic growth, employment and business revenues may increase, making it easier for borrowers and customers to meet their obligations. During economic downturns, unemployment, declining sales, inflation, and higher interest rates can place pressure on household and business finances. Even financially responsible borrowers may experience difficulties when their income decreases or expenses rise unexpectedly. Consequently, financial institutions must consider broader economic conditions rather than relying solely on an individual’s or company’s past payment behavior.
Technology has made the assessment of payment propensity increasingly sophisticated. Financial institutions and businesses can analyze large amounts of transaction and credit data to identify patterns in payment behavior. Automated systems can monitor missed payments, changes in account activity, and other indicators of financial stress. These tools can improve risk assessment and allow organizations to respond more quickly to potential repayment problems. At the same time, responsible use of financial data is important because inaccurate information or inappropriate assessment methods can unfairly affect access to credit.
Propensity to pay also has implications for financial planning and business strategy. Individuals can improve their payment behavior by maintaining budgets, building emergency savings, reducing unnecessary debt, and organizing payment schedules. Businesses can improve collections by establishing clear credit policies, communicating payment expectations, monitoring outstanding invoices, and maintaining good relationships with customers. These practices can reduce financial uncertainty and improve cash flow.
In conclusion, propensity to pay is a fundamental concept in finance because it helps explain whether financial obligations are likely to be fulfilled. It reflects both the ability and willingness to make payments and is influenced by personal financial circumstances, business conditions, economic developments, and payment history. By understanding these factors, lenders, businesses, and individuals can make more informed financial decisions, manage risk, and maintain healthier financial relationships.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
One way patients can avoid medical debt is through hospital financial assistance, also known as charity care. Most of the nation’s hospitals offer free or discounted medical care to patients with very high medical debt or low incomes.
Getting financial assistance, however, can be challenging. Many patients don’t know that hospitals offer financial help, surveys show, and complex application forms leave others stymied.
Hospitals often demand that applicants turn over bank statements, pay stubs, tax returns, divorce filings, or other materials, and submit their applications in person, by mail, or by fax.
“They don’t make it easy,” said Neale Mahoney, a Stanford University economist who studies medical debt.
Such hurdles leave many patients with unpaid bills they should never have had to pay in the first place. In a single year, hospitals and health systems billed patients for at least $2 billion that they likely didn’t owe, one analysis found.
As healthcare costs climb and more people lose their coverage, states and hospitals are testing an emerging approach to fix this problem: automatically screening patients to see if they qualify for assistance and proactively wiping out debt when they do. This is known as “presumptive eligibility.”
Under this approach, patients may have the cost of their care wiped out before they see any bills — but not always. Hospitals differ on when, how, and for whom they use auto-enrollment, potentially impinging on patients’ finances.
Here’s what you need to know about how auto-enrollment works.
What is hospital financial assistance?
In many states, hospitals set their own criteria for whom they provide financial aid. Eligibility is typically based on income for the patient’s entire household. The closer patients are to poverty, the less they have to pay. Patients with middle incomes and insurance are sometimes eligible for discounts, especially if their bills would gobble up a big chunk of what they earn.
At least 11 states require hospitals to wipe out bills for low-income patients, though income cutoffs vary. Georgia, for example, mandates free care for anyone with income slightly above the federal threshold for poverty. In several states — including Oregon, North Carolina, and Maryland — patients can earn double that amount and still get free care.
But in most states, many patients must complete applications to receive assistance.
Nearly all nonprofit hospitals say they screen and automatically reduce bills for certain patients.
Under the Affordable Care Act, nonprofit hospitals must make reasonable efforts to find people who are eligible for help before they take patients to court, sell their debt to collection agencies, or ding their credit over bills. Presumptive eligibility is one way hospitals can comply with the regulation, which took effect in 2016.
In the first year under the new rules, about 70% of tax-exempt hospitals nationwide said they screened patients and proactively reduced bills, according to an analysis of federal data for Tradeoffs by the independent research institute RTI International. As of 2022, that figure was nearly 90%.
The federal law doesn’t apply to for-profit and public hospitals, which don’t have to report the actions they take before going after patients for unpaid bills.
In six states, policymakers require hospitals to use presumptive eligibility and skip applications for certain patients. Those states are California, Delaware, Illinois, Maryland, North Carolina, and Oregon.
Who is eligible to be automatically enrolled in financial assistance?
In most states, hospitals decide which patients can skip the application.
Common groups automatically screened include people who are homeless, deceased, or already enrolled in state or federal programs to help low-income households with housing, food, or prescriptions. Other hospitals have more unique criteria, like Christus Health, which will write off bills for anyone in a religious order who took a vow of poverty.
Eligibility criteria are often buried in official policies and hard to find or decipher. Some hospitals share little to no public information about whom they will proactively screen. Thirteen hospitals owned by Ascension, one of the nation’s largest Catholic health systems, state only that they may screen patients “with a sufficient unpaid balance.”
Across the half-dozen states with presumptive eligibility mandates, eligibility rules vary. Maryland, for example, requires hospitals to proactively wipe out bills only for patients who already get government help for food or utilities but are ineligible for Medicaid. In Illinois, lawmakers created less-stringent requirements for rural hospitals compared with urban facilities.
In Oregon, starting in 2024, hospitals had to screen anyone who owed more than $500 and every patient on Medicaid or who is uninsured. In 2025, roughly 80% of Oregon patients who got financial help with bills never filled out an application, based on data shared publicly by the first 26 hospitals to do so. The state’s legislature this year raised the screening threshold to include patients who owe at least $1,500 for a single visit.
***
***
Without an application, how do hospitals figure out who gets help?
Hospitals have several ways to find patients eligible for financial assistance.
Typically, hospitals turn to public records, any information patients have previously volunteered, or tools from consumer credit companies to estimate whether patients qualify to have bills reduced.
For example, if a hospital sees that a patient lives in a high-poverty ZIP code or has no address listed, that could be enough to deem them eligible. Many pay companies to run employment and credit checks on patients to determine whether they qualify for free care.
Hospitals may also consider how likely patients are to pay bills, regardless of how much they earn. This is called “propensity to pay.” California and Oregon prohibit its use, concerned that hospitals may try to collect more often from people who dutifully pay their bills even though their incomes qualify them for financial assistance.
When do hospitals screen patients for financial aid?
It depends.
Illinois, North Carolina, and Oregon require hospitals to screen certain patients before they send any bills. California hospitals will have to do the same starting in 2027.
Some hospitals voluntarily screen patients before sending bills; others try to collect money from patients first. As long as they screen patients before suing them for very overdue bills, hospitals can stay within the letter of the federal law that pushed many of them to embrace presumptive eligibility.
For example, the policy of Christus Health is to screen patients only “after all other eligibility and payment sources have been exhausted.”
Anna Stelter, vice president of policy for the Texas Hospital Association, said hospitals want to investigate other options for payment — like Medicaid or county safety net programs — before they give out financial assistance.
“We do want to make sure that whoever is financially responsible for that care is identified and pays,” Stelter said. “Charity care is the relief of last resort.”
Hospitals’ publicly posted policies may also be fuzzy about when they will screen for patients likely eligible for help. For example, Cook Children’s Health Care System in Fort Worth, Texas, says its goal is to determine a patient’s eligibility “as soon as sufficient information is available.”
Who pays the bills when patients get free care?
In one sense, we all do. Taxpayers cover some or all of the cost of financial assistance, though the amount varies by hospital.
About half the nation’s hospitals are nonprofit and legally get a pass on paying most taxes. KFF estimates that nonprofit hospitals pocketed $24 billion in 2020 that they would otherwise have paid as income, sales, or property taxes.
Government-owned and for-profit hospitals have their own sets of tax benefits to help offset costs for low-income patients. Government hospitals often get additional taxpayer support, and for-profit hospitals generally receive smaller government subsidies, like additional payments for caring for high numbers of uninsured and Medicaid patients.
Whether taxpayer dollars fully cover hospitals’ costs for financial assistance depends on the amount of government support they receive — information often not publicly available. It also hinges on how many patients need help, how many meet hospitals’ criteria for assistance, and how many get through an application. Research shows hospitals spend widely different amounts on financial assistance, from less than 1% of yearly expenses to more than 7%.
Philanthropy and hospitals’ income cover costs not absorbed by tax dollars.
This article is part of “Hidden Help,” an investigative series from Tradeoffs and KFF Health News about how hospitals can protect their patients from the life-altering harms of medical debt.
Melanie Evans is a reporter for Tradeoffs, a nonprofit newsroom reporting on healthcare’s toughest choices. Sign up for the weekly newsletter to get the latest stories every Thursday morning.
Tradeoffs’ reporting for this series was supported, in part, by the California Health Care Foundation, the National Institute for Health Care Management Foundation, and the Solutions Journalism Network.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
Your thoughts and comments on this ME-P are appreciated. Feel free to review our top-left column, and top-right sidebar materials, links, URLs and related websites, too. Then, subscribe to the ME-P. It is fast, free and secure.
Artificial intelligence (AI) has developed from a largely theoretical idea into a technology that is increasingly part of everyday life. AI systems can now understand language, recognize images, generate content, assist with scientific research, and perform complex tasks. As these systems become more capable, researchers and society are beginning to consider a possible future transition from artificial intelligence to artificial superintelligence. This development could transform human civilization, creating extraordinary opportunities while also raising serious questions about safety, control, and responsibility.
Artificial intelligence refers to computer systems designed to perform tasks that normally require human intelligence. These tasks include learning from information, solving problems, understanding language, recognizing patterns, and making decisions. Modern AI can already perform some tasks at a level comparable to or beyond humans. However, most existing AI systems remain specialized or limited in important ways. They depend on human-designed objectives, training data, computing resources, and environments in which they operate.
The concept of artificial general intelligence (AGI) describes a potential future system with broad intellectual abilities. Rather than being designed for one particular task, an AGI would theoretically be able to learn and perform a wide range of intellectual activities. It could potentially transfer knowledge between different subjects, adapt to unfamiliar problems, and improve its abilities through experience. Whether and when AGI will be achieved remains uncertain, and there is no universally accepted definition or test for it.
Artificial superintelligence represents a further hypothetical stage. It generally refers to an AI system whose intellectual capabilities substantially exceed those of humans across most or all areas of cognitive activity. Such a system could potentially conduct scientific research, develop technologies, analyze enormous amounts of information, and solve problems far more rapidly than individual humans or existing institutions. If achieved, superintelligence could accelerate progress in areas such as medicine, energy, transportation, education, and scientific discovery.
At the same time, the development of increasingly powerful AI could create significant challenges. One concern is the problem of ensuring that highly capable systems reliably pursue goals that are consistent with human intentions and values. A system that is extremely capable but misunderstands its objectives could produce harmful consequences even without intending to cause harm. Other concerns include cybersecurity, economic disruption, concentration of technological power, privacy, misinformation, and the possibility that advanced AI could be used irresponsibly by individuals or organizations.
The transition from AI to superintelligence should therefore not be viewed simply as a race to create increasingly powerful machines. It also involves developing methods for testing, monitoring, controlling, and governing advanced systems. Researchers are exploring areas such as AI alignment, interpretability, robustness, evaluation, and safety. Governments, businesses, researchers, and the public may all have roles in determining how increasingly powerful AI technologies are developed and used.
Ultimately, the path from artificial intelligence to superintelligence is uncertain. Some experts believe highly advanced systems could emerge relatively soon, while others believe major technical challenges remain. Regardless of the timeline, the possibility deserves careful consideration. AI has the potential to expand human capabilities enormously, but realizing its benefits will require thoughtful development and responsible decision-making. The central challenge is not simply creating machines that become more intelligent, but ensuring that increasing technological power contributes to human well-being and remains subject to appropriate human oversight.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on September 30, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
The ER Billed Her Anyway
By Michelle Andrews
September 29th, 2026
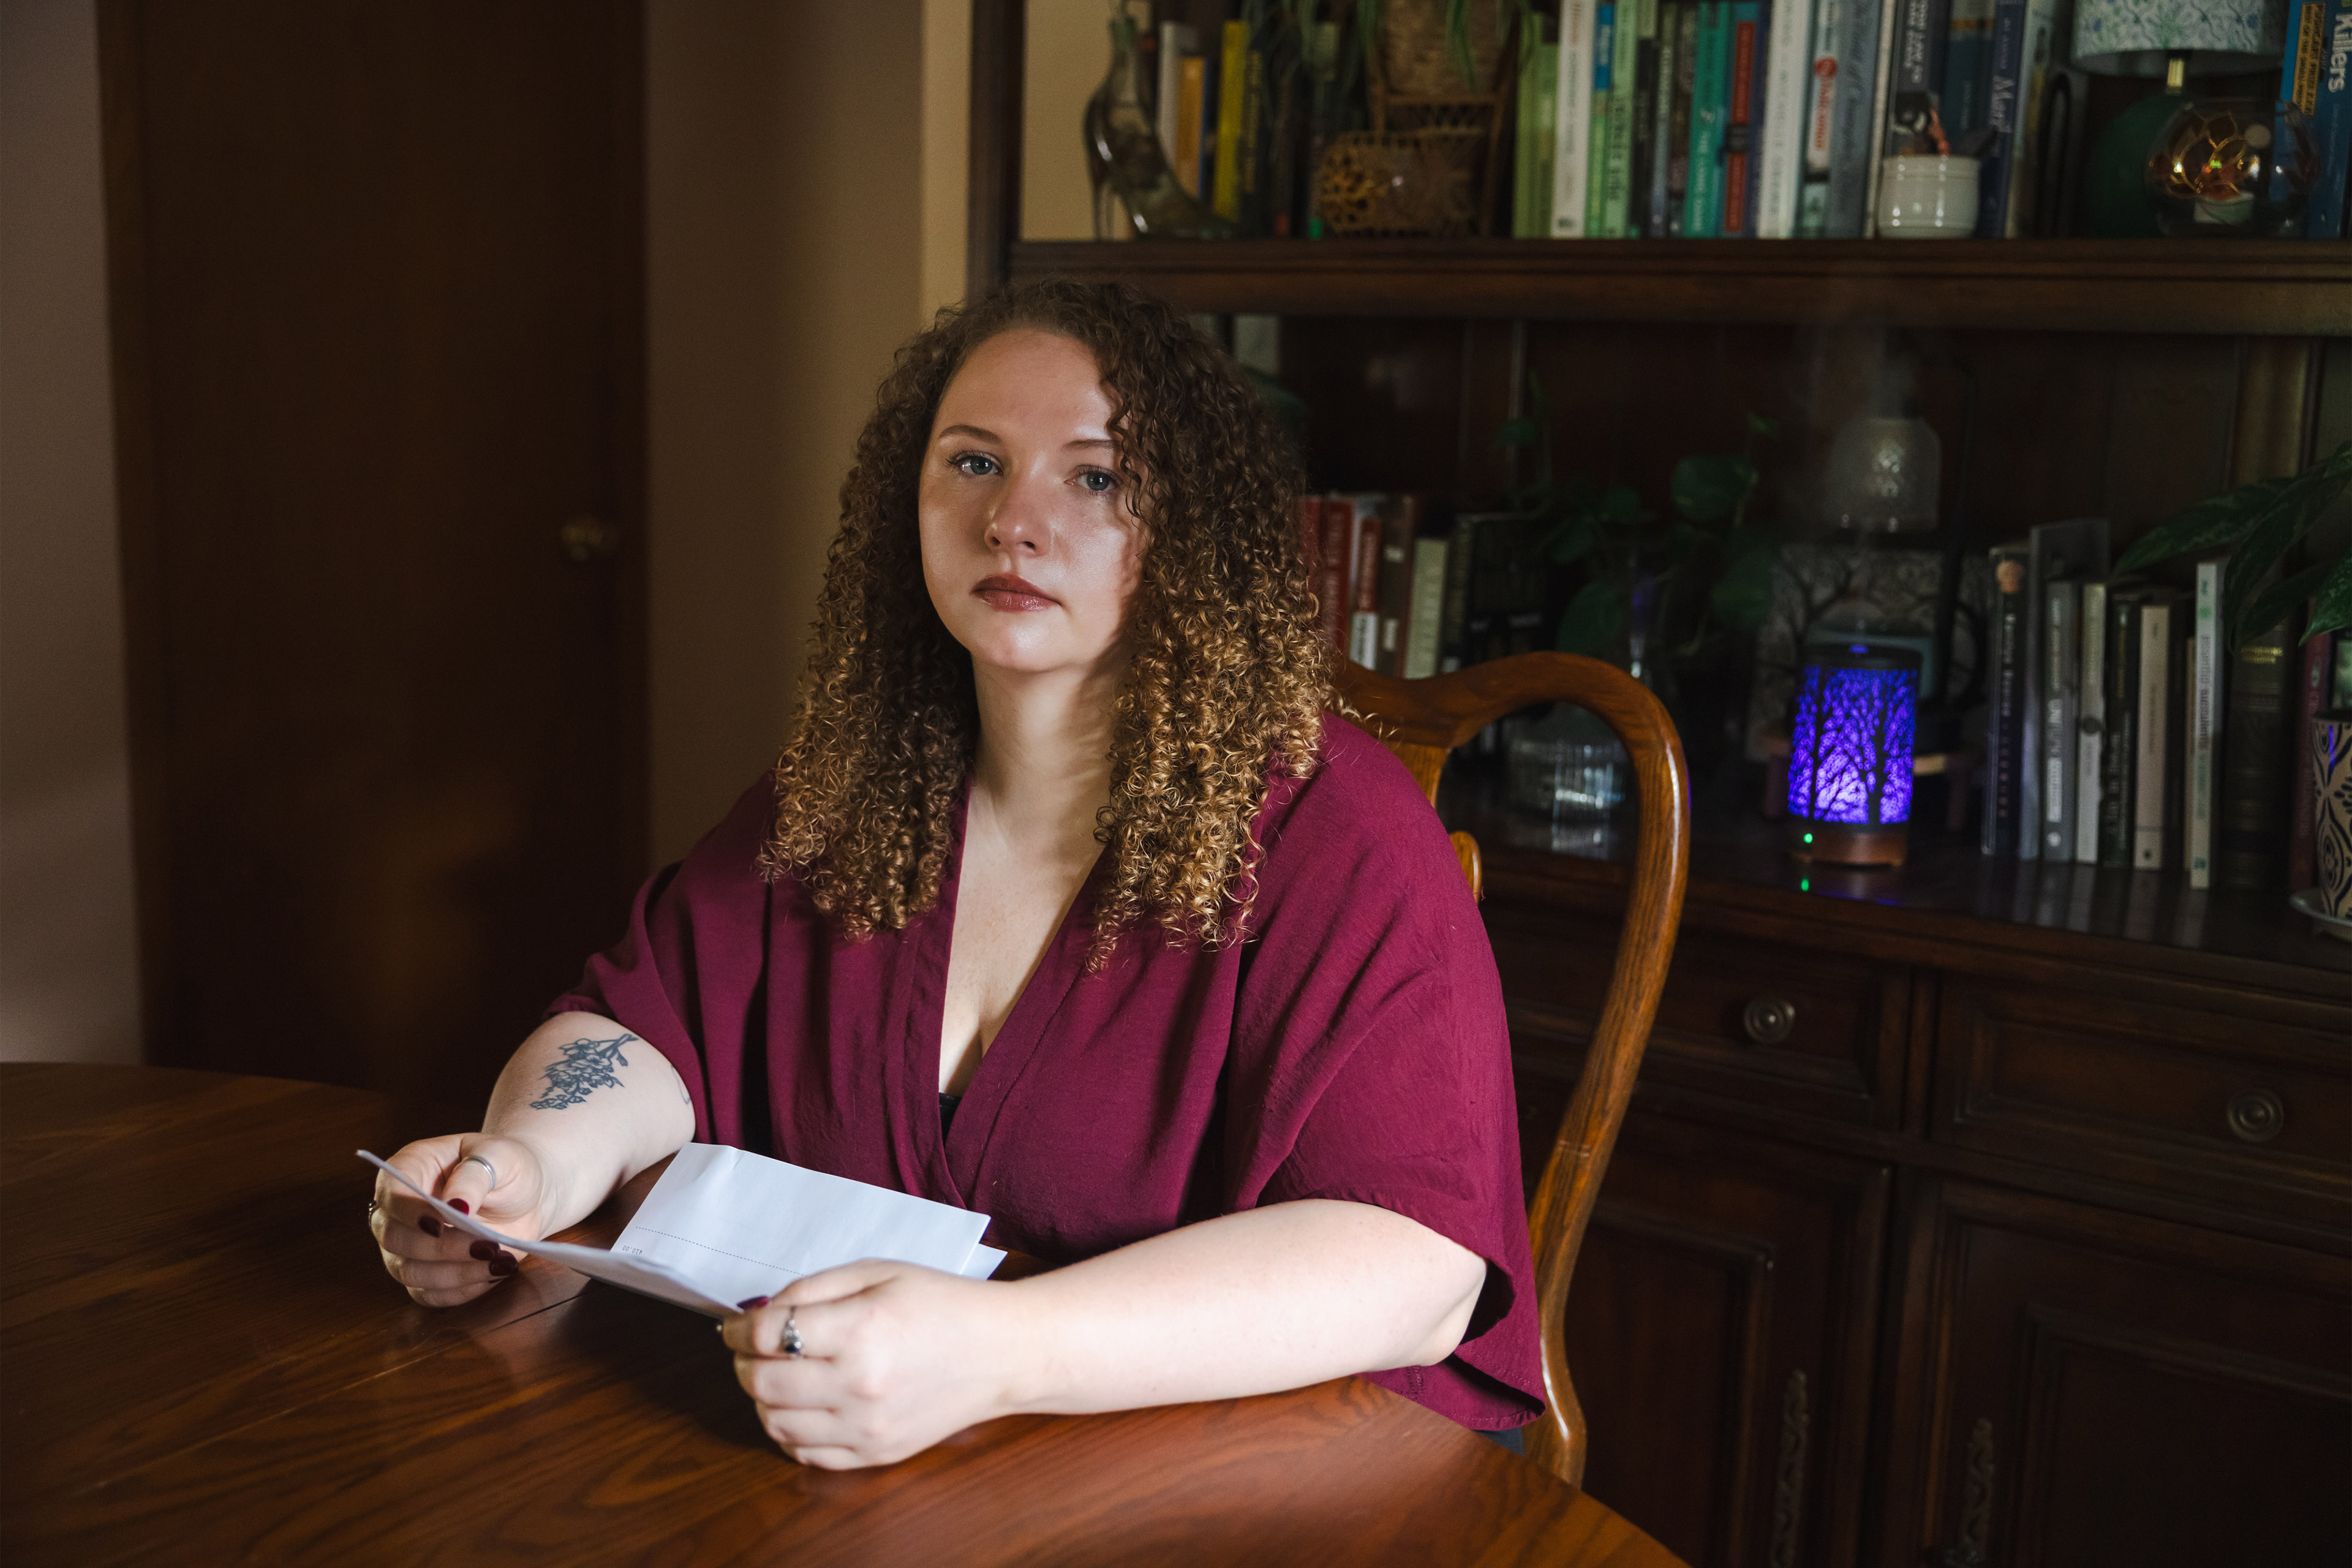
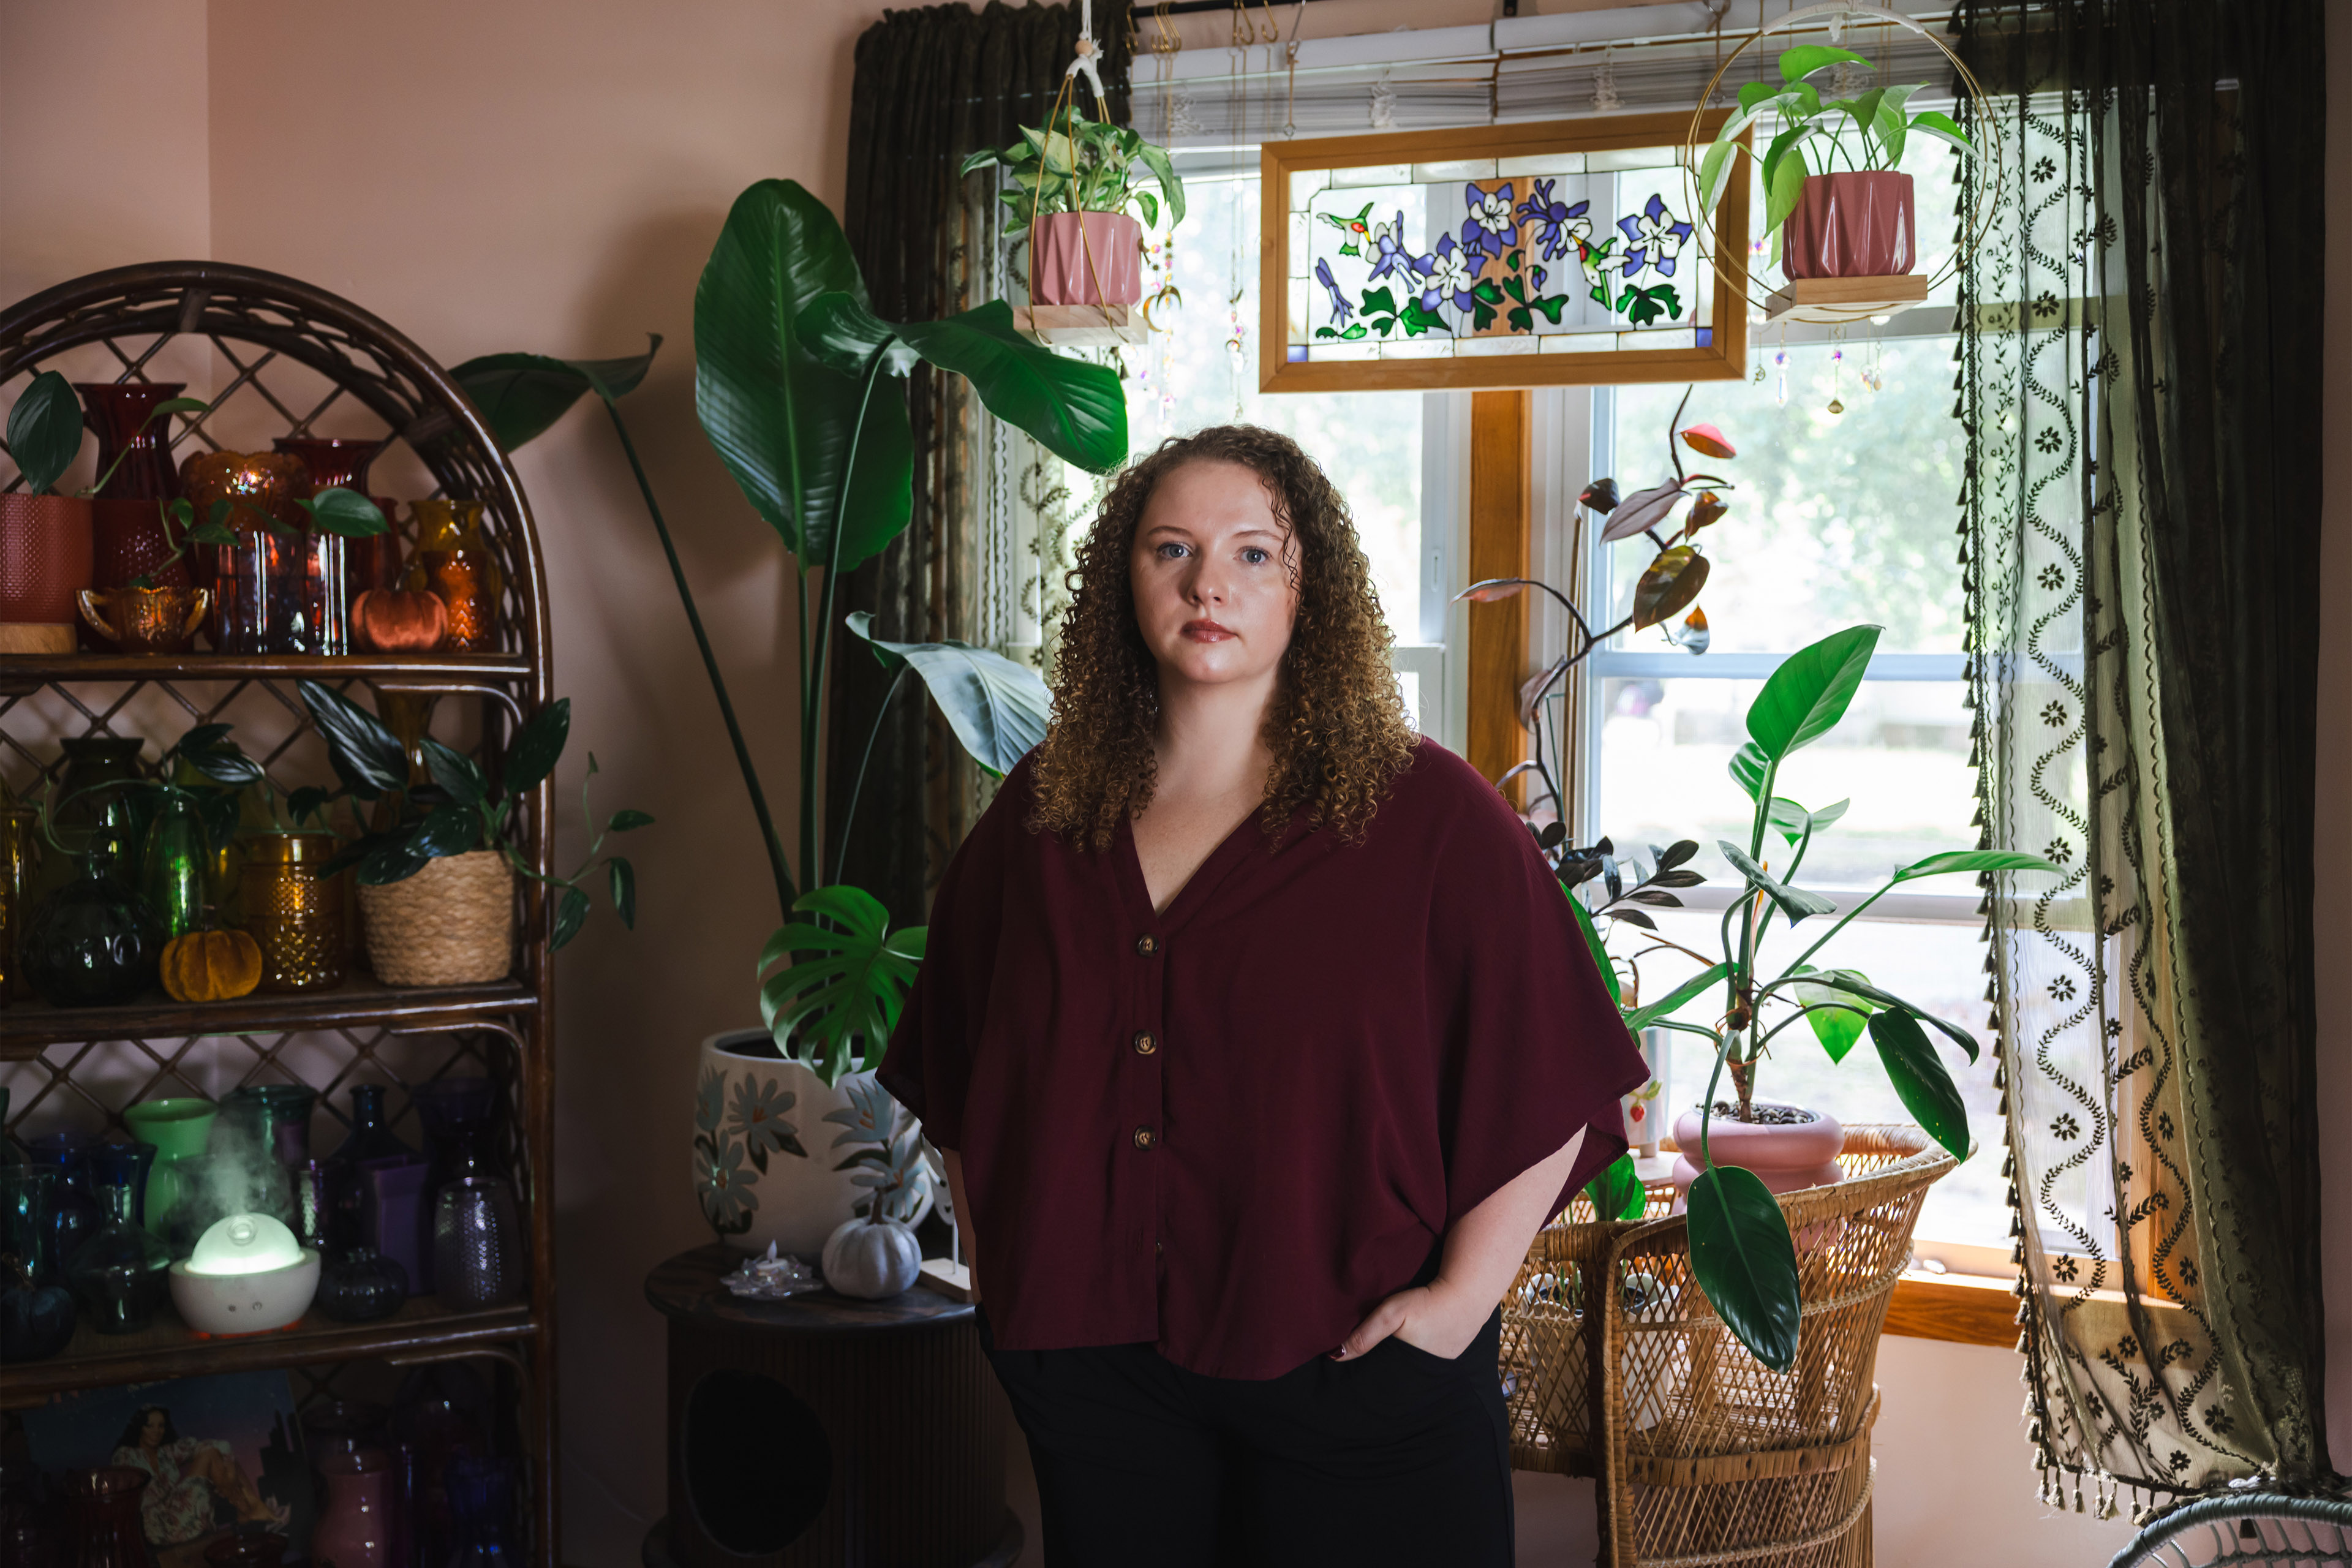
After hospital staffers checked her vital signs, Autumn Daniels spent four hours in the waiting room before her sister took her to another hospital. She still got a bill from the ER for $410. (Taylor Glascock for KFF Health News)
Autumn Daniels is no stranger to migraine headaches, which have troubled her since childhood.
The migraine tormenting the 32-year-old in April was even worse than usual. After a week of piercing head pain, she went to an urgent care center near her home in Champaign, Illinois, and received an injection of Toradol, a non-steroidal anti-inflammatory drug that usually helps with her symptoms. The doctor at the clinic told her that if the pain didn’t improve, she should go to an emergency room the next day.
It didn’t improve. So the next morning, Daniels’ sister took her to a nearby ER, at Carle Foundation Hospital in Urbana. She said the ER didn’t seem very busy when she registered at the front desk and was taken briefly to an exam room, where a staffer checked her vital signs and asked whether she had migraines frequently. Then they told her to sit in the waiting room until she was called.
She and her sister waited. And waited. By then, Daniels said, she was vomiting every 10 minutes, a not-uncommon occurrence during one of her serious migraine attacks.
After four hours, with no indication that Daniels would be seen anytime soon, her sister took her to another hospital. There, after a wait of about an hour and a half, Daniels was seen and received treatment, including more Toradol and anti-nausea medication.
Having left Carle without getting treatment, Daniels didn’t expect to be charged.
Then the bill came.
The Medical Service
Daniels said a staffer checked her pulse, temperature, and blood pressure when she arrived at Carle. She said she received no other services, nor was she seen by a doctor.
At one point while they sat in the waiting room, Daniels said, her sister asked for an ice pack for her head, but the staff wouldn’t provide one.
“ER triage is driven by risk of death or serious harm, not by level of suffering,” said Jennifer Robblee, a neurologist at the Barrow Neurological Institute in Phoenix and a board member at the Association of Migraine Disorders. “Migraine patients without red flags are unlikely to be prioritized, as they are not at immediate risk of dying.”
The Bill
$410 for an “Emergency Room Level 1” visit. Daniels said she requested an itemized bill showing how the hospital arrived at that figure but never received one.
This is not the first time that a patient has complained to KFF Health News’ “Bill of the Month” about receiving a bill after leaving a Carle Health emergency room without being treated. In 2023, Maggi Wettstein took her toddler to a different Carle Health hospital and was billed $445 for a nasal swab test for covid and influenza. They, too, left before getting treatment.
The Billing Problem: What Counts as Care?
Though Daniels left the emergency room after a four-hour wait without being treated, the hospital billed her anyway. Her health plan, provided through her job as a state employee, paid for her treatment at the second hospital but denied the Carle claim, leaving her on the hook for the charges.
“Under the terms of her health plan, claims associated with a patient leaving the facility against medical advice are not eligible for coverage,” Leslie Porras, a spokesperson for HealthLink, which administers Daniels’ plan, said in a statement.
When Daniels asked about her bill, a Carle representative responded in an email that said: “Effective March 1, 2026, Emergency Department visits may result in charges even if you are not seen directly by a provider. When you arrive at the Emergency Department, your visit begins as soon as care is initiated.”
The email said “care” could mean registration and nursing assessment, in addition to diagnostic testing and treatment. It said that even if patients leave without being seen by a provider, they may still be charged, because the hospital is using resources to maintain its staff, space, and equipment.
Carle Health declined to discuss Daniels’ bill or her care with KFF Health News, even though Daniels signed a privacy waiver that authorized it to do so.
Daniels was not expecting to be charged after leaving an emergency room without receiving treatment. But a health system representative later told her an ER visit begins “as soon as care is initiated,” which could mean when the patient registers at the front desk and is assessed for triage purposes. (Taylor Glascock for KFF Health News)
In a statement, Carle Health spokesperson Brittany Simon said, “Our Emergency Department has consistent billing practices for triage care,” referring to the process through which patients are evaluated to ensure the most critical cases are treated first.
“Carle Health takes patient concerns seriously and supports transparency in our billing processes,” she said.
Typically, an ER bill would include separate dollar amounts for physician charges and hospital charges, said Amber Padron, assistant director of case management at the Patient Advocate Foundation, a nonprofit that assists patients with chronic or life-threatening conditions.
Daniels’ bill listed a single charge, for $410. Under the description, it said “Emergency Room Level 1” and included the current procedural terminology code “99281.” CPT codes are used to bill for evaluation and management, or E/M, services provided by a medical professional. Level 1 is the lowest level of emergency care.
But there’s a catch: According to the American Medical Association’s CPT guide, “Triage alone is not an E/M service; therefore, it cannot be reported with an E/M code.”
It gets murkier. According to Robert Mills, a spokesperson for the AMA, the physician charge for an emergency visit under that CPT code would generally be significantly less than $410.
“It is likely the hospital consolidated the provider-billed charge with a facility fee,” Mills said, referring to a fee that hospitals tack onto bills to cover their overhead costs, such as utilities.
Amid the billing uncertainty, Daniels is clear about one thing: The decision to charge ER patients who leave without getting treatment is recent.
In 2025, she went to the same emergency room with gastrointestinal problems. After waiting for several hours, she went elsewhere for care. She said that before leaving, her mother, who accompanied her that day, confirmed with the front desk that Daniels wouldn’t be charged if they left then. And she wasn’t.
“So when I went in for this visit in April, I had no idea I was going to be charged, because it was a very similar set of circumstances,” Daniels said.
The health system didn’t respond to a question about why it changed its policy.
The Resolution
Carle didn’t budge. According to the health system’s email to Daniels, “the charges have been determined to be accurate and fully supported by the medical record documentation.”
Daniels said she paid $25 of the $410 bill and has applied for financial assistance.
Meanwhile, according to HealthLink’s statement to KFF Health News, Daniels can contest her health plan’s denial: “Ms. Daniels has the right to appeal the decision through the established appeals process.”
She’s considering it, but she remains outraged about what happened.
“How is it ethical or even legal for a hospital to essentially bill for occupying a waiting room?” she asked.
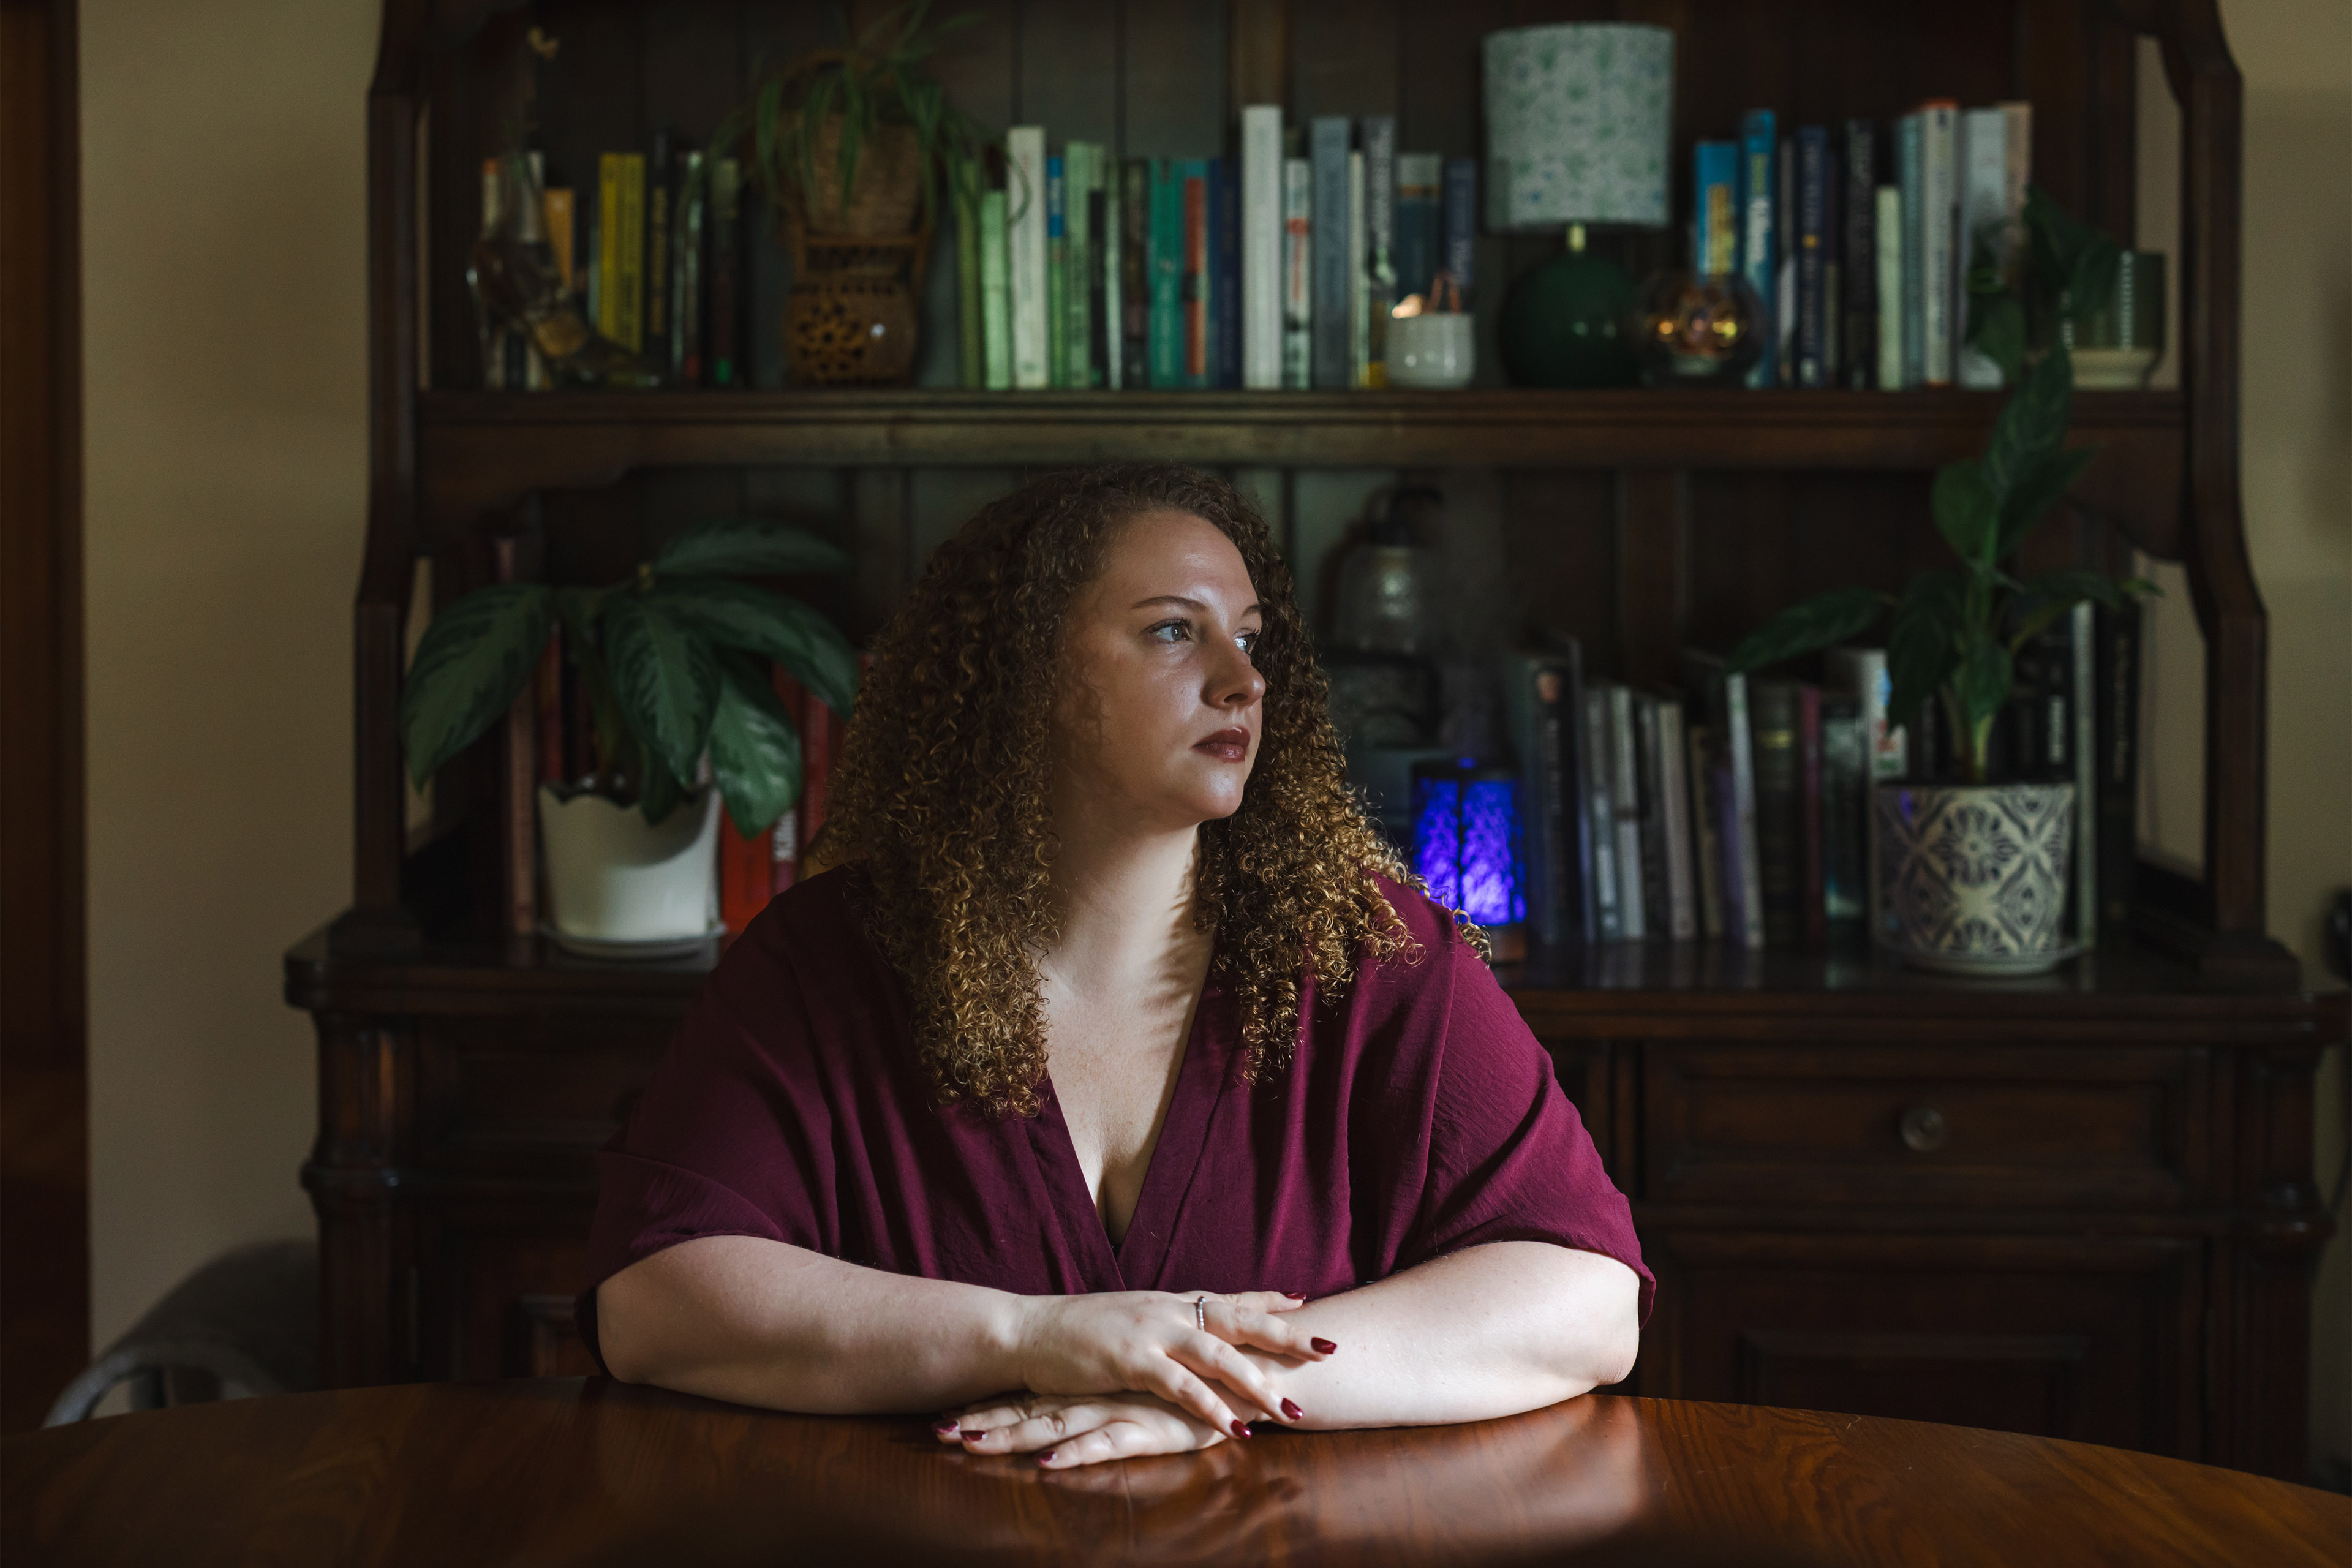
Daniels is considering contesting her health plan’s denial of coverage for the ER bill: “How is it ethical or even legal for a hospital to essentially bill for occupying a waiting room?” (Taylor Glascock for KFF Health News)
The Takeaway
Don’t assume you won’t be billed if you leave a hospital before receiving medical care. You can check with the front desk about the facility’s policy, as well as ask your insurer whether it provides coverage for such bills.
If the hospital billing department isn’t giving you information about what services you’re being billed for, request your medical records, said Padron, of the Patient Advocate Foundation.
Furthermore, when your health plan processes a claim, you should receive an explanation of benefits informing you of that and explaining what you may owe. Keep an eye on your mail and your insurance portal.
When a claim is denied, filing an appeal with your health plan is always a smart idea, Padron said.
“It’s always going to be a no if you don’t appeal,” she said.
Bill of the Month is a crowdsourced investigation by KFF Health News and The Washington Post’s Well+Being that dissects and explains medical bills. Since 2018, this series has helped many patients and readers get their medical bills reduced, and it has been cited in statehouses, at the U.S. Capitol, and at the White House. Do you have a confusing or outrageous medical bill you want to share? Tell us about it!
KFF Health News is a national newsroom that produces in-depth journalism about health issues and is one of the core operating programs at KFF—an independent source of health policy research, polling, and journalism. Learn more about KFF.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
The 7 percent rule for retirement is a simple withdrawal strategy that suggests retirees can withdraw 7 percent of their total retirement savings in the first year of retirement, then adjust that annual withdrawal amount each year to keep pace with inflation. For instance, with $1 million in retirement accounts. This strategy allows you to withdraw $70,000 in year one, increasing that amount slightly each year as the cost of living rises.
Unlike the more conservative 4 percent rule, which is grounded in decades of research and testing through historical market data, the 7 percent rule is considered more aggressive. It appeals to those who want to enjoy a higher standard of living in their early retirement years or those who have a higher risk tolerance.
However, this higher withdrawal rate requires careful planning and may not suit most retirees.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Healthcare will not reform itself because the forces that shape it—economic incentives, institutional inertia, political fragmentation, and cultural expectations—push it toward preserving the status quo rather than transforming it. The system is too complex, too profitable for certain stakeholders, and too politically sensitive to spontaneously reorganize into something more efficient, humane, or affordable. Any meaningful change requires coordinated action, and healthcare is built in a way that prevents coordination from ever happening naturally.
The core problem is incentives. Every major player in healthcare benefits more from maintaining the current structure than from changing it. Hospitals earn revenue from procedures, admissions, and billing complexity. Insurers profit from managing risk, not eliminating it. Pharmaceutical companies thrive on high prices and long patent protections. Even many physicians, through fee‑for‑service models, are rewarded for volume rather than outcomes. When every stakeholder is financially rewarded for the system as it exists, reform becomes economically irrational. No industry voluntarily restructures itself in ways that reduce revenue, and healthcare is no exception.
Institutional inertia reinforces this resistance. Healthcare is a massive ecosystem with deeply entrenched processes, legacy technologies, and regulatory frameworks that have accumulated over decades. Changing any one part requires changing many others, and the interdependencies make reform feel like rewiring an airplane mid‑flight. Hospitals rely on outdated electronic record systems because replacing them is disruptive and expensive. Insurers cling to complex billing codes because they are woven into every administrative workflow. Medical education still emphasizes specialization and acute care because that is how the system has operated for generations. Institutions do not reform themselves when the cost of change feels greater than the cost of dysfunction.
Political fragmentation adds another layer of immobility. Healthcare in the United States is not a single system—it is a patchwork of federal programs, state regulations, private insurers, employer‑based coverage, and individual market rules. Reform requires alignment across federal agencies, state governments, Congress, private companies, and professional associations. That alignment almost never occurs. Political parties disagree on the role of government, states resist federal mandates, and powerful lobbying groups influence legislation to protect their interests. Even when reform is proposed, it is typically watered down, delayed, or blocked entirely. A fragmented system cannot reform itself because no single entity has the authority or incentive to lead the transformation.
***
***
Cultural expectations also play a role. Americans expect unlimited choice, cutting‑edge treatments, and immediate access to specialists. They want the best technology, the newest drugs, and the most advanced procedures. These expectations drive demand for high‑cost care and discourage reforms that emphasize prevention, primary care, or cost control. A system built around consumer expectations of “more” will not voluntarily shift toward “less but smarter.” Cultural pressure keeps the system oriented toward high‑intensity, high‑cost medicine, even when simpler approaches would produce better outcomes.
Another barrier is the sheer profitability of inefficiency. Administrative complexity—often criticized as waste—is a revenue source for many organizations. Billing departments, claims processors, coding specialists, and compliance teams exist because the system is complicated. Simplifying healthcare would eliminate entire categories of jobs and shrink entire industries. No system willingly reforms in ways that eliminate its own workforce. Complexity persists because it pays.
Even innovation struggles to drive reform. New technologies, such as telemedicine, AI diagnostics, and value‑based care models, promise efficiency and better outcomes. But they are often absorbed into the existing structure rather than transforming it. Telemedicine becomes another billable service. AI tools are layered onto old workflows instead of replacing them. Value‑based care programs are implemented as pilot projects rather than systemic shifts. Innovation cannot reform a system that continually reshapes new ideas to fit old incentives.
***
***
Finally, healthcare will not reform itself because the people most harmed by the system—patients—have the least power to change it. Individuals cannot negotiate prices, redesign insurance networks, or restructure hospital systems. They experience the consequences but cannot influence the architecture. A system in which the beneficiaries of dysfunction hold the power and the victims hold none will never reform from within.
In the end, healthcare is structurally designed to resist change. Its incentives reward the status quo, its institutions fear disruption, its politics prevent coordination, its culture demands high‑cost care, and its complexity protects entrenched interests. Reform requires external pressure—legislative action, public demand, or economic crisis. Without those forces, healthcare will continue operating exactly as it does now, not because it works well, but because it works well enough for the people who control it.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on September 27, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
How Corporate Ownership Is Reshaping Medical Practices
Corporate ownership is influencing how physicians practice. Among the key findings from the 2026 PAI Employed Physician Survey of 1,003 employed physicians is that 82 percent of physicians are now employed by hospitals or other corporate entities. Furthermore, most employed physicians feel pressure to put their employer’s priorities ahead of what they believe is best for patients.
B.F. Skinner’s perspective on medicine focused on applying operant conditioning and behavioral analysis to medical adherence, treatment compliance, and psychiatric therapy rather than relying solely on internal medical models.
Core Ideas on Medicine and Health
Medical Adherence: Skinner’s framework explains that failing to take prescription drugs or follow a treatment plan is driven by environmental variables and reinforcement contingencies, not personal failure or “forgetfulness”.
Behavioral Pharmacology: His experimental methods demonstrated that drug effects on behavior are schedule-dependent, meaning they interact directly with environmental determinants.
Psychiatric Therapy: Applied behavior analysis used positive reinforcement principles pioneered by Skinner to help psychiatric inpatients and shape clinical interventions in medical settings.
Critique of Medicalization: Behaviorism challenges the tendency to reduce complex human actions and societal problems strictly to internal physical or mental diseases.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Zero-sum economics is the idea that one person’s or group’s economic gain must come at the expense of another’s. In a zero-sum situation, the total amount available is fixed. If one participant receives more, another participant necessarily receives less. The concept is useful for understanding certain economic conflicts, but it does not accurately describe the economy as a whole.
The term “zero-sum” comes from the idea of a fixed pool of resources. For example, imagine two people dividing ten dollars between themselves. If one person receives seven dollars, the other can receive only three. The total remains ten dollars. This is a zero-sum situation because the gains and losses exactly offset one another. Many economic activities can have zero-sum characteristics, particularly when participants are competing for a scarce and fixed resource.
Competition for land can provide a simple example. If two businesses want to purchase the same piece of property and only one can obtain it, the successful buyer gains control of the property while the other loses the opportunity to use it. Similarly, when governments negotiate over a fixed amount of a natural resource, gaining a larger share may leave less available for others. In these circumstances, thinking in zero-sum terms can help explain why disagreements occur.
However, much of economic activity is not inherently zero-sum. Economies can grow because people create new goods and services, develop technologies, improve productivity, and exchange resources in ways that benefit multiple parties. When a farmer grows more food because of better equipment, for example, the total amount of food available can increase. When a company develops a useful new product, consumers may receive something they value while the company earns revenue. Both sides can benefit from the transaction.
Trade is another important example. Two people may voluntarily exchange goods because each values what the other possesses more highly. A person who has extra vegetables might exchange them for clothing made by someone else. After the exchange, both participants may consider themselves better off. The transaction has not simply transferred a fixed amount of wealth from one person to another; it has created value through specialization and exchange.
Economic growth therefore challenges the assumption that wealth is a fixed quantity. Productivity improvements can allow societies to produce more with the same amount of labor and resources. Education can increase workers’ skills, while technological innovation can make production faster and less expensive. Investment in infrastructure can also make it easier for businesses and individuals to produce and exchange goods. These processes can expand the overall economic possibilities available to society.
Nevertheless, scarcity remains an important limitation. Resources such as land, time, energy, and certain raw materials are finite. Even in a growing economy, people and governments must make choices about how these resources are used. Choosing to devote more resources to one purpose can mean devoting fewer resources to another. For instance, a government that spends more money on transportation may have fewer resources available for other programs unless it increases revenue or reduces other spending.
***
***
The zero-sum perspective can also influence political and social debates about inequality. If people believe that economic gains are always obtained at someone else’s expense, they may view differences in wealth primarily as evidence of direct competition between groups. Sometimes economic outcomes do involve distributional conflicts, particularly when policies determine who receives a fixed benefit or bears a particular cost. At other times, however, the economy may be capable of generating additional wealth, making the central issue how that new wealth is distributed rather than whether one group must lose for another to gain.
Understanding the difference between zero-sum and positive-sum situations is therefore important. A zero-sum framework is appropriate when participants are dividing a genuinely fixed resource. It becomes less useful when applied to activities that increase production, encourage innovation, or create mutual gains through voluntary exchange. Economic life contains both types of situations.
Ultimately, zero-sum economics provides a valuable way of thinking about scarcity and competition, but it should not be treated as a complete description of economic activity. Some conflicts involve competing claims over limited resources, while other activities expand the amount of wealth and opportunity available. Recognizing the difference allows economic issues to be understood more clearly and helps explain why some situations require choices about distribution while others allow people to create mutual benefits.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Transformational leadership is a leadership approach that focuses on inspiring individuals to achieve meaningful goals while encouraging personal growth, innovation, and positive change. Unlike traditional leadership styles that may rely heavily on rules, rewards, or authority, transformational leadership emphasizes motivation, vision, trust, and shared values. Transformational leaders seek not only to accomplish organizational objectives but also to develop the people they lead. This approach is widely relevant in businesses, educational institutions, healthcare organizations, and community settings because it can help organizations adapt to change and encourage individuals to reach their full potential.
One of the most important characteristics of transformational leadership is the ability to create and communicate a clear vision. A transformational leader gives people a sense of purpose by explaining what the organization hopes to achieve and why those goals matter. Instead of simply telling employees what tasks they must complete, the leader connects everyday responsibilities to a larger purpose. When people understand how their contributions affect the overall organization, they may become more committed and motivated. A strong vision can also provide direction during periods of uncertainty and change.
Another important element of transformational leadership is inspiration. Transformational leaders encourage people to challenge themselves and believe that improvement is possible. They often demonstrate enthusiasm, confidence, and commitment to organizational goals. Their behavior can influence employees to become more engaged in their work. However, inspiration is not simply about giving motivational speeches. Effective transformational leaders demonstrate the values and behaviors they expect from others. By acting with integrity, responsibility, and dedication, they can establish credibility and encourage others to follow their example.
***
***
Transformational leadership also places significant emphasis on intellectual stimulation. Leaders using this approach encourage employees to think creatively, question existing practices, and develop new solutions to problems. Rather than assuming that established procedures are always the best, transformational leaders create an environment in which people can offer ideas and explore alternative approaches. This can be especially valuable in organizations facing technological developments, changing customer expectations, or competitive pressures. Allowing employees to participate in problem-solving can also increase their sense of responsibility and involvement.
Individualized consideration is another central feature of transformational leadership. Transformational leaders recognize that employees have different abilities, experiences, interests, and professional goals. Instead of treating everyone in exactly the same way, they provide guidance and support according to individual needs. This may involve mentoring an employee, providing constructive feedback, offering opportunities for professional development, or helping someone overcome a challenge. By investing in individual development, leaders can strengthen both employee capabilities and organizational performance.
Transformational leadership can have several benefits for organizations. It can contribute to higher levels of employee engagement, teamwork, creativity, and commitment. Employees who feel respected and valued may be more willing to contribute ideas and take initiative. The approach can also help organizations respond to change because employees are encouraged to think beyond established routines. Furthermore, developing employees can create a stronger pool of future leaders, helping organizations maintain continuity as responsibilities change.
Despite its advantages, transformational leadership also has limitations. A strong emphasis on vision and change can sometimes create unrealistic expectations if leaders do not provide sufficient resources, planning, and support. Leaders may also become overly focused on organizational goals and unintentionally overlook practical concerns faced by employees. In addition, transformational leadership depends heavily on trust and credibility. If a leader communicates an inspiring vision but fails to demonstrate the behaviors necessary to achieve it, employees may become skeptical. Therefore, transformational leadership should be supported by effective communication, realistic planning, accountability, and attention to employee well-being.
In conclusion, transformational leadership is an approach that seeks to create positive change by motivating people, communicating a meaningful vision, encouraging innovation, and supporting individual development. Its emphasis on inspiration and personal growth distinguishes it from leadership approaches based primarily on authority or external rewards. When practiced effectively, transformational leadership can help individuals and organizations adapt, learn, and pursue shared objectives. Ultimately, successful transformational leadership is not simply about leading people toward a particular goal; it is about helping people understand the purpose behind that goal, develop their abilities, and become active participants in achieving meaningful organizational change.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Spendthrift syndrome refers to a persistent pattern of excessive, impulsive, or poorly controlled spending that harms a person’s financial stability and emotional well-being. Although the term is often used casually to describe someone who enjoys shopping, the problem becomes serious when spending repeatedly exceeds income, creates debt, or causes conflict with family members. It is not simply a matter of being irresponsible. For many people, overspending is connected to emotions, habits, social pressure, and difficulty delaying gratification.
A person with spendthrift tendencies may buy items they do not need, shop to relieve stress, or feel compelled to make purchases after seeing advertisements and online promotions. Modern technology can make this behavior easier. Shopping apps, saved payment information, one-click ordering, and buy-now-pay-later plans reduce the time available to reconsider a purchase. Social media also encourages comparison by presenting expensive lifestyles as normal or desirable. As a result, some individuals feel pressure to spend money in order to appear successful, fashionable, or accepted.
Emotional factors often play an important role. Shopping can provide a brief sense of excitement, control, or comfort, especially during periods of sadness, anxiety, loneliness, or boredom. However, this relief is usually temporary. Once the purchase is made, the person may feel guilt, regret, or fear about bills and debt. Those unpleasant feelings can then trigger more spending as a way to escape them, creating a damaging cycle. Over time, financial stress may affect sleep, relationships, work performance, and self-esteem.
The consequences of uncontrolled spending can be severe. Credit-card balances may grow, savings may disappear, and important expenses such as rent, food, health care, or education may be neglected. In families, overspending can lead to arguments and loss of trust, particularly when purchases are hidden from a partner or when shared money is used without agreement. Young adults may be especially vulnerable because they are still learning budgeting skills while also facing advertising and easy access to credit.
Addressing spendthrift syndrome requires honesty and practical planning. A useful first step is tracking every purchase for several weeks. This helps identify patterns, such as shopping late at night, spending after stressful events, or making frequent small purchases that add up. Creating a realistic budget can also give money a clear purpose. Essential bills, savings, and debt payments should be prioritized before discretionary spending. Limiting access to credit cards, deleting shopping apps, and waiting twenty-four hours before nonessential purchases can reduce impulsive decisions.
Support from others can be valuable as well. A trusted friend or family member may help someone remain accountable to financial goals. If spending feels impossible to control or is closely linked to depression, anxiety, or other emotional struggles, speaking with a financial counselor or mental-health professional may be appropriate. The goal is not to eliminate enjoyment or treat every purchase as a mistake. Instead, it is to develop a healthier relationship with money—one based on choice, planning, and long-term security rather than temporary emotional relief.
Spendthrift syndrome shows that money habits are often connected to deeper personal and social influences. Recognizing the problem without shame is essential. With awareness, boundaries, and support, individuals can regain control of their finances and make spending decisions that better reflect their needs, values, and future goals.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on September 22, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
First Day of Autumn 2026
Astronomical Autumn
Date: September 22, 2026
Time: 8:05 p.m. EDT (5:05 p.m. PDT, 00:05 UTC on September 23)
Significance: This date marks the autumnal equinox, when day and night are approximately equal in length.
Meteorological Autumn
Start Date: September 1, 2026
Duration: September, October, and November
Purpose: This definition divides the year into four seasons of three months each, making it easier for meteorologists to track climate patterns.
Summary of Definitions
Definition
Start Date
Duration
Astronomical
September 22
Until Winter Solstice (Dec 21)
Meteorological
September 1
September to November
Both definitions are correct but serve different purposes. Astronomical autumn is based on the position of the Earth relative to the Sun, while meteorological autumn is based on calendar months.
The financial services industry has historically been defined by physical spaces, from the bustling, chaotic trading floors of Wall Street to the imposing stone architecture of retail banks.
However, the digital revolution quietly dismantled these physical structures, replacing them with abstract algorithms, complex spreadsheets, and glowing flat screens. While this transition maximized operational efficiency, it stripped away the intuitive, spatial, and collaborative elements of human decision-making. Enter Virtual Reality (VR): an immersive technology that is no longer confined to the realms of gaming and entertainment. Today, VR is emerging as a powerful, transformative tool in finance, fundamentally altering how data is visualized, how global teams collaborate, and how institutions interact with their clients.
At the core of finance lies data—massive, fast-moving, and multidimensional data. For decades, analysts and portfolio managers have relied on traditional two-dimensional monitors to track market trends, risk variables, and asset correlations. This approach creates a cognitive bottleneck, as humans must mentally stitch flat charts together to understand complex market ecosystems. Virtual reality shatters this limitation by translating abstract numbers into immersive three-dimensional landscapes. In a VR environment, an entire investment portfolio can be visualized as a living corporate city. The height of a building might represent an asset’s market capitalization, its color could dictate real-time price fluctuations, and its proximity to other structures could visualize risk correlation. By stepping inside their data, financial professionals can utilize natural spatial awareness to spot anomalies, recognize structural patterns, and assess systemic risk far more quickly than would be possible scrolling through thousands of spreadsheet rows.
Beyond sophisticated data analysis, virtual reality is redefining collaboration within global financial institutions. The modern financial sector relies on seamless communication between decentralized teams scattered across New York, London, Tokyo, and beyond. Traditional video conferencing, while functional, lacks the nuance of shared physical presence and limits real-time collaborative modeling. VR bridges this geographic divide through virtual trading floors and immersive boardrooms. Equipped with VR headsets, traders and executives from around the world can gather as avatars in a singular digital workspace. They can collectively manipulate 3D data models, simulate macroeconomic scenarios, and execute complex strategies simultaneously. This level of immersion reproduces the high-energy, spontaneous collaboration of legacy trading pits while maintaining the precision and compliance of automated digital systems.
Simultaneously, VR is transforming the consumer-facing side of finance by reinventing retail banking and wealth management. As physical bank branches continue to close due to rising operational costs, institutions risk losing personal connections with their customers. VR provides a compelling middle ground by enabling virtual bank branches. Clients can step into a digital branch from the comfort of their living rooms to meet face-to-face with a financial advisor. This is particularly impactful for wealth management and financial planning. Instead of reviewing static retirement projections on a piece of paper, clients can view interactive, immersive timelines of their financial futures. An advisor can visually demonstrate how shifting savings rates or market downturns will alter a client’s long-term lifestyle goals, making abstract financial planning tangible and emotionally resonant.
Furthermore, the technology plays an increasingly vital role in institutional training and onboarding. The compliance-heavy, high-stakes nature of finance means that mistakes are exceptionally costly. VR offers a risk-free sandbox environment where junior traders, compliance officers, and customer service representatives can sharpen their skills. Trainees can be dropped into high-pressure scenarios, such as a simulated market crash or a volatile client confrontation, allowing them to build muscle memory, emotional resilience, and split-second decision-making capabilities without risking a single dollar of institutional capital.
In conclusion, virtual reality is evolving from a novel tech gimmick into a foundational pillar of modern financial infrastructure. By humanizing complex data, dismantling geographic barriers to collaboration, restoring personal touch to digital banking, and optimizing professional training, VR addresses the modern limitations of a purely flat digital economy. As hardware becomes more accessible and processing power continues to scale, the institutions that successfully integrate spatial computing into their daily workflows will capture a distinct competitive edge. The future of finance is no longer bound to a screen; it is an immersive environment waiting to be explored.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Artificial intelligence is transforming nursing by enhancing clinical decision-making, improving patient outcomes, and streamlining workflows, while also raising ethical and professional considerations.
***
***
Enhancing Clinical Decision-Making
AI technologies, including machine learning and predictive algorithms, are increasingly used to support nurses in clinical decision-making. Tools such as clinical decision support systems can analyze large datasets from electronic health records (EHRs), laboratory results, and patient-reported outcomes to identify patterns, predict risks, and suggest interventions with greater accuracy than manual methods. Examples include fall risk prediction, sepsis detection, and prevention of catheter-associated infections, which help nurses make timely, evidence-based decisions and reduce human error in patient care.
Improving Patient Outcomes
By integrating AI into nursing practice, healthcare providers can deliver more personalized and precise care. AI can synthesize data from multiple sources to create a holistic view of a patient’s health, enabling tailored treatment plans and early interventions. This capability supports better health outcomes, enhances patient safety, and allows nurses to focus on complex, hands-on care that requires human judgment and empathy.
Streamlining Nursing Workflows
AI also contributes to operational efficiency in nursing. Automated data analysis, predictive alerts, and mobile health applications reduce the time nurses spend on routine tasks, allowing them to prioritize direct patient care. AI-driven tools can optimize staffing, monitor patient acuity, and assist in scheduling, which helps alleviate workload pressures and mitigate burnout among nursing staff.
***
***
Ethical and Professional Considerations
While AI offers significant benefits, it also raises ethical and professional challenges. Nurses must critically evaluate AI tools to ensure they align with patient-centered care, uphold safety, and avoid unintended harm, particularly for vulnerable populations. The American Nurses Association emphasizes that nurses should question the assumptions behind AI technologies and advocate for ethical implementation that reflects nursing values. Concerns include potential overreliance on algorithms, corporate-driven priorities that may conflict with patient care, and the risk of undermining clinical judgment if AI is improperly applied.
Role of Nurses in AI Integration
Nurses play a crucial role in the development, implementation, and evaluation of AI in healthcare. Their expertise ensures that AI tools are practical, safe, and enhance rather than replace the human aspects of care. Active involvement in AI design and policy-making helps maintain the balance between technological efficiency and the holistic, hands-on approach essential to nursing practice.
Conclusion
AI is reshaping nursing by providing advanced tools for decision-making, patient monitoring, and workflow management, ultimately improving care quality and efficiency. However, its integration must be guided by ethical principles, professional judgment, and active nurse participation to ensure that technology complements rather than compromises patient-centered care.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
B.F. Skinner was a psychologist rather than an economist, but his principles of environmental conditioning helped shape the foundation of modern behavioral economics.
Operant Conditioning and Choice
Reinforcement: Skinner proved that actions followed by rewards happen more often. In economics, this explains why consumers buy items on sale or investors chase rising stock prices.
Punishment: Costs or negative outcomes make actions happen less often. Taxes and fines use this exact idea to reduce specific behaviors.
Environmental Control: Skinner believed environments control choices, opposing traditional economic views that focus purely on internal, rational math.
Token Economies
Incentives: Skinner created token systems where people earn tokens for good actions and trade them later for real rewards.
Modern Parallels: This system directly mirrors modern loyalty points, credit card cash-back rewards, and corporate bonus structures.
Behavior Analysis vs. Behavioral Economics
Internal vs. External: Behavioral economists study internal mental thoughts and biases. Skinner’s behavior analysis ignores internal thoughts and focuses only on external rewards and history.
Market View: Some analysts argue that long-term central bank actions condition investors to expect bailouts, acting as a massive economic reinforcement schedule.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Virtual reality (VR) is fundamentally altering how economists visualize data, simulate market behavior, and train the future workforce. Long confined to the realms of gaming and entertainment, immersive technology has emerged as a powerful tool for understanding complex economic systems.
By transforming abstract theoretical frameworks into tangible, interactive environments, virtual reality bridges the gap between mathematical modeling and human behavior. As global economies become increasingly digitalized, the integration of VR into economics offers unprecedented opportunities for experimental research, consumer analysis, and macroeconomic forecasting.
At its core, economics relies on the study of how individuals make choices under conditions of scarcity. Traditional economic experiments often struggle to replicate the messy reality of human decision-making, forcing researchers to rely on simplified lab settings or retrospective survey data. Virtual reality completely changes this dynamic by allowing researchers to construct highly controlled, hyper-realistic experimental environments. In a virtual storefront, for example, economists can manipulate subtle variables—such as the layout of products, the behavior of virtual bystanders, or real-time price fluctuations—to observe authentic consumer reactions. Because participants experience a genuine sense of presence, their choices mirror real-world behavioral economic patterns much more accurately than responses to a hypothetical questionnaire. This high degree of experimental control combined with ecological validity provides policymakers and businesses with deeper, data-driven insights into consumer psychology and market anomalies.
Beyond microeconomic experiments, virtual reality serves as a revolutionary mechanism for data visualization. Modern economic data is incredibly vast, high-dimensional, and difficult to conceptualize through traditional two-dimensional charts or spreadsheets. Using VR data spaces, analysts can literally walk through complex datasets, observing multidimensional clusters of inflation rates, employment statistics, and supply chain bottlenecks simultaneously. By mapping data points as physical objects in a 3D environment, anomalies and correlations that were previously obscured by the sheer volume of text become instantly recognizable. This spatial interaction allows central banks, corporate leaders, and financial institutions to grasp macroeconomic trends more intuitively, leading to faster, more robust policy decisions during times of financial instability.
***
***
Furthermore, virtual reality is rewriting the rules of labor economics and workplace productivity. The technology enables immersive remote collaboration, allowing global teams to work together in shared virtual spaces without the logistical costs, time constraints, or environmental impacts of physical travel. In terms of human capital development, VR drastically lowers the marginal cost of high-skill job training. Medical students can practice complex surgeries, engineers can test expensive industrial equipment, and retail workers can experience high-stress scenario management all within a zero-risk virtual simulation. By reducing the physical capital required for education and minimizing training accidents, VR accelerates skill acquisition, boosts structural productivity, and shifts the long-run aggregate supply curve outward.
However, the widespread adoption of virtual reality also introduces novel economic challenges that theorists must navigate. As digital assets, virtual real estate, and immersive commerce continue to expand, they create entirely new digital economies. These virtual ecosystems require their own regulatory frameworks, property rights enforcement, and taxation strategies. Central banks may eventually need to consider how virtual currencies and transactions impact broader monetary policy and inflation metrics in the physical world. Additionally, unequal access to premium VR hardware could exacerbate the digital divide, creating disparities in education and employment opportunities that reinforce existing socio-economic inequalities.
In conclusion, virtual reality is no longer a futuristic novelty; it is a transformative economic catalyst. By providing a playground for realistic behavioral experimentation and offering intuitive ways to navigate massive datasets, VR enhances our understanding of financial systems. Simultaneously, its capacity to optimize labor training and remote work promises to drive tangible productivity gains in the real world. As economists and policymakers adapt to this immersive frontier, they must balance the immense analytical and productive benefits of virtual reality against the regulatory and ethical hurdles of a dual physical-digital economy. Ultimately, those who master the virtual landscape will hold the keys to navigating the complex economic realities of tomorrow.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
The Evolution and Impact of Micropayments in the Digital Economy
The internet was originally designed to facilitate the free and seamless exchange of information, but it lacked a built-in mechanism for exchanging small amounts of value. As the digital landscape matured, content creators, developers, and service providers found themselves in a perpetual struggle to monetize their work without alienating users.
For decades, the dominant solutions were subscription models and intrusive digital advertising. However, subscriptions demand an upfront commitment that casual consumers are often unwilling to make, while advertisements clutter user interfaces and compromise privacy. To bridge this gap, the concept of micropayments emerged. Generally defined as financial transactions involving very small sums of money—often ranging from a fraction of a cent to a few dollars—micropayments are fundamentally reshaping how value is transferred, consumed, and appreciated in the modern digital economy.
The underlying infrastructure supporting micropayments has undergone a massive transformation. Historically, traditional financial networks like credit cards and bank wires were entirely unsuited for micro-transactions. The fixed processing fees associated with standard credit card transactions could easily exceed the total value of a fifty-cent payment, making the model economically unviable. To circumvent these high friction costs, early digital platforms relied on centralized aggregation models. Companies like Apple, through the iTunes ecosystem, aggregated small digital purchases into single, larger bills. In recent years, however, technological breakthroughs have introduced decentralized networks and layer-2 blockchain solutions, such as the Bitcoin Lightning Network. These innovations allow for near-instantaneous transactions with practically negligible fees, finally unlocking the true technological potential of peer-to-peer micro-billing.
The most profound impact of micropayments is felt in the realm of digital journalism and creative content creation. Under the current paradigm, internet users frequently encounter hard paywalls that demand monthly or annual subscriptions just to read a single article. This “subscription fatigue” restricts access to information and hurts publishers who lose casual readers. Micropayments offer an elegant alternative by introducing a pay-per-article or pay-per-minute model. A reader can seamlessly authorize a payment of five cents to read an insightful editorial, allowing them to curate their media consumption across dozens of platforms without committing to a single one. This empowers independent creators, bloggers, and musicians to directly monetize their niche audiences, shifting the economic power away from massive media conglomerates back to individual artists.
Beyond traditional media, micropayments are a foundational element of the rapidly expanding gaming and software-as-a-service (SaaS) industries. In modern gaming, the “free-to-play” model relies entirely on microtransactions. Players download games at no cost but routinely spend small sums on virtual cosmetics, extra lives, or character upgrades. While this model has faced criticism regarding predatory design, it undeniably demonstrates the immense consumer willingness to engage in small, frictionless purchases. In software engineering and cloud computing, micropayments allow users to pay precisely for the resources they utilize. Instead of paying a steep monthly fee for an artificial intelligence tool, a developer can pay a hundredth of a cent for every line of code generated, creating a highly efficient, utility-based pricing environment.
***
***
Despite the obvious benefits, the widespread adoption of micropayments faces notable psychological and technical hurdles. Chief among these is the “cognitive transaction cost.” Behavioral economics shows that every time a consumer must decide whether or not to spend money—even a trivial sum—it triggers a micro-moment of mental stress and hesitation. If a user has to actively approve every five-cent transaction while browsing a website, the resulting decision fatigue ruins the browsing experience. To overcome this barrier, modern systems utilize automated, pre-authorized wallets that stream fractions of a cent in the background as a user scrolls through a webpage or listens to a podcast, removing the conscious burden of payment execution.
Looking forward, micropayments are poised to serve as the economic backbone of the emerging Machine-to-Machine (M2M) economy and the Internet of Things (IoT). In an interconnected world, smart devices will need to transact with one another autonomously. For instance, an electric vehicle could automatically stream micropayments to a smart toll road or a charging station while driving, or a smart weather sensor could sell localized atmospheric data to a meteorological agency for a fraction of a penny per second. By providing a highly scalable, low-cost method to transfer tiny amounts of wealth, micropayments are quietly transforming the internet from a network of free information into a hyper-efficient, liquid marketplace for global digital value.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on September 16, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
WASHINGTON (AP) — The Federal Reserve just raised its benchmark interest rate Wednesday for the first time since 2023 in an effort to quell stubbornly-high inflation, a move that could spur a sharp response from the White House.
The quarter-point increase lifts the Fed’s key rate to about 3.9% and, over time, could result in higher borrowing costs for mortgages, auto loans, and credit cards. In a set of quarterly projections, the Fed also signaled that its rate-setting committee expects to hike rates a second time later this year to 4.1%.
“Today’s policy action will support a timelier return” to the central bank’s 2% inflation goal, the Fed said in a statement.
Economic theories are structured frameworks—such as classical, Keynesian, supply and demand, and neoclassical—that explains how economies function, how resources are allocated, and how markets behave.
What is Economic Theory
Economic theory provides concepts, principles, and models to analyze how societies produce, distribute, and consume goods and services. It helps explain phenomena like price changes, market behavior, and economic growth, and guides policymakers in addressing issues such as inflation and unemployment.
Major Branches
Microeconomic Theory: Focuses on individuals, firms, markets, and decision-making.
Macroeconomic Theory: Examines aggregate indicators such as national income, fiscal policy, inflation, and unemployment.
Key Economic Theories
1. Classical Economic Theory
Key Thinkers: Adam Smith, David Ricardo, and Thomas Malthus.
Core Idea: Markets self-regulate through the “invisible hand,” promoting efficient resource allocation with minimal government intervention.
2. Keynesian Economic Theory
Key Thinker: John Maynard Keynes.
Core Idea: Demand drives economic activity; government intervention is necessary during recessions to stabilize the economy.
3. Supply and Demand Theory
Explains price determination through equilibrium where quantity demanded equals quantity supplied.
4. Neoclassical Economics
Focuses on rational choice, utility maximization, and market equilibrium.
5. Marxian Economics
Analyzes capitalism through class struggle, labor value, and exploitation.
6. Monetarism
Emphasizes the role of monetary policy and control of the money supply in managing economic stability.
7. New Classical & New Keynesian Economics
New Classical: Advocates rational expectations and market-clearing models.
New Keynesian: Incorporates price stickiness and supports policy intervention.
Schools of Economic Thought
Economic theories are often grouped into schools such as classical, Marxian, neoclassical, Keynesian, and heterodox approaches. Modern mainstream economics includes micro and macro branches, with distinctions like saltwater vs. freshwater economists in the U.S.
Economic theories continue to evolve, shaping how economists interpret markets, forecast trends, and design policy solutions.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
A cognitive scientist studies how the mind works—covering perception, memory, language, reasoning, and decision‑making—using interdisciplinary methods from psychology, neuroscience, linguistics, computer science, and philosophy.
What a Cognitive Scientist Does
Investigates mental processes such as perception, memory, attention, language, and problem‑solving.
Builds computational or theoretical models of how the mind represents and processes information. conducts experiments. (behavioral, computational, or neuroimaging) to test hypotheses about cognition.
Applies findings to fields like AI, education, human‑computer interaction, and decision science.
Interdisciplinary Foundations
Cognitive science integrates:
Psychology — experimental methods for studying behavior and mental processes. Neuroscience — brain imaging (fMRI, EEG) to link cognition to neural activity.
Linguistics — structure and processing of language.
Computer Science & AI — computational models of thought and intelligent systems.
Philosophy — foundational questions about mind, consciousness, and knowledge.
Typical Research Questions
How does the brain construct perception from sensory input?
How do humans learn, store, and retrieve knowledge?
How is language acquired and processed?
How are decisions made under uncertainty?
How do emotions and social context shape thinking?
Methods Used
Behavioral experiments.
Eye‑tracking.
EEG, fMRI, MEG.
Computational modeling.
Virtual reality and field studies.
Career Paths
Cognitive scientists work in:
Academia — research and teaching.
Industry — AI, UX research, neurotechnology, human‑factors engineering.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on September 14, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
By Dr. David Edward Marcinko; MBA MEd
***
***
Diagnostics and Imaging: AI algorithms analyze foot scans, X-rays, MRIs, and gait patterns to detect early signs of conditions such as plantar fasciitis, bunions, diabetic foot complications, fractures, and joint degeneration. These tools can identify subtle abnormalities that may be missed by the human eye, enabling timely intervention and reducing the risk of severe complications.
Predictive Analytics: AI can forecast the likelihood of foot-related complications, particularly in high-risk patients like those with diabetes. By analyzing historical and real-time data, AI helps podiatrists anticipate issues such as diabetic foot ulcers and implement preventive care strategies.
Personalized Treatment Plans: AI-driven systems integrate patient medical history, lifestyle, and foot health data to create customized treatment strategies. This ensures that interventions are tailored to individual needs, improving the effectiveness of care.
Gait Analysis and Biomechanics: AI tools track movement patterns, detect abnormalities, and recommend corrective measures. This is especially beneficial for athletes, patients with mobility issues, and those recovering from injuries.
Orthotic Design: AI-generated 3D models allow for the creation of custom orthotics and insoles that precisely fit a patient’s foot structure, enhancing comfort and therapeutic outcomes.
Workflow and Practice Efficiency
Administrative Support: AI-powered platforms assist with appointment scheduling, patient reminders, and follow-ups, reducing no-show rates and administrative burden.
Clinical Documentation: AI-driven dictation and natural language processing tools enable podiatrists to record clinical notes directly into electronic health records, saving time and reducing documentation fatigue.
Patient Engagement: AI facilitates digital-first experiences, including self-scheduling, two-way communication, and real-time monitoring, which enhances patient satisfaction and adherence to treatment plans.
Benefits and Challenges
Benefits: AI improves diagnostic accuracy, enables early intervention, personalizes care, predicts complications, and optimizes clinic operations. It complements the podiatrist’s expertise rather than replacing it, allowing clinicians to focus more on patient interaction and complex decision-making.
Challenges: Integrating AI requires addressing data privacy, regulatory compliance, technology adoption, and staff training. Ensuring accurate AI outputs and maintaining patient trust are also critical considerations.
Future Outlook
AI is expected to continue evolving in podiatry, with advancements in machine learning, computer vision, and predictive analytics further enhancing patient care. As adoption grows, AI will likely become an indispensable tool for both large and small podiatric practices, improving outcomes while maintaining efficiency.
Posted on September 14, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
August 2026 U.S. CPI Inflation Numbers
In August 2026, the U.S. Consumer Price Index rose 0.4% month‑over‑month and 3.4% year‑over‑year, while core CPI increased 0.3% monthly and 2.4% annually.
Key figures
Headline CPI (MoM): +0.4% (forecast: 0.4%)
Headline CPI (YoY): +3.4% (unchanged from July)
Core CPI (MoM): +0.3% (forecast: 0.2%)
Core CPI (YoY): +2.4% (unchanged from July).
Drivers of the change
Energy: Gasoline prices jumped 3.9%, accounting for over one‑third of the monthly CPI gain; the energy index rose 2.1% and was up 16.3% YoY.
Food: Overall food prices rose 0.1% MoM; food at home was flat, while food away from home increased 0.3%.
Shelter: Shelter costs rose 0.3% MoM.
Other services: Transportation services up 0.5% MoM.
Market and policy context
The August report was the final major inflation data point before the Fed’s September policy meeting. While headline and annual rates matched expectations, the core CPI monthly gain was faster than forecast, prompting traders to raise odds of a quarter‑point Fed rate hike . The 2‑year Treasury yield rose to ~4.61% and FedWatch odds for a hike approached 90%.
Summary: August’s CPI showed a modest monthly acceleration driven largely by energy, with underlying inflation (core) also picking up. Annual inflation held steady at 3.4%, but the core monthly rate’s surprise uptick kept pressure on the Fed to consider tightening.
Classic Definition: Describes a pattern in which people engage in a healthy behavior but then counteract its benefits by choosing an unhealthy one.
Modern Circumstance: This tendency emerges from a psychological process known as self‑licensing, where a virtuous action creates a sense of moral credit. Once individuals feel they have “earned” a reward, they may permit themselves to indulge in behaviors that undermine their original effort.
Paradox Example: Someone who completes a strenuous workout may later justify eating a high‑calorie dessert, believing the exercise offsets the indulgence. Although both actions make sense in isolation, together they can cancel each other out, slowing progress toward health goals.
Paradox Example: People drive safe cars more aggressively
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Statutory interest is a type of interest imposed by law to compensate a creditor or party deprived of timely payment. It applies when payments are overdue, such as in commercial transactions, government repayments, or court judgments, and serves both as a remedy for the affected party and a deterrent against late payments Unlike contractual interest, which is agreed upon between parties, statutory interest is set by legislation or regulation and may vary depending on jurisdiction and the type of debt.
Legal Basis
The legal foundation for statutory interest comes from statutes such as the Late Payment of Commercial Debts (Interest) Act 1998 in the UK, the Prompt Payment Act in the U.S., or other relevant national laws These laws define:
When interest begins to accrue (e.g., after the due date or a specified grace period).
The applicable interest rate (often a fixed rate plus a benchmark rate like the Bank of England base rate).
The method of calculation (typically simple interest). For example, in UK business-to-business transactions, statutory interest is 8% plus the Bank of England base rate for late payments.
Calculation
Statutory interest is generally calculated using the formula: Interest = Principal × Rate × (Days Late / 365) Where:
Principal is the overdue amount
Rate is the statutory interest rate expressed annually
Days Late is the number of days the payment is overdue Interest accrues from the day after the payment was due until it is fully paid or legally recovered.
Practical Applications
Commercial transactions: Businesses can claim statutory interest on late payments for goods or services.
Government repayments: Tax authorities or public bodies may pay statutory interest on late refunds or overpayments.
Court judgments: Courts may award statutory interest on sums owed under judgments.
Statutory interest ensures fairness by compensating for the time value of money and encouraging timely payments, complementing contractual agreements when no specific interest terms are set.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
So, what is money? Money is elusive. It seems to demand so much from us. Not only does it seem utterly convoluted and alien, it is also bafflingly personal. In between, we find complex monetary systems, multi-national legalisms; a whole host of political and cultural mythologies, our most profound personal issues and another zillion nuances that go into generating “the money forces.” Then, as if to heap insult upon injury, the art of money demands competency with your own personal intangibles.
Money has strong spiritual and religious components. Indeed, our relationship with money goes straight to our souls. Getting it, keeping it and spending it all precisely reflect our values, morals and motivations. Some believe money has its origins in religious rituals. Others believe that the love of money is at the root of all evil. Either way, it is no accident that the money issue is the second most frequently addressed topic in the Christian Bible and is clearly a part of most major religious traditions. It has that kind of power in our lives.
What’s more, money itself has much else in common with religion. Despite pretentious banalities decrying money as either secular creed or an unworthy recipient of thoughtful attention by right thinking people, and in spite of trite condemnations of its hold on our value systems, the baseline fact is that money is a belief system with all the qualities and characteristics that generally attend belief systems. It has only the values, functions and meanings we collectively give it. No more. No less. It is myth at its best.
It also grounds humanity’s best attempts to take care of its individuals while rationally allocating goods and services. Perfection? Hardly. Yet still the best system we know for delivering life’s necessities to the broadest possible group of living souls.
One may suggest the following to be financial axioms of our age:
Money is the most powerful secular force on the planet.
Money skills are quite literally 21st century survival skills.
Money skills do not come with our DNA.
Therefore, this may lead to multiple conclusions that heads directly core realities. If these observations are true and can be taken together as working presuppositions for life in the 21st century, well, you know, money is just plain powerful. Our lives will go better if we have a grip on it.
Money skills come in many forms and are much more than mere technical proficiency. In fact, some money skills are simple coping mechanisms such as balancing creditors and cash flow, understanding insurance needs or grasping the rudiments of our legal system.
Others include an ability to deal with the array of money systems that have evolved in response to complex economies including relevant bureaucracies. Also, an appreciation for history and social evolution is useful. At the very least, such an appreciation will enhance your coping skills. Much about our economic systems does not make much sense if taken in isolation.
Money has been evolving for the thousands of years. It has been an integral part of civilization. It enables the marketplace. It is easy to become cynical about money, but without it, our systems grind to a halt. This includes our healthcare systems.
Money underscores the purpose of this chapter. Its work is grounded in these beliefs and the attendant exploration of their ramifications for individual lives. In doing this work, our discussion will range from the philosophical to the intensely personal. Be forewarned, this chapter will not teach you how to get rich so much as it might, hopefully, help you live richly. To derive maximum benefit, it is imperative that you bring a willingness to look into yourself as well as the world around you.
We are too easily daunted by money. Some of our fears are justified but there are whole ranges of skill that are resolved by simply understanding some basics. For all the mysteries and myths woven around money, truly crucial money skills are easily accessible to individuals. At the level required for 21st century survival, money skills are not particularly complex. If you don’t have them, you can generally rent them or associate with them.
The simple fact is that if you have read the entirety of this book, you have been exposed to just about all there is to know about financial planning fundamentals, and some practice management benchmarks. If you have not found it between these covers, most of what is left is just a phone call, or couple of browser clicks away.
***
***
Don’t misunderstand. There are certain financial and managerial issues that are incredibly complex, that deserve years of schooling, should only be used in the hands of the most skillful, and truly merits our awe and admiration. This is comparable to those times when sophisticated surgical invasion is required. Sometimes it does the trick perfectly. But you don’t do heart surgery to cure a cold and you do not necessarily need complex solutions to your financial problems. Be careful out there.
This will undoubtedly get us into some philosophical trouble, but we plead with you to understand the simple realities of the financial services and medical consulting industry. There are some great people in it. Nonetheless, in the wonderful world of personal finance and practice management, what others make complex often simply covers sales motives, crude politics or some other form of pocketbook invasion. Or, it may be an attempt to make someone appear sophisticated. Or, it might possibly be simply an intellectual version of the old shell game, betting neither you nor a team of auditors could find the pea that has been so magnificently shuffled. Reducing gimmicks to essential components is a worthy skill. Never investing in something you do not understand is simply fundamental intelligence. If you don’t “get it,” please accept the possibility that it may not be you. Hold off. Even if you “get it,” it is still a good idea to “get” the seller’s motives. There is a difference between paranoid and prudent, but even paranoids reduce their odds of getting mugged if their fear helps them stick to safer paths.
Yet, these and other basics are pure financial muscle. Whole industries are built around them and getting around them.
True sophistication comes with tailoring your money and practice to you. Imagine what you would know if you had completely absorbed the information contained herein. You could have learned to build; staff and plan for your medical business. You might have received an overview of various taxation systems and miscellaneous methods for best working with their demands. You could now be comfortably crunching numbers, multiplying, adding, subtracting and dividing with the best of them. In the meantime, you have been exposed to investments, estate planning, insurance, “retirement” planning, and so forth. You could have been absorbing details, possibilities, likelihoods, and the prospective repercussions for guessing wrong. Imagine.
And so what?
At the end of the day, the real trick is to understand this information as it applies to you, personally. Without knowledge of your own life dreams and goals, the utility of any of this knowledge is of the most dubious value.
Now step back a minute. How do these thoughts feel? Are you energized or daunted? Empowered or bewildered? Thrilled or bored? Be honest in your answers. Money has huge emotional and personal spiritual aspects to it. Overestimating either your aptitudes or your knowledge can be both expensive and time consuming. It can most certainly be intellectually daunting and spiritually depleting.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Respite care — temporary relief for caregivers — can be costly, but a variety of funding sources and cost management strategies can help make it more affordable.
Costs and Budgeting: Average respite care costs vary by type and location. In-home respite can range from a few hours to overnight or multi-day stays, with hourly rates adding up over time. Adult day care and short-term facility stays are generally more expensive but may be more convenient for some families. Budgeting should account for both the base rate and any additional services (e.g., skilled nursing, dementia-specific care). Long-term use of respite care can have significant cumulative costs, so planning ahead is essential.
Funding Sources
Government Programs:
Medicare: Covers respite care only for patients in hospice and under specific conditions, typically up to five days at a time.
Medicaid: May cover respite care through state Home and Community-Based Services (HCBS) waivers for eligible individuals.
Veterans Affairs (VA): Offers up to 30 days of respite care per year for eligible veterans in various settings.
Private Insurance: Long-term care insurance may include respite coverage, but this varies by policy; private health or employer insurance may also cover certain services.
Out-of-Pocket: Many families pay directly, sometimes with tax deductions for qualified caregiving expenses.
Non-Profit & Community Resources: Organizations like the ARCH National Respite Network and local Area Agencies on Aging can connect families with subsidized or grant-based respite care.
Cost-Saving Strategies
Use short-term or partial-day services to reduce total hours and costs
Compare providers and rates, and consider volunteer or family caregiver options when possible.
Leverage Medicaid waivers or VA benefits if eligible.
Plan for recurring costs by setting aside a dedicated care giving budget.
Key Takeaways: Respite care funding is often a mix of public benefits, private insurance and out-of-pocket payments. Careful budgeting, eligibility checks, and use of community resources can significantly reduce the financial burden and ensure caregivers get the breaks they need.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on September 9, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
The Bureau of Labor Statistics just reported that the U.S. economy added a whopping 162,000 jobs in August, far exceeding economists’ expectations. Even better, previously reported employment gains for June and July were revised upward by a combined 55,000 jobs.
After months of disappointing economic news, this sudden surge in hiring could signal something much bigger.
It may be the beginning of the economic boom President Trump has been promising.
Artificial Intelligence in accounting leverages machine learning, natural language processing (NLP), and robotic process automation to handle repetitive and data-intensive tasks such as invoice processing, expense categorization, fraud detection, and regulatory compliance. By automating these processes, AI can reduce manual workload by up to 80%, improve accuracy, and provide real-time insights for decision-making.
Key Applications
Automated Bookkeeping and Data Entry: AI platforms like Zeni, Docyt, and Puzzle automatically categorize transactions, reconcile accounts, and generate financial statements, reducing human error and saving hours of manual work.
Invoice and Expense Management: Tools such as Vic.ai and Booke AI extract invoice data using OCR, validate it, and route approvals, while AI flags anomalies or duplicate claims.
Financial Reporting and Forecasting: AI analyzes historical data to detect trends, predict cash flow, and generate reports, helping firms make proactive financial decisions.
Fraud Detection and Compliance: AI monitors transactions in real time, identifying unusual patterns and ensuring adherence to tax and audit regulations.
Accounts Payable/Receivable Automation: AI schedules payments, matches purchase orders, and manages collections, improving cash flow and reducing late fees.
Payroll and Tax Management: AI calculates wages, deductions, and taxes accurately, flags anomalies, and ensures timely filings.
· Benefits
Time Savings: Automates repetitive tasks, freeing accountants for strategic advisory work.
Accuracy and Compliance: Reduces errors in data entry, reconciliations, and reporting while maintaining audit trails.
Scalability: Handles high transaction volumes without increasing headcount.
Real-Time Insights: Provides dashboards and predictive analytics for better financial decision-making.
· Popular AI Accounting Tools
QuickBooks Online: AI-assisted transaction categorization, reporting, and reconciliation.
Xero: Cloud-based AI for bank reconciliation, invoicing, and financial insights.
Vic.ai: Autonomous accounts payable automation with anomaly detection.
Zeni: Combines AI bookkeeping with managed finance team support for startups.
Docyt: Multi-entity bookkeeping automation with real-time reporting.
FloQast: Enterprise AI for journal entries, reconciliations, and compliance workflows .
Puzzle: AI-native ledger and month-end close automation for accounting firms.
***
***
Industry Impact
AI is reshaping accounting by reducing manual drudgery, accelerating month-end closes, and enabling advisory-focused roles. Adoption is growing rapidly, with many firms reporting over 80% automation in routine tasks and significant reductions in document analysis time. Generative and agentic AI are further expanding capabilities, allowing AI to draft reports, execute workflows, and provide predictive insights while humans retain oversight for judgment-intensive decisions.
Implementation Tips
Start with high-volume, repetitive tasks like invoice processing and bank reconciliation.
Integrate AI with existing accounting software (QuickBooks, Xero, Sage) to maintain continuity.
Maintain human oversight for audit-critical decisions and complex judgment calls.
Use AI dashboards and predictive analytics to enhance strategic decision-making rather than replace accountants. AI in accounting is no longer experimental; it is a core tool for efficiency, accuracy, and strategic growth in modern finance teams.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR- http://www.MarcinkoAssociates.com
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Posted on September 6, 2026 by Dr. David Edward Marcinko MBA MEd CMP™
***
***
The US labor market in August roused from its early summer slumber by adding 162,000 jobs, more than double what economists had expected, while the unemployment rate remained at 4.1%, new data from the Bureau of Labor Statistics showed on Friday.
August’s job gains – which are the strongest since March – mark a sharp rebound from July’s tally, which was revised up to a 21,000-job gain from a 23,000-job loss. June was also revised upwards, adding 31,000 positions. That’s up from the original estimate of 20,0000.
The number of jobs added in August was more than double economists’ expectations. They had forecast a net gain of 65,000 jobs last month and that the unemployment rate would tick up to 4.2%.
Friday’s data helps ease concerns that the job market was slowing rapidly, said Daniel Zhao, chief economist at Glassdoor.
More than five years into the pandemic, one of COVID-19’s most stubborn legacies isn’t the acute illness itself but what comes after. Long COVID—symptoms that persist for three months or longer following infection—has emerged as a sprawling, unpredictable condition affecting an estimated 7 to 23 million Americans. Unlike the flu-like symptoms of acute infection, long COVID manifests differently in nearly everyone it touches, with researchers having cataloged more than 200 distinct symptoms across virtually every organ system in the body.
The Many Faces of a Single Condition
Fatigue tops the list of complaints, but it’s not ordinary tiredness. Many patients describe post-exertional malaise, a phenomenon where even modest physical or mental activity triggers a crash that can last days. This alone reshapes daily life, forcing people to ration their energy for basic tasks like showering or grocery shopping.
Cognitive symptoms, often called “brain fog,” rank close behind. Patients report difficulty concentrating, memory lapses, and a general sense that their thinking has slowed or become unreliable. For people whose careers depend on sharp mental performance, this symptom alone can be career-altering.
The respiratory system frequently bears lasting damage too. Shortness of breath and a persistent cough can linger long after the virus has cleared, sometimes accompanied by chest pain that mimics cardiac issues. Speaking of the heart, many long COVID patients develop palpitations or a racing heartbeat, and some are diagnosed with postural orthostatic tachycardia syndrome (POTS), a condition where standing up triggers dizziness and a spike in heart rate due to dysfunction in the autonomic nervous system.
Sensory disruptions add another layer of difficulty. Loss or distortion of smell and taste—sometimes called parosmia when familiar scents become repulsive or unrecognizable—can persist for months or years, affecting nutrition, safety (missing spoiled food or gas leaks), and quality of life in ways that seem minor until experienced firsthand.
The gastrointestinal system isn’t spared either. Bloating, constipation, and diarrhea appear regularly in long COVID patients, suggesting the virus’s effects extend into the gut microbiome and digestive nerve function. Sleep disturbances compound everything else, creating a vicious cycle where poor rest worsens fatigue, brain fog, and mood.
The Mental and Emotional Toll
Long COVID doesn’t stop at physical symptoms. Anxiety and depression are common companions, sometimes triggered by the biological effects of the virus itself and sometimes by the sheer exhaustion of living with an unpredictable, often invisible illness. Many patients describe feeling dismissed by healthcare providers or family members who can’t see their suffering, since standard tests frequently come back normal despite very real impairment. This lack of validation can be as damaging as the physical symptoms themselves, eroding a person’s sense of trust in their own body and in the medical system.
Why It’s So Hard to Pin Down
Part of what makes long COVID so challenging is its sheer variability. Symptoms can wax and wane, disappear and return, or shift entirely over time. Researchers have identified distinct symptom clusters, suggesting long COVID may actually be several different conditions lumped under one label. This heterogeneity complicates both diagnosis and treatment, since no single test confirms the condition and no universal treatment protocol exists yet.
Where Things Stand Now
The encouraging news is that research has shifted from simply describing long COVID to actively testing treatments. Large-scale clinical trials are now evaluating therapies targeting fatigue, cognitive impairment, sleep disruption, and autonomic dysfunction. Progress remains incremental, and there’s still no cure, but the scientific understanding of the condition’s biological mechanisms has deepened considerably.
For now, management remains the primary approach: treating individual symptoms, pacing activity to avoid crashes, and seeking support from healthcare providers familiar with the condition. As research continues, patients and clinicians alike are hoping the coming years bring not just better symptom management, but real answers about why this virus leaves such a lasting mark on so many bodies.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com
Behavioral modification in finance refers to applying psychological principles and strategies to change financial decision-making patterns, helping individuals and institutions overcome biases and emotional influences that lead to suboptimal outcomes.
Core Concept
Behavioral finance studies how psychological factors—such as cognitive biases, emotions, and heuristics—affect the choices of investors, financial professionals, and market participants Traditional financial models assume rational, self-controlled decision-making, but in reality, people often act irrationally due to factors like overconfidence, loss aversion, herd behavior, and confirmation bias
Behavioral modification in this context means designing interventions—personal, institutional, or regulatory—that alters these patterns toward more rational, goal-aligned decisions. This can involve:
Self-awareness training to recognize personal biases.
Decision-support tools (e.g., checklists, pre-commitment devices) to reduce impulsive choices.
Structural changes in financial products or platforms to nudge users toward better outcomes.
Loss aversion – feeling losses more acutely than gains, leading to holding losing investments too long
Overconfidence – overestimating one’s knowledge or predictive ability, often resulting in excessive trading
Herd behavior – following the crowd despite contrary evidence
Anchoring – relying too heavily on initial information when making decisions.
Application Areas
Individual Investors – Behavioral modification can help retail investors avoid emotional trading, diversify properly, and stick to long-term plans.
Financial Institutions – Firms can design internal processes and training to reduce risky or irrational decisions among traders and analysts.
Regulators – Policies can be crafted to counter systemic biases, such as default options in retirement plans or disclosure requirements to reduce information asymmetry.
Example
A retirement plan might automatically enroll employees in a diversified portfolio (default option) to counteract the tendency to under invest or make frequent, emotionally driven changes to their savings This is a form of behavioral modification that leverages “nudging” to improve long-term financial outcomes.
In short, behavioral modification in finance is about using psychological insights to reshape decision-making processes so that financial choices are more consistent with rational goals and less influenced by harmful biases.
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors1738@outlook.com -OR-http://www.MarcinkoAssociates.com



 Support our online development, and advance our onground research initiatives in free market economics, as we seek to showcase the brightest Next-Gen minds.
THE ME-P DISCLAIMER: Posts, comments and opinions do not necessarily represent iMBA, Inc., but become our property after submission. Copyright © 2006 to-date. iMBA, Inc allows colleges, universities, medical and financial professionals and related clinics, hospitals and non-profit healthcare organizations to distribute our proprietary essays, photos, videos, audios and other documents; etc. However, please review copyright and usage information for each individual asset before submission to us, and/or placement on your publication or web site. Attestation references, citations and/or back-links are required. All other assets are property of the individual copyright holder.