



 Support our online development, and advance our onground research initiatives in free market economics, as we seek to showcase the brightest Next-Gen minds.
THE ME-P DISCLAIMER: Posts, comments and opinions do not necessarily represent iMBA, Inc., but become our property after submission. Copyright © 2006 to-date. iMBA, Inc allows colleges, universities, medical and financial professionals and related clinics, hospitals and non-profit healthcare organizations to distribute our proprietary essays, photos, videos, audios and other documents; etc. However, please review copyright and usage information for each individual asset before submission to us, and/or placement on your publication or web site. Attestation references, citations and/or back-links are required. All other assets are property of the individual copyright holder.


By Dr. David Edward Marcinko; MBA MEd
SPONSOR: http://www.MarcinkoAssociates.com
***
***
Why it Matters Today?
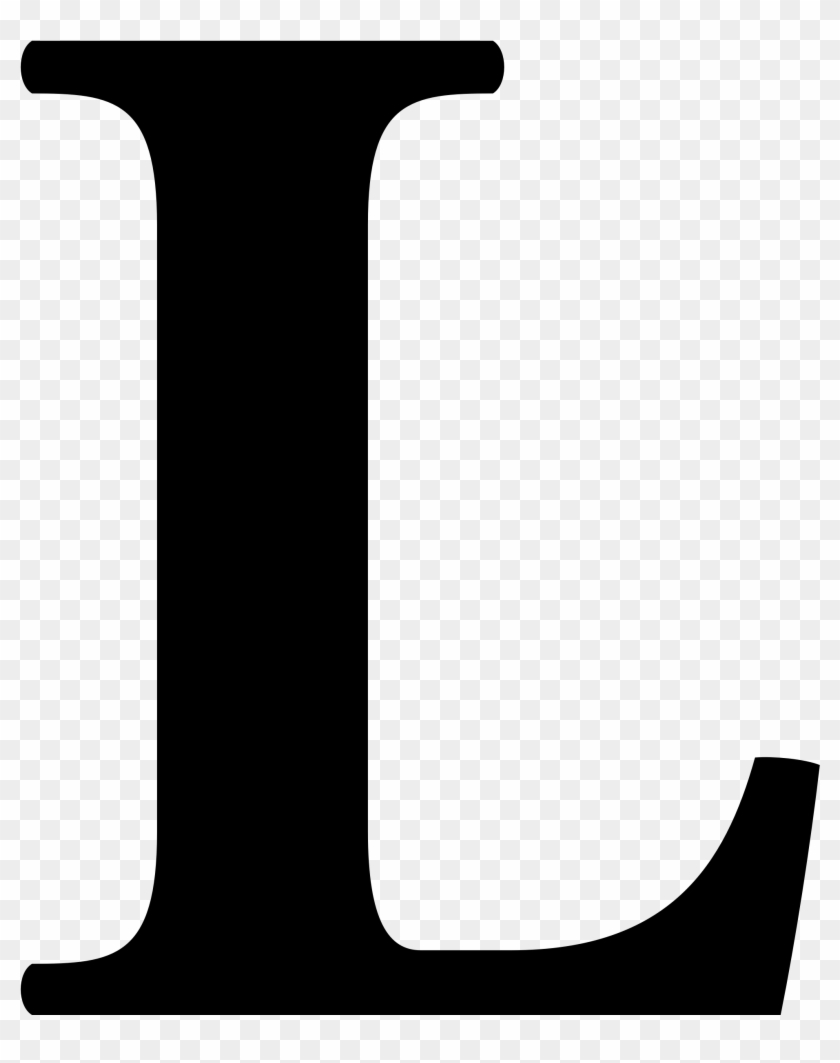
The concept of an L‑shaped economy describes one of the most troubling trajectories a nation can experience after a major economic shock. Unlike recoveries that rebound quickly or gradually, an L‑shaped pattern reflects a sharp decline followed by a prolonged period of stagnation, with little or no return to previous levels of growth. The image of the letter “L” captures this dynamic: a steep vertical drop in economic activity, followed by a long, flat horizontal line that represents years of weak or nonexistent recovery. Understanding how an economy falls into this pattern, and why it struggles to escape, is essential for grasping the long‑term consequences of severe recessions and structural weaknesses.
An L‑shaped economy typically begins with a sudden collapse in output. This may be triggered by a financial crisis, a burst asset bubble, a geopolitical shock, or a structural shift that undermines key industries. In the immediate aftermath, unemployment rises sharply, investment contracts, and consumer confidence deteriorates. What distinguishes an L‑shaped downturn from other recession patterns is not the severity of the initial decline but the failure of the economy to regain momentum. Instead of rebounding, growth remains flat for years or even decades. The forces that normally stimulate recovery—such as renewed investment, increased consumer spending, or technological innovation—fail to materialize or are too weak to overcome the underlying damage.
One of the most common drivers of an L‑shaped stagnation is the presence of overwhelming debt. When households, businesses, or governments accumulate excessive debt during boom periods, the aftermath of a crash forces them to shift from spending to repayment. This process, often called a balance‑sheet recession, suppresses demand across the entire economy. Households cut consumption, firms delay investment, and banks become more cautious in lending. Even when interest rates fall, borrowers may be unwilling or unable to take on new loans. As a result, monetary policy loses much of its effectiveness, and the economy becomes trapped in a low‑growth equilibrium.
Demographic trends can also contribute to an L‑shaped trajectory. Aging populations reduce the size of the labor force, slow productivity growth, and weaken consumer demand. When fewer young workers enter the economy, innovation and entrepreneurship may decline. At the same time, governments face rising costs for healthcare and pensions, which can limit their ability to invest in growth‑enhancing areas such as education, infrastructure, or research. In countries where birth rates fall sharply, the long‑term outlook becomes even more challenging, as shrinking populations reduce the potential for future expansion.
Financial system weakness is another critical factor. After a major crisis, banks may be burdened with bad loans, reduced capital, and heightened risk aversion. When banks hesitate to lend, businesses cannot expand, and consumers cannot finance major purchases. Credit is the lifeblood of modern economies, and when it dries up, recovery becomes extremely difficult. Even if governments attempt to stimulate growth through public spending, the private sector may remain too fragile to respond effectively.
The consequences of an L‑shaped economy are far‑reaching. For workers, prolonged stagnation means fewer job opportunities, slower wage growth, and reduced mobility. Young people entering the labor market may face years of underemployment, which can have lasting effects on their lifetime earnings and career trajectories. Older workers may struggle to adapt as industries decline or shift abroad. The sense of economic insecurity can erode social cohesion and fuel political discontent.
***
***
Businesses also suffer in an L‑shaped environment. Weak demand discourages investment, and uncertainty about future growth makes long‑term planning difficult. Firms may cut back on research and development, reducing innovation and productivity. Small and medium‑sized enterprises, which often rely on bank lending, are especially vulnerable. As weaker firms fail, industries may consolidate, reducing competition and further slowing progress.
Governments face their own challenges. With tax revenues depressed and social spending rising, public finances come under strain. Policymakers may be forced to choose between austerity, which can deepen stagnation, and increased borrowing, which may be unsustainable in the long run. Traditional policy tools, such as lowering interest rates, may be ineffective when rates are already near zero. In such cases, governments must consider unconventional measures, including large‑scale public investment, structural reforms, or targeted support for innovation and productivity.
Escaping an L‑shaped economy requires more than short‑term stimulus. It demands a comprehensive strategy that addresses the structural weaknesses holding the economy back. This may include reducing debt burdens, revitalizing the financial system, encouraging technological innovation, and adapting to demographic realities. Countries that successfully avoid or escape stagnation often do so by investing in human capital, fostering competitive industries, and maintaining flexible economic institutions.
The L‑shaped economy serves as a warning about the long‑term consequences of severe economic shocks and the importance of resilience. In a world facing aging populations, rising debt levels, and rapid technological change, the risk of prolonged stagnation is real. Understanding the dynamics of an L‑shaped trajectory helps policymakers and citizens recognize the need for proactive measures to sustain growth and ensure economic stability.
COMMENTS APPRECIATED
SPEAKING: Dr. Marcinko will be speaking and lecturing, signing and opining, teaching and preaching, storming and performing at many locations throughout the USA this year! His tour of witty and serious pontifications may be scheduled on a planned or ad-hoc basis; for public or private meetings and gatherings; formally, informally, or over lunch or dinner. All medical societies, financial advisory firms or Broker-Dealers are encouraged to submit an RFP for speaking engagements: CONTACT: Ann Miller RN MHA at MarcinkoAdvisors@outlook.com -OR- http://www.MarcinkoAssociates.com
Like, Refer and Subscribe
***
Share this:

Filed under: iMBA, Inc. | Tagged: economic-shock, economics, economy, finance, Investing, l, Marcinko, politics | Leave a comment »

 The Leading Business Education Network for Doctors, Financial Advisors and Health Industry Consultants
